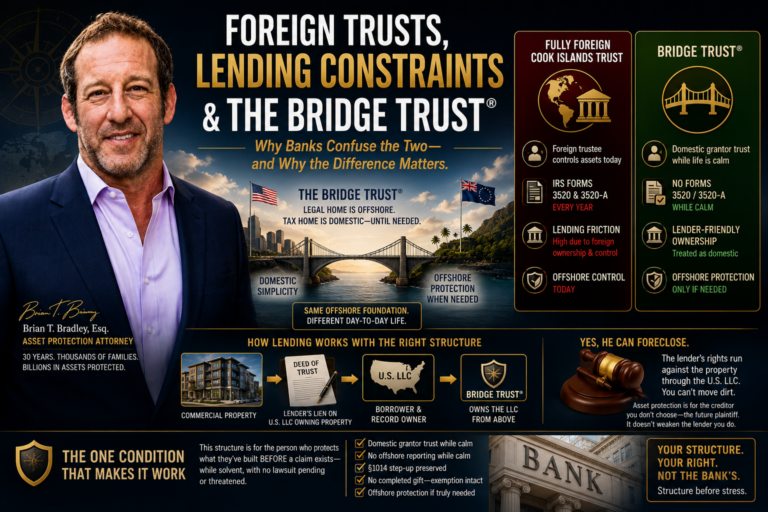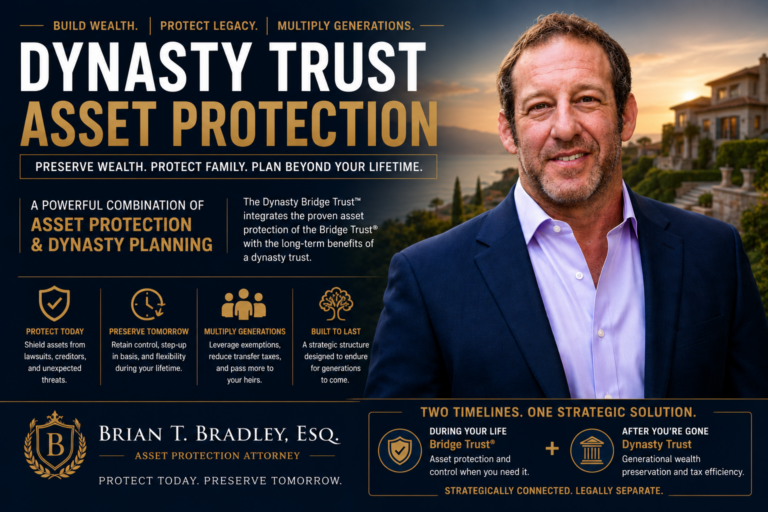
The Bridge Trust® rests on two bodies of codified law doing two different jobs. U.S. federal tax statutes — IRC §§671–677 and §7701(a)(30)(E), with Treas. Reg. §301.7701-7 — govern how it is taxed and reported. Offshore trust statutes in the Cook Islands and Belize govern what a creditor can actually do to reach the assets. Neither is a loophole. Both have been on the books for decades.
This page walks through the statutes, the regulations, and the cases that test them.
Key Points
- Two statutory tracks. Tax classification and creditor enforcement are separate legal questions with separate answers.
- Irrevocable and grantor-taxed are not in conflict. IRC §677 says so explicitly, and most practitioners have never had reason to read it.
- Registered offshore from inception, in two jurisdictions. Nothing moves at a trigger because nothing has to.
- Three failure modes defeat most structures: reactive timing, retained control, and reliance on domestic law in a domestic court. Each has a published case behind it.
- Human oversight, not an automatic trigger. A documented decision by an independent fiduciary is what makes an impossibility defense credible.
- Timing is the only variable that cannot be fixed later.
Why the Skeptic Is Right to Ask
Consider the kind of person who asks this question.
He’s a surgeon. Or a real estate investor who just closed on his twelfth property. He’s smart, he’s skeptical, and he’s heard too many people selling “asset protection” with nothing behind it but a pitch deck.
He’s also learned to watch for one thing. Some of the people selling these structures are attorneys. Many are not.
You often can’t tell at first. The website looks like a law firm. The person on the call talks like a lawyer. It’s only later — sometimes an hour into the “consultation” — that it lands: you’re not talking to an attorney. You’re talking to a salesman. No legal advice is being given, and no attorney-client privilege is protecting a word of what you just shared.
That is not a technicality. In asset protection you hand over the most sensitive facts you have — what you own, what you’re afraid of, which lawsuit keeps you up at night. With a licensed attorney, that conversation is privileged. With a “legal solution provider,” it’s a sales record. And a sales record can be found.
So when someone describes a trust that operates under Cook Islands law and can shift offshore when a lawsuit hits, his first thought isn’t excitement. It’s prove it.
That’s the right instinct. Here is the proof.
⸻
Why Do Most Asset Protection Structures Fail?
Three reasons, and each has a published case behind it. The structure was built after the threat was foreseeable. The settlor kept control he should have relinquished. Or the plan relied on domestic law to protect assets sitting inside a domestic court’s reach.
Jurisdiction — Toni 1 Trust v. Wacker
Toni 1 Trust v. Wacker, 413 P.3d 1199 (Alaska 2018).
Alaska wrote one of the first domestic asset protection trust statutes in the country, and included language declaring that only an Alaska court could hear a challenge to an Alaska trust.
Then Alaska’s own Supreme Court held that the language does not work. A creditor can sue in another state or in federal court, and that court can apply its own fraudulent-transfer law regardless of what the Alaska statute says. That is the Full Faith and Credit Clause (U.S. Const. art. IV, §1) doing exactly what it was written to do.
No state can wall its trusts off from the rest of the country’s courts — decided by the very state that built the tool.
Timing — Battley v. Mortensen
Battley v. Mortensen, 2011 WL 5025288 (Bankr. D. Alaska 2011).
Thomas Mortensen funded an Alaska self-settled trust while solvent, with no lawsuit pending and no claim on the horizon. On paper he did it right.
Years later he filed bankruptcy, and the court unwound the trust anyway under 11 U.S.C. §548(e) — the ten-year federal reach-back that applies specifically to self-settled trusts.
Read that number again. Ten years. Solvency at the time of transfer did not save it.
Control and choice of law — In re Huber
In re Huber, 493 B.R. 798 (Bankr. W.D. Wash. 2013).
Donald Huber, a Washington resident, created an Alaska trust to borrow Alaska’s protective law. The court refused to apply it and applied Washington law instead — where he lived, where the assets were, where the real connection existed. Washington voids self-settled spendthrift trusts. The trust collapsed.
You cannot shop for a friendlier state’s law while living and operating somewhere else.
Three cases, three failure points, one lesson: a structure that never leaves the U.S. legal system stays inside the reach of a U.S. judge.
The U.S. Tax Foundation
The trust is a grantor trust under IRC §§671–677, so income is reported on the settlor’s personal return. Separately, it satisfies the court and control tests of Treas. Reg. §301.7701-7 and is therefore classified as domestic under IRC §7701(a)(30)(E). Two independent rules answering two different questions.
Grantor trust status — IRC §§671–677
Under the grantor trust rules, when a grantor retains certain interests or powers, the trust’s income, deductions, and credits are reported directly on the grantor’s personal return. The trust pays no income tax. The grantor does, exactly as if they still owned the assets.
Here is the point most practitioners miss: irrevocability and grantor-trust taxation are completely separate legal concepts.
A trust can be irrevocable — the grantor cannot simply reclaim the assets — and still be a grantor trust for tax purposes. IRC §677 treats income as belonging to the grantor when it can be distributed for the grantor’s benefit, even when the trust cannot be revoked.
That is not a workaround. It is what the statute says.
Many CPAs and general-practice attorneys rarely encounter this combination, and when they first see it they assume something must be wrong. The answer is to read the statute.
The regulations
Treas. Reg. §1.671-1(b) clarifies that grantor trust treatment affects tax reporting only. It does not merge the trust with the grantor for other legal purposes. Tax reporting does not determine legal control of assets.
Treas. Reg. §1.671-4(b)(2) permits certain grantor trusts to report under the grantor’s Social Security number rather than a separate EIN. That option exists because the IRS recognizes irrevocable grantor trusts as legitimate and common.
Domestic classification — IRC §7701(a)(30)(E)
Whether a trust is domestic or foreign for tax purposes is a different question, governed by IRC §7701(a)(30)(E) and the two-part test in Treas. Reg. §301.7701-7:
The court test — a U.S. court can exercise primary supervision over administration.
The control test — U.S. persons control the trust’s substantial decisions.
While the Bridge Trust® operates domestically it satisfies both, so it is treated as a domestic grantor trust for tax purposes even though the governing instrument provides for a foreign successor trustee and offshore situs on duress.
In plain English: trust income is reported on your personal return, no separate trust taxation occurs, and the IRS sees everything. Nothing is hidden.
Is This a Domestic Trust That Becomes Foreign?
No. It is registered offshore from the day it is signed — in the Cook Islands and in Belize. Two jurisdictions, two registrations, both in countries whose courts will not enforce a U.S. judgment against the trust. Nothing moves at a trigger because nothing has to.
This is the part most people get wrong, including most critics.
This is a Cook Islands trust with formal registration on file from execution. Not a domestic trust with an offshore clause bolted on. Not a trust that “becomes” foreign if a lawsuit appears. Foreign from inception — in law and on the register.
And it is registered in Belize as well.
That is what “the bridge” actually means. On one side, the trust reports to the IRS as a domestic grantor trust — a normal 1040, full transparency. On the other, its legal home has been offshore the entire time. Two passports held at once: a U.S. tax passport and an offshore legal passport.
So the skeptic’s version — “it moves offshore once you get sued” — describes a different, weaker product. Nothing moves, because nothing has to. The offshore registration already exists, which is why there is no transfer to attack at the worst possible moment.
The Offshore Legal Foundation
Three jurisdictions built their trust law expressly to reject foreign judgments: the Cook Islands, Nevis, and Belize. This structure is registered in two of them. The barriers are non-recognition of foreign judgments, a criminal-standard burden of proof, short limitation periods, and trustees legally constrained from honoring foreign orders.
The Cook Islands International Trusts Act 1984, strengthened through multiple amendments, has the longest track record and the most-tested body of law, so it makes the clearest worked example.
No recognition of foreign judgments
A U.S. judgment has no automatic legal effect in the Cook Islands. A creditor who wins $10 million in California cannot present that judgment and collect. They must file a new lawsuit in the Cook Islands, prove the claim under Cook Islands law, and overcome the statutory protections.
That is not a loophole. It is a deliberate legislative decision by a sovereign nation.
Criminal-level burden of proof
A creditor challenging a transfer must prove beyond a reasonable doubt both that the transfer was made with intent to defraud that specific creditor, and that it rendered the settlor insolvent at the time.
That is the standard used to convict someone of a crime. Most U.S. fraudulent transfer claims require only a preponderance of the evidence.
Strict limitation periods
Cook Islands law imposes short deadlines, and the clock runs from the transfer rather than from when a lawsuit is filed. Once the window closes, the claim is permanently barred.
Trustees are legally constrained from honoring foreign orders
A licensed offshore trustee operates exclusively under local law. Complying with an order from a foreign court that has no local jurisdiction exposes that trustee to personal legal liability and loss of license.
That is not uncooperativeness or discretion. It is a professional consequence, and it is why a U.S. repatriation order directed at the trustee has no practical effect.
Bond requirements and fee-shifting — and a distinction that matters
A creditor faces substantial upfront cost, and fee-shifting can leave a losing claimant paying both sides’ legal costs. That combination eliminates contingency-fee litigation. No plaintiff’s lawyer pursues offshore litigation on contingency.
But the specifics differ by jurisdiction, and most content on this topic gets it wrong.
Nevis mandates a bond by statute. Under §61 of the Nevis International Exempt Trust Ordinance (Cap. 7.03), a creditor must deposit EC$270,000 with the Ministry of Finance before bringing an action against trust property — $100,000 USD at the fixed 2.70 peg, and the court may require more.
The Cook Islands has no equivalent mandatory cash bond. The International Trusts Act 1984 does not impose one. Its barriers operate through non-recognition, the criminal burden, limitation periods, and costs-shifting instead.
Different architecture, not different strength. Conflating the Nevis statutory bond with Cook Islands law is one of the most common errors in comparative offshore analysis.
And Belize goes one step further
Under the Belize Trusts Act (Chapter 202), a qualifying international trust is walled off from foreign-law fraudulent-conveyance claims by statute. Section 7 overrides the older Statute-of-Elizabeth provision Belize once inherited. The result is a jurisdiction with no limitation clock to run at all.
Say plainly what that does and does not mean. It does not let anyone move assets ahead of a creditor and run — a U.S. court still has power over the person, and this trust is built to be funded long before any claim exists. What it means is that once you are properly and timely inside the structure, the offshore forum a creditor would have to fight in is even less hospitable than the Cook Islands.
Two registrations. Two hostile forums. No single point of failure.
What Does the Case Law Actually Show?
That courts sanction people, not statutes. When critics point to offshore trusts that “failed,” the cases fall into four buckets — retained control, reactive timing, a non-creditor obligation like a criminal fine or divorce judgment, or a court jailing a debtor it could not otherwise reach. Look closely and the trust usually did its job.
Statutes create legality. Case law interprets statutes when disputes arise. When a structure operates squarely within what the statute permits, courts have little reason to intervene — which is why offshore asset protection litigation rarely produces long appellate opinions.
Several U.S. cases still provide essential context.
FTC v. Affordable Media — the Anderson case
FTC v. Affordable Media, LLC, 179 F.3d 1228 (9th Cir. 1999) is the most cited and most half-quoted case in this field.
The timing was not the defect. The trust was established in July 1995. The FTC filed in April 1998 — nearly three years later.
Control was. Michael and Denyse Anderson named themselves co-trustees and trust protectors of their own trust. As protectors, they retained the power to override an event of duress or replace the trustee.
When the court ordered repatriation, the Cook Islands trustee declared duress, removed them as co-trustees, and refused. When they tried to install their children as replacement trustees, the trustee removed those appointees too. The mechanism held twice, under direct federal pressure, against parties actively trying to satisfy the court.
The Ninth Circuit affirmed contempt anyway, because holding a live control mechanism meant they could not establish impossibility of compliance. They were incarcerated.
Then the FTC took the fight offshore and lost there too. On August 10, 1999, the Cook Islands High Court ruled against the FTC entity on every point it raised and awarded costs against it in favor of the trustee. The matter later settled. The assets never came back.
A U.S. court may sanction individuals within its jurisdiction. It does not thereby gain control over assets governed by a foreign trustee under foreign law. What failed was not the offshore jurisdiction. It was the domestic side of the structure — because the grantors insisted on keeping protector powers over an offshore entity.
United States v. Grant — where the impossibility defense worked
Ordered to repatriate against a $36 million IRS liability, Mrs. Arline Grant complied with the request. When the trustee refused, she attempted to replace the trustee. She was unsuccessful for more than two years.
In 2008 the court found the failure was not for lack of effort, held that she had established she was genuinely unable to repatriate, and denied the government’s motion.
Grant also produced a specific drafting instruction. The trust gave her “non-reviewable, sole and complete discretion to remove and replace the Trustee at any time” — a power that nearly sank her. The fix is a single clause: make that power exercisable only when the beneficiary is not acting under duress.
That is exactly what this instrument does, and it is why the grantor’s appointment and removal powers are suspended the moment duress is declared.
The underlying rule — Maggio v. Zeitz
Civil contempt requires a present ability to comply. The Supreme Court confirmed it in Maggio v. Zeitz, 333 U.S. 56 (1948).
When a properly structured trust places control with an independent offshore trustee, the settlor may no longer have that ability. Real separation of control is what makes the impossibility defense legitimate — and Anderson is the reminder that courts will find self-created impossibility where the settlor built the barrier and kept a key.
In re Rensin — the honest boundary
In re Rensin, 600 B.R. 870 (Bankr. S.D. Fla. 2019) is the case that most rewards careful reading, because it is not a clean win.
Joseph Rensin, a Florida businessman, set up an offshore trust under Cook Islands law and later migrated it to Belize — the same two jurisdictions this structure uses. Strong offshore footprint on paper.
Here is what he did wrong. He was the settlor and a discretionary beneficiary of his own trust, and he treated it like a checking account. Roughly $8.6 million flowed to him or for his benefit over the years.
In bankruptcy, the court applied Florida law to determine what a Florida creditor could reach, notwithstanding the Belize choice-of-law clause. Every distribution payable to Rensin was fair game, and his exemption arguments failed.
But note what the court could not do. It could not compel the offshore trustee to hand over assets held beyond U.S. jurisdiction. Foreign situs still drew a hard line around the part of the trust Rensin did not control.
That is the whole lesson in one case. Offshore situs is necessary — it protected what a U.S. court could not reach. It is not sufficient. Retain a beneficial interest, pay yourself distributions, and a domestic court will reach exactly that, no matter where the trust is registered.
It is also why this instrument does the opposite of what Rensin did. Distribution discretion rests solely with the trustee. The client cannot compel a distribution to himself. What sank Rensin is the specific thing the drafting prevents.
Why Human Oversight Instead of an Automatic Trigger?
Because a clause that fires mechanically on a litigation event reads to a court as pre-programmed obstruction, and because it erases the fiduciary judgment an impossibility defense depends on. A documented decision by an independent professional puts a witness on the record who can testify to reasoned judgment.
Some offshore structures rely on automatic triggers — mechanisms that attempt to shift the trust offshore the moment a lawsuit is filed. Courts view those provisions with skepticism, and for good reason.
The Bridge Trust® uses human oversight instead.
An independent attorney serves as Trust Protector — a separate professional party, not the settlor and not subject to the same court orders. When a legitimate legal threat arises, the Protector may issue a written Declaration of Duress, in the Protector’s own discretion.
Once duress is declared, the instrument operates: standing consents are revoked, the grantor’s powers to appoint or remove the Protector and successor trustee are suspended, distributions are suspended, and further amendments are barred. The settlor does not have to act, and cannot act.
The Protector may then appoint the Special Successor Trustee — a licensed independent offshore trust company that is a signatory party to the trust from the beginning, not merely named in it, with KYC, due diligence, and onboarding completed years in advance. From that point the trustee acts under offshore law, not U.S. court authority.
This is the Anderson fix. The Andersons stayed in the loop and kept the power to reverse the freeze. Here the settlor’s relevant authority is stripped the moment an independent professional declares, leaving nothing for a court to order the settlor to exercise.
The Compliance Record
The Bridge Trust® is not designed to hide assets. It operates transparently under U.S. tax law.
While the trust operates domestically, income is reported directly on the grantor’s personal return. If a foreign trustee is activated, additional reporting requirements may apply, including Form 3520, Form 3520-A, FinCEN Form 114 (FBAR), and Form 8938.
Every dollar remains reportable. Protection comes from jurisdictional law, not from hiding assets from the IRS.
“If This Works, Why Isn’t There More Case Law?”
Because statutes create legality and courts issue opinions when disputes arise. A structure operating within the clear boundaries of a statute gives courts little to interpret — and deterrence resolves matters before they produce published opinions.
If you drive within the speed limit, there is no police report about your trip. The absence of enforcement action is not proof that the law failed. It is evidence the law was followed.
There is a second reason, and it is economic. A creditor facing non-recognition of the judgment, a criminal-standard burden of proof, a short limitation window, and costs-shifting usually revalues the claim rather than litigating it abroad. Settlements are private. Cases that never get filed produce no opinions.
The Formula in Plain English
The Bridge Trust® is a trust that reports to the IRS like a domestic trust while being governed by foreign jurisdictions that U.S. courts do not control.
Tax transparency comes from IRC §§671–677 and §7701, with Treas. Reg. §301.7701-7.
Jurisdictional protection comes from the Cook Islands International Trusts Act 1984 and the Belize Trusts Act, Chapter 202.
Structural integrity comes from genuine control separation through independent fiduciaries.
The protection works only when three conditions are satisfied:
Timing — the structure exists before a claim arises. Control — the settlor does not secretly control the assets. Jurisdiction — an independent offshore trustee operates under a foreign statute.
Miss any one and the structure fails. Get all three right and the enforcement barriers become very real.
FAQs
Is the Bridge Trust® legal? Yes. It is built on IRC §§671–677 and §7701 for U.S. tax treatment, and on the Cook Islands International Trusts Act 1984 and Belize Trusts Act Chapter 202 for creditor protection. All are codified statutes that have existed for decades.
Can a trust be irrevocable and still be a grantor trust? Yes, and this is the point most CPAs question first. IRC §677 treats income as the grantor’s when it can be distributed for the grantor’s benefit, even where the trust cannot be revoked. The two concepts are independent.
Is this a domestic trust that converts to offshore? No. It is registered offshore from execution, in the Cook Islands and Belize. “Domestic” describes only its tax classification under §7701 while no threat exists.
Does it reduce my taxes? No. It is tax-neutral by design. Income is reported on your own return and the IRS sees everything.
Who decides when the offshore protection activates? An independent attorney serving as Trust Protector, by written Declaration of Duress, in the Protector’s discretion. There is no automatic trigger.
Can a U.S. court order my trustee to return the assets? It can order a person within its jurisdiction to act. It has no mechanism to compel a licensed foreign fiduciary who would face personal liability and loss of license for complying.
Why isn’t there more case law proving this works? Because deterrence resolves matters before they produce opinions, and because a structure operating within a statute gives courts little to interpret. Anderson is the closest documented example — the FTC could not reach the assets, lost in the Cook Islands, and settled.
What is the one thing that can’t be fixed later? Timing. Every other variable can be designed around. A structure built after a claim is foreseeable is a voidable transfer, and no amount of drafting cures it.
Conclusion: Law, Not Loopholes
The Bridge Trust® is not based on loopholes. It is built on statutes.
The Internal Revenue Code permits irrevocable grantor trusts. Offshore law in the Cook Islands and Belize restricts foreign creditor enforcement. Treasury regulations confirm that tax reporting and asset control are separate legal questions.
These statutes have existed for decades.
The only question that truly matters is timing. Was the structure built before it was needed? Because once a lawsuit appears, the law changes — and no structure built after the fact can fix that.
Structure before stress.
📞 For a confidential legal consultation, contact Bradley Legal Corp. at (888) 773-9399, or complete the intake questionnaire at btblegal.com.
By: Brian T. Bradley, Esq.