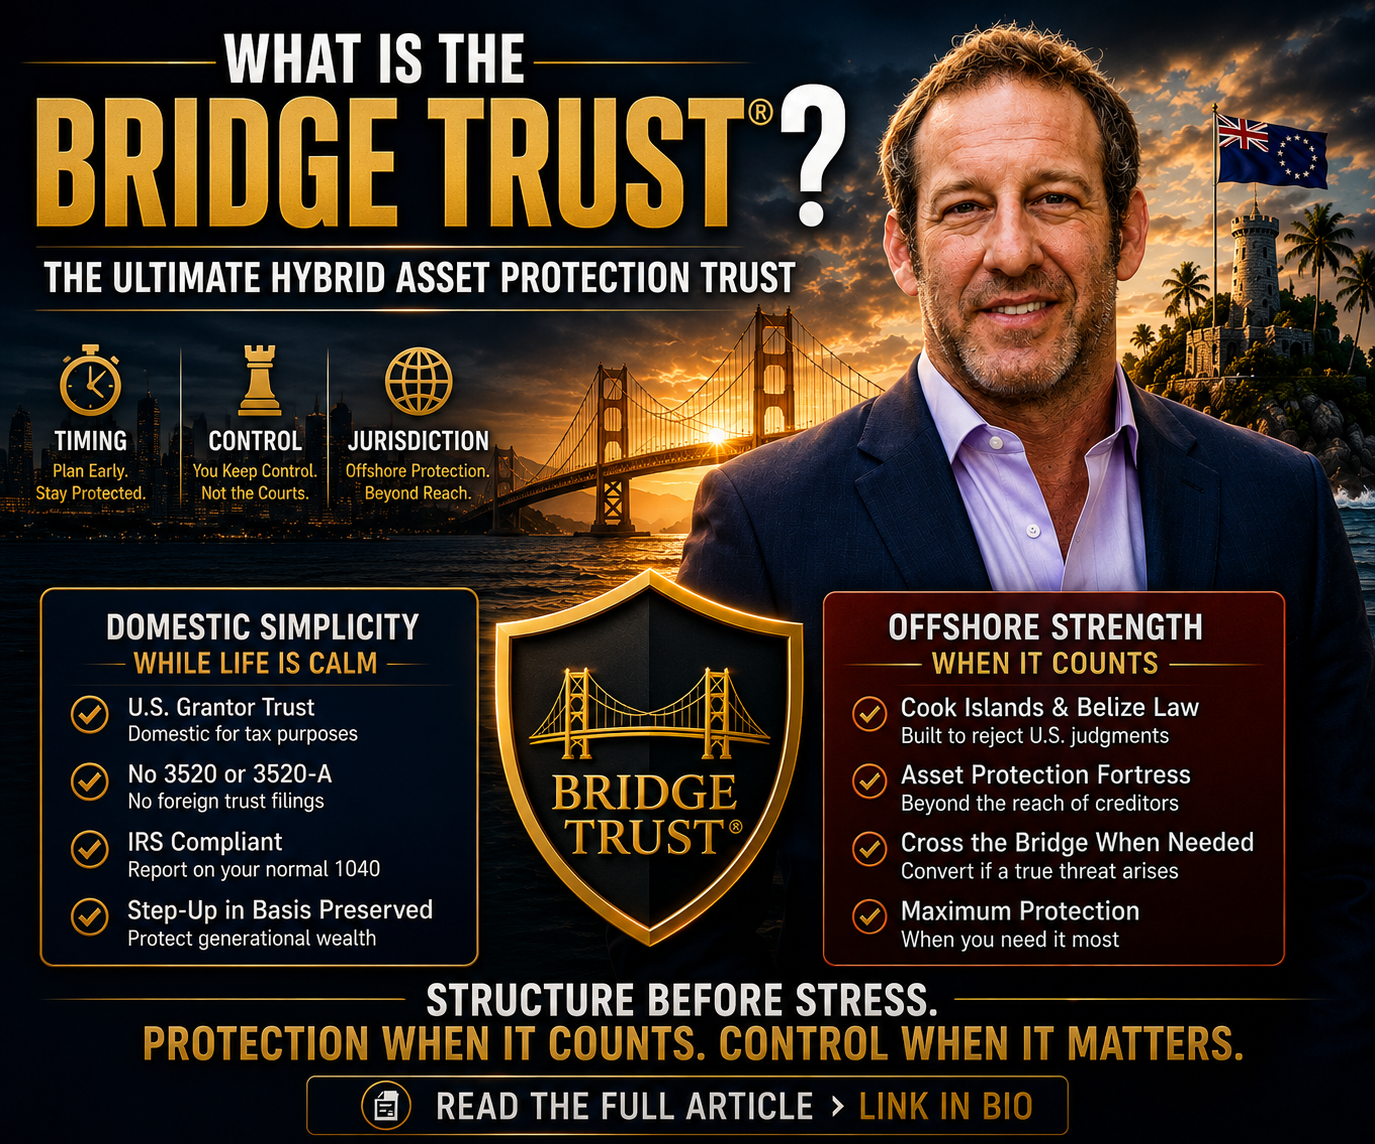
The Bridge Trust® is a single asset-protection trust with an offshore legal foundation — in a jurisdiction such as the Cook Islands — that the IRS classifies as a domestic grantor trust for tax purposes under IRC §7701. It is foreign by nature and domestic by election. It is tax-neutral, fully reportable, and has been in use for roughly 30 years.
If you have assets worth protecting and real exposure to litigation, this guide explains how the structure works, what the case law actually says, and who it is — and is not — for.
Key Points:
• One trust, not two. The offshore legal foundation exists from inception. Nothing is created, transferred, or decanted when the trust shifts to offshore administration.
• Two separate questions, two separate answers. Legal character is foreign. Tax classification is domestic. Those are not competing identities.
• Tax-neutral by design. It does not reduce, defer, or hide tax. Income is reported on your own return under the grantor-trust rules.
• Not a DAPT. It does not rely on any state asset-protection statute, which is why the line of cases that defeat domestic asset-protection trusts does not reach it the same way.
• The transition is discretionary, not automatic. An independent Trust Protector exercises fiduciary judgment. There is no mechanical “lawsuit-filed” switch.
• Timing is the whole game. Structuring before a claim is foreseeable is legitimate planning. Structuring after is where fraudulent-transfer exposure lives.
• No structure guarantees an outcome. What it changes is the position you negotiate from.
What Problem Does the Bridge Trust® Actually Solve?
It solves the trade-off between convenience and protection. Domestic trusts are easy to run but never leave the reach of the U.S. court system. Fully offshore trusts are powerful but carry real cost and annual filing burden from day one. The Bridge Trust® holds the offshore protection in reserve and deploys it only if a serious threat appears.
Asset-protection failures almost always fall into one of two buckets.
A domestic trust is convenient. It is also fully subject to U.S. court jurisdiction, which means a determined creditor with a judgment and a motivated forum has a path to it.
A fully offshore trust removes that ceiling. But it also brings offshore administration cost, Form 3520 and 3520-A filings, FBAR reporting, and assets you cannot access without a foreign trustee’s cooperation — starting immediately, whether or not a serious threat ever materializes.
The Bridge Trust® was built for the client who wants the second level of protection without carrying the second level of operational burden for a risk that may never arrive.
Think of it as a hybrid engine. Efficient and fully compliant under normal conditions. Capable of deploying maximum legal defense when real litigation risk appears.
A Story That Explains the Problem
The following is a composite illustration drawn from patterns I see in practice. It is not an actual client.
Dr. Sarah Chen had built exactly what she set out to build. Twelve years out of residency, running a successful orthopedic surgery practice. Four rental properties. Roughly $2.3 million in investable assets outside her retirement accounts. And she had just been named in her third malpractice claim in eighteen months — none with merit, all of them expensive.
Her malpractice insurer covered the defense. But the policy had limits, and Sarah had done the math. One bad jury, one runaway verdict, and twelve years of work was on the table.
She had researched her options. She understood what an offshore trust could do — non-recognition of foreign judgments, a criminal-level fraud burden, short limitation windows. She also understood what it costs to run one, and she did not want to carry a full offshore operation indefinitely for a risk that might never materialize.
She wanted the protection without the permanent operational weight. That gap is exactly what the Bridge Trust® was designed to close.
⸻
How Does the Bridge Trust® Work, Step by Step?
The trust is created with its offshore legal architecture already in place, administered domestically while conditions are calm, and taxed as a U.S. grantor trust the entire time. If a credible threat appears, an independent Trust Protector may shift administration offshore to a pre-committed Special Successor Trustee. No new trust is created at that moment.
1. Created with an offshore legal foundation from inception
From day one the trust is built on offshore trust law — an offshore jurisdiction such as the Cook Islands. A Special Successor Trustee is engaged from the start: pre-vetted, onboarded through full KYC and compliance, and a signatory party to the trust agreement itself, not merely named in it.
This matters because the foundation is not assembled in a panic at the moment of crisis. It exists at inception and stays dormant until it is needed.
That distinction is doing real legal work:
• Planning done before a claim arises is legitimate structuring.
• Planning done after a claim appears can be attacked as a fraudulent transfer.
2. Classified as a U.S. grantor trust for tax purposes
While administered domestically, the trust satisfies the two-part test in Treas. Reg. §301.7701-7 — the Court Test (a U.S. court exercises primary supervision) and the Control Test (U.S. persons control substantial decisions) — so the IRS treats it as a domestic trust under IRC §7701(a)(30)(E).
Separately, the instrument is drafted to establish and maintain grantor-trust status under IRC §§671–677, so trust income is reported on your own return and the trust is disregarded for income-tax purposes.
Those are two different rules doing two different jobs. The court/control test determines domestic-versus-foreign classification. The grantor-trust rules determine who reports the income. Conflating them is one of the most common errors I see in commentary about this structure.
The design is deliberately tax-neutral, not tax-avoidant. It does not reduce, defer, or hide tax. It changes where your assets are legally protected, not what you owe.
3. Operates domestically while conditions are normal
Day to day, the trust functions much like a domestic trust. Assets are managed domestically. The offshore legal framework stays embedded in the governing instrument, and the offshore trustee relationship already exists — dormant, but live.
4. Transitions only if a credible threat arises
If a serious legal threat appears — a major lawsuit, creditor enforcement, a judgment, a government investigation — the trust may shift to offshore administration.
The word “may” is load-bearing. Under the governing instrument, declaring an Event of Duress does not by itself change situs, governing law, or trustee. It opens a discretionary menu available to the Trust Protector. There is no mechanical trigger a court can characterize as a pre-programmed obstruction clause.
5. Human oversight through an independent Trust Protector
The decision to activate offshore administration rests with an independent Trust Protector exercising fiduciary judgment. There are no automatic triggers, no pre-programmed switches, and no hidden transfers. Every step is deliberate and legally supervised.
That design is what keeps the structure defensible while ensuring the offshore defense is available when it is genuinely warranted.
Is the Bridge Trust® Really Just a Domestic Trust?
No. It is one trust with an offshore legal foundation that the IRS classifies as domestic for tax purposes only. Legal character and tax classification are separate questions with separate answers. The trust is foreign by nature and domestic by election — and a creditor runs into the foreign half.
This is the most common misunderstanding about the structure, and the one worth getting exactly right.
Some people assume the Bridge Trust® is two trusts — one domestic, one offshore — with assets shuffled between them when a threat appears. Others describe it as “both domestic and offshore at once.” Neither is accurate.

Two comparisons make it click.
A dual citizen carrying two passports. Still one person, simply recognized by two systems. The Bridge Trust® is one trust — foreign for legal and asset-protection purposes, domestic for tax.
A green-card holder. A citizen of another country who is nonetheless taxed as a U.S. resident. Foreign in legal status, domestic for tax. No contradiction there either.
What actually happens at the moment of transition?
No new trust is created. No assets are transferred. No decanting occurs.
What changes is administration and tax posture. The U.S. tax classification is dropped and control moves to the pre-committed Special Successor Trustee. The trust that existed yesterday continues to exist today. Its offshore foundation was there the whole time.
This is not a technicality. Creditors sometimes argue that the transition is itself a fraudulent transfer. Under this structure there is no transfer at the trigger — only a change in how an existing, already-offshore-founded trust is administered and taxed.
Is the Bridge Trust® Legitimate, or Is It a Scam?
It has been in existence and used for over 30 years, with thousands of clientsIt, protecting billions in assets. Yes, it is legitimate when it is structured and funded before litigation is foreseeable. It rests on two well-established bodies of law — offshore trust statutes for jurisdiction, and U.S. grantor-trust tax law for transparency. It relies on jurisdictional separation, not secrecy, and every dollar remains reportable.
The word “offshore” carries baggage it has not earned in this context. Secrecy structures and tax-evasion schemes are a different animal, and they are illegal for reasons that have nothing to do with trust law.
Here is the honest test. A legitimate asset-protection structure:
• reports every dollar to the IRS,
• does not reduce or defer a single dollar of tax,
• is funded before a claim is foreseeable, and
• puts genuine legal authority in the hands of someone the client cannot compel.
The Bridge Trust® is built to satisfy all four. A structure that fails any of them is not asset protection — it is a fraudulent transfer or a tax scheme wearing a trust’s clothing, and the courts treat it accordingly.
What I will not tell you is that any structure makes assets untouchable. Nothing does. What a properly built structure changes is the position you negotiate from when a claim arrives.
Bridge Trust® vs. DAPT vs. Fully Offshore vs. Living Trust: What Actually Protects What?
A revocable living trust provides no lifetime creditor protection. A domestic asset-protection trust depends on another state’s court honoring your chosen state’s statute. A fully offshore trust protects but carries permanent cost and filing burden. The Bridge Trust® holds offshore protection in reserve at domestic operating cost.

Why Do Domestic Asset Protection Trusts Keep Failing in Court?
Because a DAPT relies on a state statute, and the state where you organize a trust is not necessarily the state where the fight gets enforced. When the creditor, the assets, or the debtor touches another state — or a federal court — that forum can apply its own law and public policy under the Full Faith and Credit Clause.
This is the structural weakness, and it is not a matter of opinion. Courts have done it repeatedly.
Toni 1 Trust v. Wacker, 413 P.3d 1199 (Alaska 2018) — published state supreme court authority, and the cleanest holding in this line. Alaska’s own high court held that a state DAPT statute cannot stop other states or federal courts from applying their own fraudulent-transfer law and jurisdiction. When the state that wrote the statute says the statute has limits, that settles the question.
In re Huber, 493 B.R. 798 (Bankr. W.D. Wash. 2013) — bankruptcy court applied the settlor’s home-state Washington law rather than the trust’s chosen Alaska law.
Battley v. Mortensen, 2011 WL 5025288 (Bankr. D. Alaska 2011) — an Alaska DAPT was voided in bankruptcy under 11 U.S.C. §548(e), the ten-year reach-back for self-settled trusts, even though the settlor was solvent at the time of transfer. Bankruptcy court decision.
Dahl v. Dahl (Utah 2015) — the forum state’s law was applied over the trust’s stated governing law. Worth keeping straight: this arose in a divorce, not a creditor enforcement action, which limits how far it travels.
Kilker v. Stillman (Cal. Ct. App. 2012) — a California court disregarded a Nevada asset-protection trust for a California-resident settlor. This opinion is unpublished and non-citable as authority under California Rule of Court 8.1115. I include it as an illustration of judicial attitude, not as precedent, and anyone citing it as binding authority is overreaching.
United States v. Huckaby, No. 2:23-cv-00587-DAD-JDP (E.D. Cal. Mar. 2, 2026) — the most recent and most instructive. A self-settled Nevada spendthrift trust could not shield California real property from a federal judgment lien. Although the trust designated Nevada law for construction (Restatement (Second) of Conflict of Laws §277), the court held that California law — the law of the situs of the land — governs whether a creditor can reach a beneficiary’s interest (Restatement (Second) §280). The trust was self-settled because the same people were trustors, settlors, trustees, and beneficiaries, and Cal. Prob. Code §15304 voids self-settled spendthrift protection. The lien reached the property under 28 U.S.C. §3201(a). This is a district-court order granting partial summary judgment, not appellate authority — but the reasoning is clean and the fact pattern is common.
The pattern across all six is consistent: a domestic trust never leaves the U.S. system, so a determined U.S. court can reach it. An offshore legal foundation is what removes that ceiling.
There is a corollary worth stating plainly, because it comes up on every real-estate call: you cannot move dirt. Land is governed by the law where it sits. Protection for real estate works by structuring and protecting the equity, not by relocating the property.
What Does Offshore Trust Law Actually Do to a Creditor’s Claim?
It changes the economics of collection. A U.S. judgment is not directly enforceable, so the creditor must re-litigate from scratch in a foreign forum, under a criminal-level burden of proof, within a short limitation window, after posting a substantial bond. Most claims never justify the trip.
The Cook Islands International Trusts Act (1984, substantially amended in 1989) is the statute most people mean when they say “offshore trust.” Nevis offers materially comparable protection. The core features:
1. Non-recognition of foreign judgments. A U.S. judgment is not directly enforceable. The creditor has to re-litigate the underlying claim locally, from the beginning.
2. A criminal-level burden of proof. Fraudulent transfer must be proven beyond a reasonable doubt — the highest burden in any comparable jurisdiction — and the creditor must also prove the transfer left the settlor insolvent.
3. Strict limitation periods. Claims are barred after a short window measured from the transfer.
4. Duress and repatriation protections. Offshore trustees are constrained from complying with foreign court coercion or repatriation demands.
5. A substantial upfront bond and fee-shifting. A creditor generally must post a significant bond to bring the claim and faces fee-shifting if it loses.
6. Long-term duration. These trusts can run for a century or more, which supports multigenerational planning.
This is real statutory law, not marketing language. And the practical effect is the point: most creditors do the math on that list and never board the plane.
What Does the Case Law Really Say About Offshore Trusts?
Courts do not defeat a properly structured offshore trust because it is offshore. Failures trace to three things: reactive planning, improper retained control, or a fraudulent transfer. The published cases are consistent about this, including the ones critics cite most often.
FTC v. Affordable Media, LLC, 179 F.3d 1228 (9th Cir. 1999) — the “Anderson” case, and the one most frequently quoted at half its length. Both halves matter.
The half critics quote: the Andersons stayed on as co-protectors of their own offshore trust, and the Ninth Circuit held the district court did not abuse its discretion in rejecting their impossibility defense and holding them in contempt.
The half almost nobody finishes: the Cook Islands trustee refused to repatriate, and the assets stayed offshore. The foreign jurisdiction held. What failed was the Andersons’ retained control — because they were still co-protectors, their inability to comply was self-created.
Anderson is never a clean win and never a clean loss. It is the clearest argument in the entire case bank for separating roles: the person under U.S. compulsion must not be the person holding the relevant authority.
SEC v. Solow, 554 F. Supp. 2d 1356 (S.D. Fla. 2008) — a lesson in what after-the-fact conduct does to your position. Transfers made after notice tainted assets that would otherwise have been exempt, and the court rejected the impossibility defense on the ground that self-created penury excuses nothing. This is not an offshore win and I do not present it as one. It is the strongest available argument for the thesis of this entire page: build the structure before a claim is visible, and once one appears, do nothing without counsel.
United States v. Grant (S.D. Fla.) — the “Arline Grant” litigation, where the impossibility defense worked because control had genuinely been relinquished. Ordered to repatriate, Mrs. Grant tried — she even attempted to replace the trustee — and the independent offshore trustee refused. The court accepted that she was unable to comply. It also carries a drafting lesson this structure takes seriously: the weakness was giving the beneficiary an unrestricted power to remove and replace the trustee, a power that should be suspended during duress.
Riechers v. Riechers, 679 N.Y.S.2d 233 (N.Y. Sup. Ct. 1998) — a physician established a Cook Islands trust years earlier in response to malpractice exposure. The court declined to set it aside, finding it had been created for the legitimate purpose of protecting family assets, and acknowledged it had no jurisdiction over the offshore corpus. Keep the limits straight: this was a divorce case, and the court still made an equitable-distribution award against the husband personally. A trust shields you from creditors. A divorce court with personal jurisdiction over a spouse can still order an offsetting award.
One honest note on Grant and Anderson: the creditor in both was the federal government — an unusually relentless, well-resourced adversary that a typical private plaintiff rarely replicates. That is part of why most claims against a well-built offshore structure never get that far.
Maggio v. Zeitz, 333 U.S. 56 (1948) sits underneath all of this: civil contempt requires a present ability to comply. Everything in the control analysis is downstream of that rule.
Common Objections to the Bridge Trust®, Answered
Most criticism of this structure applies real legal principles to a structure built differently than the criticism describes. Below are the seven objections I hear most, with the parts I agree with stated plainly before the parts I don’t.
Skepticism is the correct posture when you are putting seven or eight figures behind a legal structure. I would rather earn a client who showed up skeptical.
“If you’re the trustee, a judge can just order you to hand over the assets.”
I agree with the principle, without qualification. If you are within a U.S. court’s jurisdiction and you hold legal authority over property, that court may order you to exercise it, and refusing can lead to contempt. Any planner who waves that off is asking you to eat the consequences.
Where I disagree is the application, because the objection assumes you still hold that authority on the day the order issues. In a properly built Bridge Trust®, you do not. The roles are divided from inception — grantor, domestic trustee, independent Protector, Special Successor Trustee — and on an Event of Duress, certain retained grantor powers are suspended and the Protector receives authority to appoint or replace trustees.
The client’s investment role is advisory only, and the instrument says so expressly: it cannot be construed as control and cannot be used to argue dominion or decision-making authority. Distribution discretion is vested solely in the trustee. You cannot compel a distribution to yourself. That is not a limitation I apologize for. That is the thing that works.
The separation is not ceremony. It is the product.
“The offshore trustee could just refuse to serve when you actually need it.”
This one gets repeated a lot, and it describes a different arrangement than this one.
The Special Successor Trustee signs the trust agreement as a party, alongside the settlors, trustees, and Protector. It is not merely named in a document it has never seen. KYC, compliance, due diligence, onboarding, and ongoing relationship management are all completed before any litigation exists. Fees fund an existing fiduciary and contractual engagement.
Refusal without legitimate fiduciary grounds would carry contractual, fiduciary, reputational, and regulatory consequences for a licensed trust company. And if a named successor genuinely cannot serve, the instrument gives the Protector authority to appoint another — the drafted answer to exactly this objection.
Limited fiduciary discretion around AML, sanctions, and local law exists in every trust everywhere. That universal principle is not the same thing as deciding for the first time, mid-litigation, whether to participate.
Across nearly 30 years the acceptance mechanism has operated every time it has been triggered. That is platform history, not a promise about your case.
“Judges hold people in contempt for this. Look at Anderson.”
They do, and Anderson is the right case to look at — as long as you read all of it. See the case-law section above. The assets stayed offshore because the foreign trustee refused. The contempt attached to retained control, not to the fact of being offshore.
That is an argument for doing the control analysis carefully. It is not an argument for skipping the structure.
“If it works, why isn’t there a body of case law where it won?”
Because the structure does its work at the leverage and settlement stage, before anything reaches a published opinion. A creditor facing non-recognition of the judgment, a criminal-level burden of proof, a short limitation window, a substantial bond, and fee-shifting usually revalues the claim rather than litigating it abroad. Settlements are private. Cases that never get filed produce no opinions.
There is also a consistency point worth making. The adverse matters critics rely on are largely unpublished trial-court orders involving reactive planning or retained domestic control. If unpublished trial-court orders count as evidence when they cut against the structure, they cannot become irrelevant when the facts run the other way.
“A fully foreign trust is stronger. The hybrid is a compromise.”
The Bridge Trust® is a foreign trust in legal character from inception. That is the entire premise. What is domestic is the tax classification and the administration while conditions are calm.
The firm has decades of experience building, administering, and defending fully foreign trusts, and for some clients that remains the right answer — typically those already facing sustained, well-resourced adversaries. For most high-liability professionals planning ahead of a threat, carrying offshore administration cost and annual 3520 / 3520-A / FBAR filings for a risk that may never materialize is a real cost with no corresponding gain in the years before anything happens.
That is a fit question, not a strength question, and it is one of the things a legal consultation is for.
“Moving assets after I get sued is a fraudulent transfer.”
Correct — and that is precisely why the offshore foundation exists from day one rather than being assembled at the moment of crisis.
There is no transfer at the trigger. No new trust is created, no assets are conveyed, and no decanting occurs. What changes is administration and tax posture. The trust that existed before the claim is the same trust that exists after it.
The fraudulent-transfer risk in this area attaches to funding, and funding happens years earlier, before a claim is foreseeable. That is what “structure before stress” actually means.
“I already have LLCs and an umbrella policy.”
Both are useful. Neither is a substitute.
Insurance pays within policy limits, subject to exclusions, and carriers litigate coverage. An LLC addresses inside liability — a claim arising from the asset — but does far less for outside liability, a claim against you personally that reaches through to your ownership interest. And a single-member LLC is the weakest position on the charging-order axis.
Layering matters here, and so does the entity you use at the holding level. That analysis is specific to your assets, your state, and your exposure.
Does the Bridge Trust® Change What I Owe the IRS?
No. The structure is tax-neutral. Income is reported on your own return under the grantor-trust rules, and the trust is fully transparent to the IRS. It does not reduce, defer, or hide a single dollar of tax.
The compliance touchpoints:
• IRC §7701(a)(30)(E) — domestic versus foreign trust classification
• Treas. Reg. §301.7701-7 — the Court Test and Control Test
• IRC §§671–677 — grantor-trust rules; income taxed to the grantor
• Treas. Reg. §§1.671-1 and 1.671-4 — grantor-trust reporting
• Forms 3520 and 3520-A — if and when the trust transitions offshore
• FBAR (FinCEN Form 114) and FATCA reporting where applicable
There is no secrecy here — only lawful jurisdictional separation.
One consequence worth flagging for advisors: because the trust is drafted to establish and maintain grantor-trust status, appreciated assets receive a step-up in basis at death under IRC §1014. The step-up rides on that grantor status and on compliant drafting, not on jurisdiction. A trust that removes assets from your estate at funding forfeits it.
When Do People Start Looking for a Bridge Trust®?
Almost never at random. People start after something makes the risk concrete — a claim, a personal guarantee, a liquidity event, or a growing portfolio they suddenly realize is exposed.
The common triggers:
• building a large real-estate portfolio
• signing personal guarantees on business debt
• receiving a malpractice claim or legal threat
• selling a business and holding new liquid wealth
• realizing insurance may not fully cover the exposure
Each is usually the first time someone asks: “If something serious happens, are my assets actually protected?”
That question is what this structure was built to answer. The difficulty is that by the time most people ask it, the calendar has already closed some of their options.
Who Is the Bridge Trust® For — and Who Is It Not For?
It fits high-liability professionals and investors who are planning ahead of a threat. It does not fit anyone already in litigation, anyone attempting to defeat an existing creditor, or anyone looking for a tax result.
Well suited for: physicians and surgeons in high-litigation specialties, real-estate investors, entrepreneurs carrying personal guarantees, and families holding significant assets in their personal names.
Not appropriate for: anyone already in litigation or facing a foreseeable claim, fraudulent transfers, tax-avoidance schemes, or last-minute planning.
Timing is not a detail here. It is the variable that determines whether the structure protects anything at all.
What Is the Dynasty Bridge Trust®?
It extends the same protection architecture past your lifetime. The Bridge Trust® defends assets from creditor threats while you are alive; the Dynasty Bridge Trust® adds a dynasty layer so those assets are not re-exposed to your heirs’ creditors, divorces, and transfer tax when they inherit.
The Bridge Trust® solves the problem most successful professionals face: protecting what you have built from a serious creditor threat during your lifetime. For families with roughly $12 million or more in exposed assets, there is a second problem it was not designed to solve alone — what happens to those protected assets after you are gone.
A standard estate plan transfers wealth. It does not defend it. The moment children inherit outright, under a will or a revocable living trust, those assets re-expose to everything in their lives: their creditors, their divorcing spouses, and transfer tax that can take up to 40% at every generational handoff.
The Dynasty Bridge Trust® combines the Bridge Trust® architecture — offshore jurisdiction, independent Trust Protector, Event-of-Duress mechanics — with downstream dynasty protection carried forward through sub-trusts under the same governing agreement. Your children benefit from the assets without owning them outright, so a creditor suing your son cannot reach what is in trust and a divorcing spouse cannot claim it as marital property. GST exemption is allocated at funding, sheltering future appreciation.
And because the structure maintains grantor-trust status during your lifetime, appreciated assets still receive the §1014 step-up at death — a benefit traditional dynasty trusts forfeit by removing assets from the estate at funding. The Dynasty Bridge Trust® captures the step-up first, then activates the dynasty layer.
Most advisors handle these as two conversations, two attorneys, and two structures. This closes both gaps in one integrated system.
Bridge Trust® FAQs
Is the Bridge Trust® the same as a regular offshore trust?
No. It is offshore in legal foundation but domestic in tax classification and administration until a transition occurs. That means no offshore filing burden and no loss of practical access while conditions are calm.
Does the Bridge Trust® avoid U.S. taxes?
No. All income remains fully reportable under U.S. tax law. The structure is tax-neutral by design and does not reduce, defer, or hide tax.
Can a U.S. court force repatriation of the assets?
Courts can order a person within their jurisdiction to act. Whether that order can be satisfied depends on whether the person still holds the relevant authority. Where authority rests with an independent trustee and the settlor’s powers are suspended under duress, enforcement becomes substantially harder — which is the entire point of separating the roles.
Is the Bridge Trust® a Domestic Asset Protection Trust?
No. It does not rely on any state DAPT statute, which is why the line of cases defeating domestic asset-protection trusts does not reach it the same way.
Who decides when the trust goes offshore?
An independent Trust Protector, exercising fiduciary judgment. There is no automated trigger, and declaring an Event of Duress does not by itself change situs, law, or trustee.
Is the Bridge Trust® one trust or two?
One. It holds an offshore legal foundation and a U.S. domestic tax classification simultaneously, the way a person can hold two passports. At transition, no new trust is created and no assets are conveyed.
Does the Bridge Trust® protect real estate?
Not by moving it. Land is governed by the law where it sits, as Huckaby illustrates. Real estate is protected by structuring and protecting the equity through entity layering, with the trust owning the holding entity.
How long has the Bridge Trust® been in use?
Roughly 30 years. With thousands of clients and billions of assets protected. That is platform history, not a guarantee about any individual outcome.
⸻
📞 For a confidential legal consultation with an Asset Protection Attorney, contact Bradley Legal Corp. at (888) 773-9399 or visit btblegal.com.
Structure before Stress.
By: Brian T. Bradley, Esq.
Asset Protection Attorney | Bradley Legal Corp.