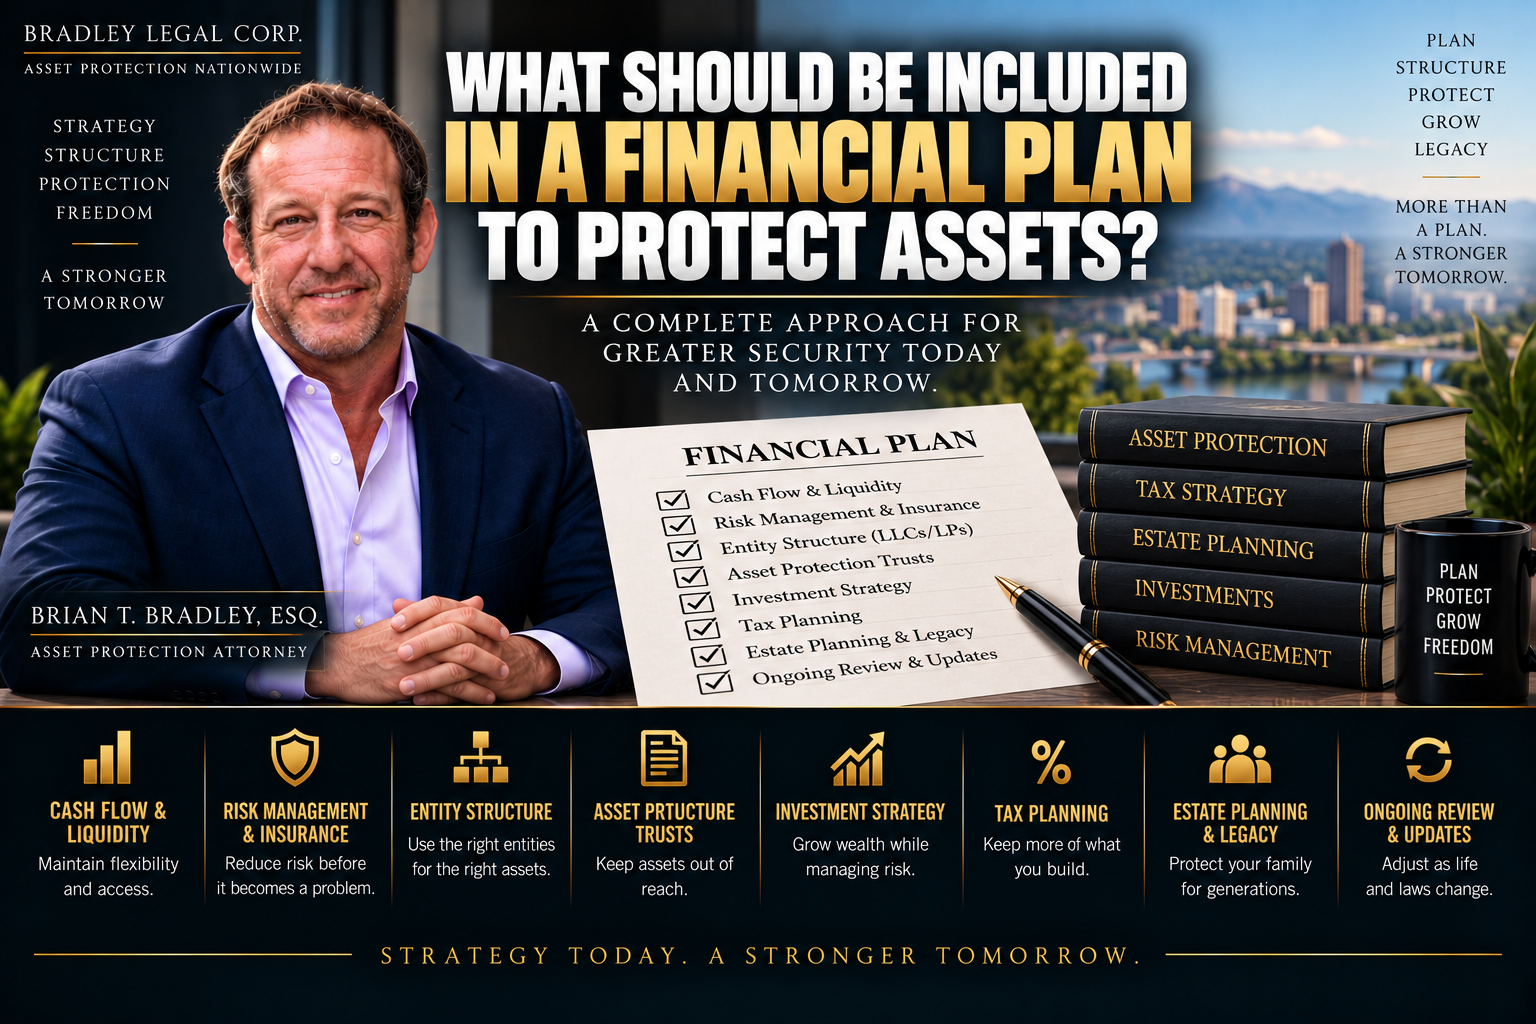
A financial plan that protects assets contains five things: adequate insurance, an inventory of what is already exempt by statute, entity separation for anything that generates liability, a holding structure that stops a personal judgment from reaching your ownership interests, and — for meaningful exposure — a trust layer that separates ownership from control. Insurance is the first line and the one most plans stop at. It is also the one that runs out first.
If You Came Here From a Personal Finance Quiz
The question usually reads:
What should be included in a financial plan to protect assets? a. how much money you will make b. how much money you will have in savings c. how much money you will invest d. how much insurance you will carry
The answer is D.
Insurance is the component of a financial plan specifically directed at protecting assets. The other three are about accumulating them. Your instructor is looking for D.
And for most households, D is genuinely the right answer. Adequate coverage handles the overwhelming majority of financial risk a typical family faces. But insurance does not protect assets. Insurance is not asset protection.
It stops being the complete answer at the point where a judgment can exceed your policy limits — which is the situation the rest of this page is written for. If that is you, keep reading. If it is not, you have your answer.
Key Points
- Insurance pays the claim. Structure protects what is left when the claim exceeds the policy.
- A meaningful share of most balance sheets is already exempt by statute. Find that before buying protection.
- A revocable living trust provides no creditor protection during your lifetime.
- Entity separation handles claims arising from assets. It does nothing about a personal judgment.
- Timing is the only element that cannot be added later.
- Investment allocation is your advisor’s domain, not your attorney’s. Anyone blurring that line should be asked why.
What a Financial Plan Actually Is
A financial plan is a structured approach to building and keeping wealth. Most plans cover accumulation well — retirement savings, education funding, an emergency reserve, debt paydown.
Where they consistently thin out is the protection side. Not because advisors ignore it, but because the tools that actually protect assets are legal structures rather than financial products, and they sit outside what a financial plan normally addresses.
The result is a common pattern: someone with a well-built portfolio, a revocable living trust, an LLC or two, and adequate insurance — who believes they have addressed protection and has not.
Component One: Insurance — and What It Actually Does
Insurance is risk transfer. It pays a claim after a loss, within policy limits. Everything above the limit becomes a personal judgment against you. That is the boundary, and it is where structure begins.
This is the first line of defense and it should be the first thing you fix, because it is the cheapest protection you will ever buy relative to what it covers.
The coverage that matters:
Liability and umbrella. An umbrella policy sits above your auto and homeowners coverage and is inexpensive relative to what it does.
Professional liability, where your work creates exposure. Check your limits against your field’s actual verdict range, whether defense costs erode the limit, whether the policy is claims-made or occurrence, and whether you have tail coverage.
Disability, which protects your ability to keep earning — a different risk than the ones above, and the one most people underinsure.
Property and casualty on everything you own that can produce a claim.
Here is the limit worth understanding. A $2 million policy against a $5 million verdict leaves $3 million as a personal judgment reaching your home equity, brokerage accounts, and investment property.
Insurance does not fail. It runs out. Structure is what handles the part above the limit.
Component Two: Know What Is Already Protected
A meaningful share of most balance sheets is already exempt from creditors by statute. Qualified retirement plans, homestead equity, and certain insurance and annuity values. Knowing that number changes what actually needs a structure — and it is the step almost every plan skips.
Qualified retirement plans. ERISA-governed plans carry strong anti-alienation protection, subject to exceptions such as qualified domestic relations orders and federal tax claims. For a mid-career professional, this is frequently the largest protected block on the balance sheet.
IRAs and non-ERISA plans vary by state and are often narrower.
Homestead varies enormously. Florida and Texas offer effectively unlimited equity protection subject to acreage limits. New York’s exemption is modest. California’s is indexed and real but limited.
Certain life insurance and annuity values are exempt under state law.
Why this comes before anything structural: if $800,000 of a $2 million net worth sits in a qualified plan and another $500,000 is protected homestead equity, the genuinely exposed number is $700,000 — and the right structure for $700,000 is not the right structure for $2 million.
An advisor or attorney who recommends a structure before running this analysis has not done the work.
Component Three: Estate Planning — What It Does and Does Not Do
A revocable living trust avoids probate and handles incapacity. It provides no creditor protection during your lifetime, because you can revoke it — and a court is not required to pretend that power does not exist.
This is the most common misunderstanding in the entire field, and it is worth being blunt about.
What a revocable living trust does: avoids probate, keeps distribution private, provides for management if you become incapacitated, and serves as the endpoint through which assets ultimately pass to beneficiaries.
What it does not do: protect anything from your creditors while you are alive.
Every asset inside a revocable trust is as exposed as if it were titled in your own name, because from a creditor’s standpoint it effectively is.
A complete estate plan also includes a durable power of attorney, an advance healthcare directive, and current beneficiary designations — which override your will on retirement accounts and insurance regardless of what the will says.
Estate planning and asset protection are different disciplines. Both matter. Neither substitutes for the other, and the clients most exposed are often the ones who completed one and believe they have done both.
Component Four: Entity Separation
Assets that can generate a claim belong in separate entities, each formed where the asset sits. This handles inside liability — a claim arising from a specific asset. It does nothing about a personal judgment coming the other direction.
Rental real estate, operating businesses, boats, aircraft — anything that can produce a claim by existing — belongs in its own entity so a claim arising from one does not reach the others.
Form each entity where the asset sits. Real property is governed by the law of the place it occupies. An out-of-state LLC owning local rentals is typically doing business there and must register, and the claim will be litigated there under that state’s law regardless of where you filed.
And know the limit. If a creditor obtains a judgment against you personally — a car accident, a professional claim, a guaranteed debt — they reach your ownership interests in every entity you hold. That is outside liability, and entity separation does not address it.
Single-member LLCs are the weakest position here. Florida codified foreclosure against them at Fla. Stat. §605.0503(4) after Olmstead v. FTC, 44 So.3d 76 (Fla. 2010). California authorizes foreclosure at Corp. Code §17705.03(b)(3), inside what its own statute calls the exclusive remedy.
Component Five: The Holding and Trust Layers
A management entity above your operating entities addresses outside liability. A trust above that separates ownership from control. Which you need depends on your exposure, not your net worth.
The management layer. An asset management limited partnership holds the operating entity interests plus safe assets — cash, brokerage accounts, securities, notes, business interests. A creditor’s remedy against your interest is a charging order: the right to receive distributions if and when they are made, with no access to the underlying assets and no management authority.
Under A.R.S. §29-341, the charging order is the exclusive remedy against a limited partner’s interest, and the section contains no foreclosure provision — an omission that reads as deliberate alongside §29-1044(B), which expressly authorizes foreclosure for Arizona general partnerships.
One honest note. Charging-order exclusivity is a rule about how a judgment creditor collects. Courts have carved exceptions — reverse veil piercing, receivership, alter ego, fraudulent transfer — and it does not survive bankruptcy. The domestic layer raises the cost of collection. It is not where the protection ultimately lives.
The trust layer. For meaningful exposure, an irrevocable asset protection trust changes the legal system the fight happens in — a jurisdiction that does not recognize U.S. judgments, applies a beyond-reasonable-doubt standard to fraudulent transfer claims, imposes short limitation periods, and shifts costs against a losing claimant.
And the mechanism that matters most: it removes your own power to act while you are the one a court would be ordering. If you retain the ability to bring assets back, a judge can order you to do exactly that.
A note on jurisdictions. The Cook Islands and Nevis are both first-tier and largely co-equal, with different architecture. Nevis mandates a statutory bond of EC$270,000 under §61 of its International Exempt Trust Ordinance. The Cook Islands has no equivalent mandatory bond — its barriers operate through non-recognition, the criminal burden, limitation periods, and cost.
Where the Investment Side Fits — and Where It Does Not
Asset allocation, diversification, and product selection belong to your financial advisor and your CPA. They are not legal questions, and an attorney making specific investment recommendations is working outside their lane.
Diversification matters. Concentration risk is real. Those are genuine components of a sound financial plan.
They are also not my discipline, and you should be skeptical of any attorney who tells you which asset classes to hold, what percentage to allocate, or which insurance products to buy. Those are questions for a licensed advisor with a fiduciary obligation and your full financial picture.
What I do is different. I build the legal architecture that determines what a creditor can reach when something goes wrong. Your advisor decides what goes in the accounts. I make sure the accounts are held in a way that survives a judgment.
The best outcomes happen when those two roles coordinate and stay in their respective lanes.
The Element That Cannot Be Added Later
Every component above assumes one thing: it exists before a claim is foreseeable.
Under the Uniform Voidable Transactions Act, a court can unwind a transfer made with intent to hinder or delay creditors — and separately unwind a transfer made without reasonably equivalent value while insolvent, with no intent required at all. In bankruptcy, 11 U.S.C. §548(e) reaches ten years for transfers to a self-settled trust.
Foreseeability starts earlier than people expect. Not at service of the complaint. At the incident. At the demand letter.
A structure built after that point is not protection. It is a transfer a creditor will attack, and it typically makes your position in the underlying case worse.
Common Mistakes
Assuming a revocable trust protects assets. It does not, during your lifetime.
Assuming an LLC is enough. It handles claims arising from the asset. It does not stop a personal judgment from reaching your interest in it.
Buying structure before running the exemption analysis. You may be paying to protect assets that are already protected.
Forgetting personal guarantees. A guarantee gives the lender a direct claim against you that no entity structure addresses.
Never funding the structure. An unfunded entity or trust protects nothing. This is the most common failure of all — the documents exist, the deeds and account retitling never happened.
And waiting. Every other mistake on this list is fixable. Timing is not.
FAQs
What should be included in a financial plan to protect assets? On a personal finance exam, the answer is insurance — how much coverage you will carry. In practice, a complete protection plan also includes an inventory of statutory exemptions, entity separation for liability-generating assets, a holding structure, and for meaningful exposure, a trust layer.
Is insurance enough? For most households, yes. It stops being enough at the point where a judgment can exceed your policy limits, because everything above the limit becomes a personal judgment.
Does a revocable living trust protect my assets from creditors? No. Because you can revoke it, a court can order that power exercised. It avoids probate and handles incapacity — both valuable, neither creditor protection.
Does an LLC protect my personal assets? It contains claims arising from the asset the LLC holds. It does not stop a personal judgment from reaching your membership interest, and single-member LLCs are the weakest position in states that authorize foreclosure.
What is already protected without any planning? Typically qualified retirement plans, homestead equity to your state’s limit, and certain insurance and annuity values. That analysis should come before any structure is recommended.
When do I need more than insurance and an LLC? When your exposed assets — what is left after exemptions — are large enough that a judgment above your policy limits would meaningfully change your life. That is an exposure question rather than a net worth threshold.
Should my attorney be recommending investments? No. Asset allocation and product selection belong to a licensed advisor. An attorney recommending specific investments or insurance products is working outside their discipline.
Is it too late if I’ve already been sued? For that claim, largely yes. A transfer now is voidable and typically worsens your position. Forward planning against claims that do not yet exist remains available.
The Bottom Line
The textbook answer to this question is insurance, and the textbook is right for most people.
It stops being right at the point where a single adverse event could take a meaningful share of what you have built. At that point the question is no longer how much coverage to carry. It is what happens to everything above the limit.
That is a legal structuring question, and it has a real answer — one that has to be built before there is anything to build it against.
You don’t rise to the level of your income. You fall to the level of your legal structure.
Structure before stress.
📞 For a confidential legal consultation, contact Bradley Legal Corp. at (888) 773-9399, or complete the intake questionnaire at btblegal.com.
By: Brian T. Bradley, Esq.