
The Trust Held. He Went to Jail Anyway.
The Belize trustee refused to repatriate. The Illinois court never reached the trust. Steve Fanady has been in Cook County Jail since June 2022. Here's why.
The Belize trustee refused to repatriate. The Illinois court never reached the trust. Steve Fanady has been in Cook County Jail since June 2022. Here's why.
Which Asset Protection Structure Do I Actually Need? LLC, limited partnership, or trust — and when each one earns its cost. A layer-by-layer framework based on your exposure, not your net worth.
Does an Offshore Trust Preserve the Step-Up in Basis? Rev. Rul. 2023-2 says completed gifts to a grantor trust get no §1014 step-up. Most offshore trusts are completed gifts. What that costs, and the design question that decides it.
Automatic Migration Provisions Under Treas. Reg. §301.7701-7. A trust that migrates offshore automatically when a creditor sues is foreign from the day it was created. The regulation says so, with an example. What a properly drafted instrument does instead.

A fully foreign trust may offer powerful asset protection—but it also creates guaranteed annual reporting obligations that can produce six-figure penalties even when no additional tax is owed. Before recommending an offshore structure, CPAs, wealth managers, and financial advisors should understand the true cost of Forms 3520 and 3520-A, the importance of an independent offshore trustee, and why many clients are better served by a hybrid Bridge Trust® that defers foreign compliance until it is actually needed. This article provides a practical framework for evaluating both the financial and structural risks before sending a client offshore.

When you create a foreign trust, you step into one of the most unforgiving reporting regimes in the entire Internal Revenue Code. The rules live in IRC § 6048.

The “trustee might refuse” critique of the Bridge Trust® collapses under the statutory framework, contractual reality, and 30 years of operating history.
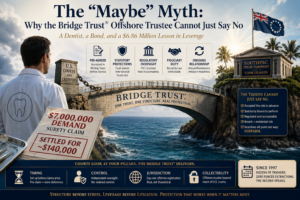
The biggest criticism of the Bridge Trust® is that the offshore trustee can simply “say no” during duress. That critique misunderstands how the structure actually works. This article explains why the Special Successor Trustee’s commitment is made at formation — not at trigger — and why the same “maybe” argument applies equally to fully foreign Cook Islands trusts. Includes real-world case analysis, trustee mechanics, Cook Islands law, and the four pillars courts actually evaluate: timing, control, jurisdiction, and collectibility.
The OBBBA Didn't Fix the GST Portability Gap. The exemption is permanent at $30M for couples. But GST exemption is not portable, and it disappears at the first death. What that costs a $12M couple who waits.

Is the Bridge Trust® Really a Domestic Trust? No. The Bridge Trust® is a foreign trust in legal character from the day it is executed. “Domestic” is its IRC §7701 tax classification, not its legal situs. Two statutory tracks, explained.