New York does not permit self-settled asset protection trusts. Under EPTL §7-3.1(a), a disposition in trust for the use of the creator is void as against the creator’s creditors. New York also permits courts with personal jurisdiction over a debtor to compel turnover of assets located anywhere in the world, and allows creditors to seize LLC membership interests outright. It is among the hardest states in the country in which to protect personal wealth.
Anyone advertising a “New York asset protection trust” built on self-settled domestic law is describing something the statute forbids.
Key Points
- EPTL §7-3.1(a) is explicit — a self-settled trust is void as against the creator’s creditors. Not a grey area.
- Koehler gives New York courts global turnover power over anyone within their personal jurisdiction. This is the enforcement tool most planning ignores.
- LLC interests can be seized outright, not merely charged. Single-member is the most exposed position.
- Out-of-state DAPTs usually fail for New York residents, because courts follow control and domicile rather than the trust document’s chosen law.
- Trustees face personal liability — a separate exposure from the one most people are researching.
- Timing decides everything. New York’s fraudulent transfer look-back runs four years.
- A creditor does not have to prove fraud. Matter of Anthone v. Carlo (4th Dep’t 2026) confirms the settlor’s creditors need not show a fraudulent conveyance to reach a self-settled trust.
What Happened to Dr. Carter
The following is a composite illustration drawn from patterns in practice. It is not an actual client.
Dr. James Carter was a cardiothoracic surgeon in Manhattan with six investment properties across Brooklyn and Queens and a net worth just over $8 million.
Five years before the lawsuits arrived, he did what his estate planning attorney recommended: funded an irrevocable trust with his investment properties and created a single-member LLC for each one.
He believed he was protected. He was not.
When a malpractice claim produced a $4.2 million judgment and a tenant personal-injury suit followed eighteen months later, the creditors’ attorneys examined his structure and found nothing that slowed them down. The irrevocable trust was self-settled — he created it and remained a beneficiary — so under EPTL §7-3.1(a) creditors could reach it. His single-member LLCs were exposed to turnover under CPLR §5225. And because the trust had been funded within the four-year fraudulent-transfer window, creditors argued the transfers were voidable.
His attorney had built an estate plan. What he needed was an asset protection structure.
In New York those are not the same thing, and the gap between them is where exposed wealth disappears.
Why Do Self-Settled Trusts Fail in New York?
Because the statute says so directly. EPTL §7-3.1(a) provides that a disposition in trust for the use of the creator is void as against existing or subsequent creditors. If you create a trust and still benefit from it, your creditors can reach it — regardless of irrevocability, spendthrift language, or drafting sophistication.
New York courts have enforced this consistently for decades.
In Vanderbilt Credit Corp. v. Chase Manhattan Bank, 100 A.D.2d 544 (2d Dep’t 1984), the court confirmed that creditors may reach whatever a trustee has discretion to distribute to the settlor.
⚠️ And the creditor does not have to prove fraud
This is the part that makes New York genuinely different, and it was confirmed five months ago.
In Matter of Anthone v. Carlo, 248 A.D.3d 1779, 258 N.Y.S.3d 378 (4th Dep’t Apr. 24, 2026), the trial court held that a judgment creditor had to establish a fraudulent conveyance before reaching assets held by a self-settled trust. The Fourth Department said that was error.
“[T]he settlor’s creditors need not allege or prove [that a self-settled] trust is a fraudulent conveyance before they are permitted to reach the full amount of the beneficial interest retained by the settlor.”
Understand what that removes. In most states, a creditor attacking a trust carries the voidable-transaction burden: intent, badges of fraud, limitations periods, insolvency. In New York, against a self-settled trust, none of that is required. The statute does the work.
The supporting authority is settled. In State of New York v. Hawes, 169 A.D.2d 919, 920 (3d Dep’t 1991), the court held the statutory language “abundantly clear and unequivocal that self-settled trusts are void as against creditors.” Vanderbilt Credit Corp., 100 A.D.2d at 546, and State of New York v. Coyle, 171 A.D.2d 288, 290 (3d Dep’t 1991), reach the same conclusion.
The facts that made the trust self-settled in Anthone are worth knowing, because they describe a very ordinary instrument. It was funded with assets transferred by the grantor or someone acting under his authority. Its stated purpose was to receive and manage assets for his benefit. The trustee was required to pay him income, and principal on request. And he could revoke it at any time.
The court’s conclusion: the trust “is totally owned by” the grantor, and therefore “available to satisfy” his obligation to the creditor.
And New York is not alone in drawing that line. The Illinois Supreme Court reached the same conclusion in Rush University Medical Center v. Sessions, 2012 IL 112906, 980 N.E.2d 45 (Ill. 2012), where a settlor had created a Cook Islands–governed family trust holding more than $18 million in assets.
The trustees argued the Uniform Fraudulent Transfer Act had displaced the older common law rule. The court rejected it: “[t]he common law rule that a self-settled spendthrift trust is void as to existing and future creditors is not abrogated by the Uniform Fraudulent Transfer Act.” And it explained why the inquiries are separate — “it is not a fraudulent transfer of funds that renders the trust void as to creditors under the common law, but rather it is the spendthrift provision in the self-settled trust.”
Two states, fourteen years apart, same principle. The self-settled rule stands on its own. It does not borrow the creditor’s burden from fraudulent transfer law, and a creditor does not have to satisfy the one to win on the other.
Note also what did not save the Sessions trust. Naming Cook Islands law as the governing law of the instrument did not stop an Illinois court from applying Illinois law to a settlor and assets within its reach. Choice of law in a document is not jurisdiction over the person or the property — which is the same lesson Huckaby delivered in California this year.
One limit worth knowing
The creditor in Anthone won the trust argument and still did not get the house.
Summary judgment was denied, and the denial affirmed, because the grantor’s opposition raised a triable issue on whether the homestead exemption under CPLR 5206(a) applied to the sale of the property. The proceeding itself was brought under CPLR 5236, which governs the sale of real property to satisfy a judgment lien.
New York’s exemptions are real and they are not large. They cover a defined slice of home equity and specified personal property. For anyone with meaningful net worth, they are a speed bump, not a plan — but they are the reason a creditor with a winning legal argument can still walk away from a residence.
Courts look at substance over form. If the settlor still benefits from the trust or retains control over it, the structure fails as creditor protection no matter how it is drafted.
New York’s formulation is also more aggressive than most states’. California’s Probate Code §15304 voids the restraint — the spendthrift clause — as against the settlor’s creditors. New York voids the disposition itself. That is a broader rule, and it forecloses arguments that survive elsewhere.
Do Out-of-State Asset Protection Trusts Work for New Yorkers?
Usually not. Courts follow control and domicile, not the jurisdiction named in the trust document. A New York resident who forms a Nevada or Delaware trust but continues to control assets from New York generally gets New York law applied to the creditor question.
Three cases show the pattern.
In re Portnoy, 201 B.R. 685 (Bankr. S.D.N.Y. 1996) — a bankruptcy court disregarded an offshore trust because the debtor retained effective control over the assets.
Lawrence v. Goldberg (In re Lawrence), 279 F.3d 1294 (11th Cir. 2002) — the settlor retained the sole power to appoint trustees, so the court rejected his impossibility defense and affirmed his incarceration for civil contempt. The related bankruptcy court decision, 227 B.R. 907 (Bankr. S.D. Fla. 1998), held the trust corpus was property of the estate and found the debtor had testified untruthfully.
In re Brooks, 217 B.R. 98 (Bankr. D. Conn. 1998) — again, retained control decided the case rather than the jurisdiction of formation.
The principle is consistent across all three: a trust where the settlor retains meaningful control will fail, regardless of where it was formed.
The same conclusion arrives from the other direction in Toni 1 Trust v. Wacker, 413 P.3d 1199 (Alaska 2018) — published state supreme court authority holding that a DAPT statute cannot stop other states or federal courts from applying their own law.
The Turnover Power That Makes New York Different
Under Koehler v. Bank of Bermuda, a New York court with personal jurisdiction over a judgment debtor may compel turnover of assets held anywhere in the world. Authority attaches to the person, not to where the asset sits. This is the enforcement tool most asset protection planning fails to account for.
Koehler v. Bank of Bermuda, 12 N.Y.3d 533 (2009). The New York Court of Appeals held that CPLR §5225 ties the court’s authority to jurisdiction over the person rather than the physical location of the property.
Practitioners call this the global turnover doctrine, and it changes the analysis entirely.
A New York court can order a debtor to produce assets located in another country — if the debtor has the legal ability to do so.
That last clause is the whole question. For planning purposes, Koehler reframes everything:
Does the person subject to the court’s jurisdiction have the authority to produce the asset?
If yes, the court can compel turnover, and moving assets offshore accomplishes nothing. If the answer is genuinely no — because an independent trustee holds exclusive authority and the debtor cannot compel a distribution — the court is ordering something the debtor cannot perform.
That is why control separation matters more in New York than almost anywhere else. Geography alone does not defeat Koehler. Relinquished authority does.
Why Do LLCs Fail in New York?
Because New York does not limit creditors to charging orders. Courts have allowed creditors to seize LLC membership interests outright, compel turnover, and order sale — and reverse veil piercing remains available. Single-member entities are the most exposed.
In 79 Madison LLC v. Ebrahimzadeh, 203 A.D.3d 589 (1st Dep’t 2022), the court allowed a creditor to seize a debtor’s LLC membership interest directly.
The controlling authority sits above that case, and it is the New York Court of Appeals. In Hotel 71 Mezz Lender LLC v. Falor, 14 N.Y.3d 303, 926 N.E.2d 1202 (2010), the court held that ownership and membership interests in limited liability companies — including out-of-state LLCs, among them Delaware entities — are “clearly assignable and transferable,” and therefore property against which a money judgment may be enforced under CPLR 5201(b).
That forecloses the argument most people rely on. Forming the LLC in Delaware or Wyoming does not change the answer, because New York’s enforcement procedures govern the proceeding and New York law decides what counts as reachable property.
The First Department addressed the charging-order argument head-on in 79 Madison: a defendant contended that a creditor is limited to a charging order even under New York law, and the court held simply that “[t]his argument is unavailing.” It also approved a direct turnover to the creditor rather than delivery to a sheriff, because CPLR 5240 permits a court to modify the use of any enforcement procedure — appropriate there because the interest’s value was uncertain and the debtor had obstructed collection.
One honest nuance. A charging order is still available in New York. Under Sirotkin v. Jordan, LLC, 141 A.D.3d 670 (2d Dep’t 2016), a court has discretion to issue a charging order instead of an order assigning or turning over the membership interest. The problem is not that charging orders are unavailable. It is that they are one option among several, chosen at the court’s discretion rather than guaranteed by statute.
What that looks like in practice: in 245 Park Member LLC v. HNA Group (International) Co., No. 23-842-cv (2d Cir. Apr. 8, 2024), the Second Circuit affirmed an order directing a judgment debtor to turn over its entire 100% membership interest in a Delaware LLC, directly to the creditor, in partial satisfaction of a judgment exceeding $185 million. (That decision is a summary order and non-precedential under Fed. R. App. P. 32.1; the binding authority is Hotel 71 and 79 Madison.)
Veil piercing remains available as a separate theory, and New York courts apply it where an entity is operated without genuine separation from its owner. That is an equitable inquiry into conduct rather than a statutory remedy — which means the discipline of running the entity properly matters as much as the drafting.
For single-member LLCs the exposure is at its worst. A creditor with a judgment against the owner can take the entire membership interest — including management control. There is no innocent co-member for the charging-order rationale to protect.
LLCs isolate operational risk. In New York they do not reliably shield personal wealth from a personal judgment.
What About Long Island, NYC, Westchester, and Upstate?
The statutes are identical statewide — EPTL §7-3.1, CPLR §5225, and the Koehler turnover doctrine apply everywhere in New York. What differs by region is the exposure profile: what you own, what kind of claim is likely, and which court hears it.
New York City and Manhattan. Concentrated professional and financial exposure — physicians in high-litigation specialties, finance professionals with fiduciary and securities exposure, business owners facing New York’s exceptionally active employment plaintiff bar. Co-op and condo ownership adds a wrinkle: a co-op interest is personal property in the form of shares plus a proprietary lease, not real property, which changes how a creditor reaches it.
Long Island — Nassau and Suffolk. The dominant profile is real estate: rental portfolios, small commercial holdings, and construction and development exposure. Premises liability and personal guarantees on recourse debt are the recurring threats. Long Island investors also frequently hold property across the county line or in adjacent states, which raises the situs question below.
Westchester and the Hudson Valley — including White Plains. Professional practices, closely held businesses, and significant residential equity. Proximity to Connecticut and New Jersey means multi-state holdings are common, and each state’s enforcement law governs its own real property.
Upstate. Lower property values but the same statutory framework, and often more concentrated business ownership relative to total net worth.
The one rule that overrides geography: you cannot move dirt. Real property is governed by the law of the place it sits. A New York LLC holding Connecticut property gets Connecticut enforcement law for that asset. Each property belongs in an entity formed where the property is.
What Is New York’s Fraudulent Transfer Look-Back?
Four years in most cases. Under the New York Debtor and Creditor Law §§273–276, modernized in 2020, courts may void transfers made with intent to hinder or delay creditors, or made without reasonably equivalent value while the debtor was insolvent.
Courts analyze “badges of fraud” — insider transfers, retained control, transfers made after litigation risk becomes apparent.
Constructive fraud requires no bad intent at all. A transfer without reasonably equivalent value that leaves you insolvent is voidable regardless of good faith.
And in bankruptcy the reach is longer: 11 U.S.C. §548(e) gives a trustee ten years against a transfer to a self-settled trust.
Planning implemented after a legal threat emerges is highly vulnerable. Planning implemented before one exists is not.
What Actually Works in New York?
A layered structure addressing timing, control, and jurisdiction simultaneously — because New York’s Koehler turnover power means offshore geography alone accomplishes nothing if the debtor retains the ability to produce the asset.
Layer one — state-matched LLCs
Each property or operating asset in a separate LLC, formed where the asset sits. New York property in a New York LLC; Connecticut property in a Connecticut LLC. This isolates operational liability and aligns each entity’s governing law with the law that will actually control creditor rights against that asset.
Given New York’s willingness to reach membership interests directly, drafting matters here — transfer restrictions, pick-your-partner provisions, and genuine economic separation are the difference between a wall and a starting point.
Layer two — the asset management limited partnership
The LLC interests are held by an Arizona limited partnership. Under A.R.S. §29-341, the charging order is the exclusive remedy against a limited partner’s interest, with no foreclosure authorization in the statutory text.
That is precisely the protection New York’s own LLC framework does not provide. A creditor receives only the right to distributions the partnership chooses to make.
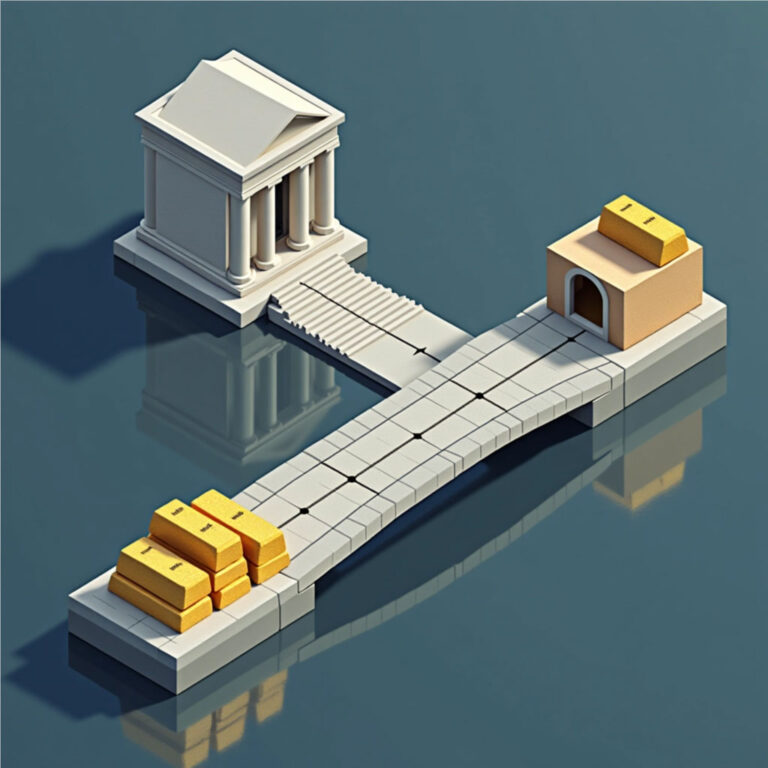
Layer three — the Bridge Trust®
The partnership interest is owned by the Bridge Trust®.
Two independent tax rules do two different jobs, and conflating them is the most common error in commentary on this structure. Because the instrument satisfies the court test and control test of Treas. Reg. §301.7701-7 — the two-part test under IRC §7701(a)(30)(E) — the IRS classifies it as domestic. Separately, it is drafted to maintain grantor-trust status under IRC §§671–677, so income is reported on the settlor’s own return. One rule determines domestic-versus-foreign classification; the other determines who reports the income.
The trust is legally an offshore trust — established under Cook Islands law, also registered in Belize, with a pre-established offshore successor trustee in the Cook Islands or Nevis. For tax purposes only, it is classified as a domestic trust under IRC §7701, so it files as a U.S. grantor trust with no foreign trust reporting and the §1014 step-up preserved. Two separate questions, two separate answers.
If a genuine creditor threat arises, an independent Trust Protector — an attorney exercising professional judgment, not the settlor — may declare an Event of Duress. That declaration is the trigger; nothing fires automatically on the filing of a complaint. Once declared, the instrument operates: standing consents are revoked, the grantor’s powers to appoint or remove the Protector and successor trustee are suspended, and distributions are suspended.
This is not a transfer of assets. Ownership remains with the trust before and after. What changes is administration.
Those jurisdictions do not recognize U.S. judgments, apply a beyond-a-reasonable-doubt standard to fraudulent-transfer claims, impose short limitation periods, and shift costs against a losing claimant. A licensed offshore trustee that honored a foreign order lacking local jurisdiction would face personal liability and loss of license.
And this is where the Koehler answer lives. The global turnover doctrine asks whether the person before the court has the ability to produce the asset. Once duress is declared and the settlor’s relevant powers are suspended, the honest answer is no — and that is a structural fact, not an assertion. Anderson is the cautionary case in the other direction: the settlors kept protector powers over their own trust, so the court found their inability self-created and jailed them for contempt, even though the Cook Islands trustee refused and the assets never came back.
No structure guarantees an outcome. What a properly built and properly timed structure changes is what a creditor can reach and what it costs to try.
What This Would Have Meant for Dr. Carter
His properties would sit in separate state-matched LLCs. The LLC interests would be owned by the limited partnership. The partnership interest would be owned by the Bridge Trust®.
A creditor might still obtain a judgment. Collecting on it would look entirely different.
And in litigation, collectability determines settlement economics.
New York Asset Protection FAQs
Does New York allow asset protection trusts? Not self-settled ones. EPTL §7-3.1(a) makes a disposition in trust for the creator’s use void as against the creator’s creditors. Third-party trusts — one you create for someone else — are enforceable.
Can a New York resident use a Nevada or Delaware asset protection trust? Usually not effectively. Courts follow control and domicile rather than the trust’s chosen law, as Portnoy, Lawrence, and Brooks each illustrate.
What is the Koehler global turnover doctrine? Under Koehler v. Bank of Bermuda, 12 N.Y.3d 533 (2009), a New York court with personal jurisdiction over a debtor may compel turnover of assets located anywhere in the world, provided the debtor has the ability to produce them.
Do LLCs protect assets in New York? They isolate operational liability. They do not reliably protect personal wealth — New York courts have allowed creditors to seize membership interests directly, and single-member LLCs are the most exposed.
Does a creditor have to prove fraud to reach my trust? Not if the trust is self-settled. In Matter of Anthone v. Carlo (4th Dep’t 2026), the court held that a settlor’s creditors need not allege or prove a fraudulent conveyance before reaching the full beneficial interest the settlor retained. EPTL §7-3.1(a) does the work on its own.
How far back can a New York creditor reach? Generally four years under Debtor and Creditor Law §§273–276. In bankruptcy, §548(e) reaches ten years for transfers to a self-settled trust.
Is a Medicaid asset protection trust the same thing? No. A Medicaid asset protection trust is an elder-law instrument designed around Medicaid eligibility and its five-year look-back. It serves a different purpose than creditor and lawsuit protection, and the two should not be confused.
Does this work differently in Long Island or NYC than upstate? The statutes are identical statewide. What differs is exposure profile — real estate concentration on Long Island, professional and financial exposure in the city, multi-state holdings in Westchester.
Is it too late if I’ve already been sued? For that claim, largely yes. A transfer now is voidable and can worsen your position. Forward planning against claims that do not yet exist remains available.
The Bottom Line
New York remains one of the most difficult jurisdictions in the country for protecting personal wealth.
Self-settled trusts fail under EPTL §7-3.1. Out-of-state DAPTs lose force when the settlor stays in New York. LLCs rarely protect personal wealth from personal judgments. And Koehler gives New York courts a reach most planning never accounts for.
Effective protection requires a structure built before any claim exists, where ownership, control, and jurisdiction are deliberately separated — and where the honest answer to the Koehler question is that the person before the court cannot produce the asset.
I spent the early part of my career on the plaintiff’s side of civil litigation, running exactly the analysis a New York creditor’s attorney runs. The structures that came apart came apart for the same two reasons every time: the debtor still controlled what he claimed to have given away, or he built the thing after the claim was already in view.
Neither is fixable once a lawsuit is filed. Both are entirely avoidable before one.
Structure before stress.
📞 For a confidential legal consultation, contact Bradley Legal Corp. at (888) 773-9399, or complete the intake questionnaire at btblegal.com.
By: Brian T. Bradley, Esq. – National Asset Protection Attorney
Not ready to talk yet?
Take my 2-minute Lawsuit Exposure Test
Answer yes or no. You get an exposure score and see where your risk actually comes from.
Take the Lawsuit Exposure Test