Real estate asset protection has two separate problems and most structures solve only one. Inside liability is a claim arising from a property — a tenant injury, a habitability dispute. One LLC per property contains that. Outside liability is a personal judgment against you, which reaches your ownership interest in every entity you hold. Property-level LLCs do nothing for it. And because real property cannot be moved, the second problem requires a different answer than cash does.
The structure almost every source recommends — property LLCs under a Wyoming holding LLC — addresses inside liability well and outside liability weakly. This page covers why, and what actually sits at that layer.
Key Points
- Inside vs. outside liability is the whole analysis. Different problems, different tools, and conflating them is the most common structural error.
- A revocable living trust provides no creditor protection. It is an estate planning instrument.
- Property held in your personal name is a direct target — and a judgment against you reaches everything else you own.
- A charging order is only as strong as the statute behind it. Arizona’s LP statute forecloses arguments Wyoming’s LLC statute leaves open.
- You cannot move dirt — which is why the structure has to create an option on the equity rather than relocate the asset.
- Timing is the threshold. Everything here assumes the structure exists before a claim is foreseeable.
What Happened to the Investor With Nine Properties
The following is a composite illustration drawn from patterns in practice. It is not an actual client.
She owned nine rental properties across California — a duplex in Fresno, three single-family rentals outside Sacramento, two small commercial units in the Central Valley, and a cluster near Stockton bought during the last downturn.
Two properties sat inside LLCs she had formed years earlier. Three were still in her personal name. The remaining four had been transferred into her revocable living trust alongside her primary residence and a brokerage account holding roughly $400,000.
She had entities. She had a trust. She had worked with professionals at every stage.
What she did not have was asset protection.
When a tenant at one of her personally held properties filed a serious injury lawsuit, the plaintiff’s attorney had a direct line to everything. The property where the injury occurred had no entity around it, so the judgment attached to her personally — which meant it reached the other properties, the brokerage account, and the assets inside the revocable trust. The LLC-held properties were examined for alter-ego liability. The trust provided no barrier, because a revocable trust never does.
That is not a California story. The same gaps exist for the New York investor with a Manhattan brownstone and four Queens rentals in his name, the Texas investor with a strip center and a brokerage account titled personally, and the Florida investor who believes homestead protection extends to his rental portfolio.
The asset class creates the vulnerability. Geography only changes the rules at the edges.
⸻
Inside Liability vs. Outside Liability
Inside liability is a claim arising from a property — a tenant injury, an environmental claim, a habitability dispute. Outside liability is a personal judgment against you from any source. They require different structures, and a plan that solves one does not touch the other.
This distinction organizes everything else on this page, and it is the thing most real estate asset protection content never names.
Inside liability runs from the property outward. A tenant falls on a defective stair. The claim belongs to whoever owns that property. If the property sits in its own properly maintained LLC, the claim stays inside that entity and does not automatically reach the rest of your portfolio.
That protection is real. It is also the only thing property-level LLCs do.
Outside liability runs from you inward. A car accident. A guaranteed business debt. A malpractice claim in your professional practice. A divorce. The judgment attaches to you personally, and then it reaches your membership interests in every entity you own.
Here is why the distinction decides so much. Someone with eight properties in eight LLCs has solved inside liability completely. They have done nothing about outside liability, because they still personally own eight membership interests, each of which a personal creditor can pursue.
An offshore trust does not fix bad property-level segregation. Property LLCs do not fix outside liability. You need both layers, and they are not substitutes.
⸻
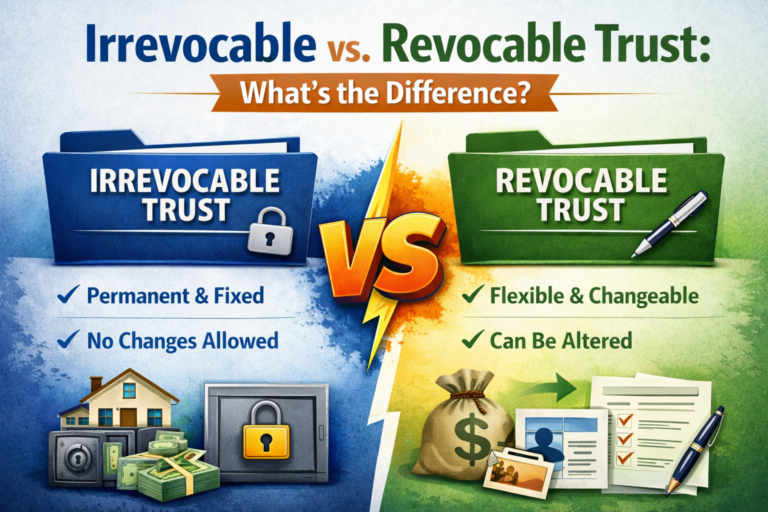
The Revocable Living Trust Is Not Asset Protection
Because you can revoke it. A court can order that power exercised to make the assets available to satisfy a judgment. Every asset inside a revocable trust is as exposed as if it were titled in your personal name, because from a creditor’s standpoint it effectively is.
This is the most persistent misconception among real estate investors, and it is worth stating flatly.
A revocable trust coordinates distribution at death and avoids probate. Both are legitimate and valuable. Neither is creditor protection.
The revocable trust is the estate planning foundation, not the asset protection structure.
⸻
Properties in Your Personal Name: The Exposure Radius
Every property held in your personal name is a direct target — and the problem is not contained to that property.
A judgment creditor obtains a lien against you personally, and that lien attaches to every piece of real property you hold individually in the state where the judgment is docketed, often reaching across state lines through domestication.
A claim arising from one personally held property does not stay with that property. The judgment runs against the person, and the person owns everything else. LLC-held properties, trust assets, and brokerage accounts all become collection targets because the liability attaches to the same individual.
Partial structuring creates false confidence. It is frequently worse than no structure, because the owner believes the problem is solved.
⸻
Should Each Property Be in Its Own LLC?
Usually yes, once the equity is meaningful — but that decision is about inside liability only, and the threshold is equity rather than property count. Grouping several low-equity properties can be defensible. Grouping high-equity properties in one entity puts them all in the same liability bucket.
The logic is straightforward. If Property A and Property B sit in the same LLC and a tenant at A wins a large judgment against that entity, B is an asset of the defendant.
Separate entities cost money — formation, registered agent, annual fees, separate bank accounts, separate bookkeeping. Those costs scale with the portfolio, and for genuinely low-equity properties the calculus is real.
Two things the standard advice usually omits.
Form each entity where the property sits. Real property is governed by the law of the place it occupies. An out-of-state LLC owning local rentals is typically doing business in that state and must register as a foreign entity, pay local fees, and comply locally — and the property-level claim will be litigated there under that state’s law regardless.
And separate LLCs do nothing about outside liability. Eight entities you personally own are eight membership interests a personal creditor can pursue. That is the layer above.
Does a Wyoming LLC Protect Property in Another State?
Not the property, and this is the most common error in real estate asset protection content. Wyoming’s charging-order statute protects your ownership interest from your personal creditors. It does nothing about a claim arising at a property in another state, and it does not displace that state’s law over its own real estate.
The pitch is that forming in Wyoming imports Wyoming’s protections. It does not.
Where the property sits controls the property. A Wyoming LLC owning a California apartment building faces California registration requirements, California franchise tax, California landlord law, and — when a tenant is injured on a defective stair — a California premises liability suit governed by California law.
United States v. Huckaby, No. 2:23-cv-00587-DAD-JDP (E.D. Cal. Mar. 2, 2026) applied exactly this principle. Under Restatement (Second) of Conflict of Laws §280, creditor rights against real property are determined by the law of the situs of the land, not by the law of the state where the holding entity was formed. A self-settled Nevada trust could not shield California real property.
You cannot move dirt.
What Wyoming’s statute does protect is the ownership interest — and that is genuinely useful. It is just a different question from the one most people are asking when they form the entity.
If Your Property Is in Oregon or Washington
Most writing on this subject assumes California, and the two states to its north do not follow California’s rules.
Oregon. The homestead exemption is $158,300 of equity for a single judgment debtor, and $316,700 where two or more members of a household are judgment debtors, under ORS 18.395. The statute itself reads $150,000 and $300,000; the State Court Administrator indexes those figures to the Consumer Price Index each July 1. Oregon does not authorize self-settled asset protection trusts — under ORS 130.315 a creditor of a settlor who is also a beneficiary reaches the maximum that could be distributed for the settlor’s benefit.
Washington. The homestead exemption is the greater of $125,000 or the county median sale price of a single-family home in the preceding calendar year, under RCW 6.13.030. There is no ceiling and no inflation index, so the number swings enormously by county — for 2025 the King County median ran $940,000 and the Ferry County median ran $199,500. Where the property sits decides what is protected.
Washington is also the harshest of the three states on self-settled trusts. Under RCW 19.36.020, a transfer made in trust for the use of the person making it is void as against that person’s existing or subsequent creditors. Not merely reachable. Void.
I am licensed in all three. There is more detail on each at my Oregon asset protection and Washington asset protection pages.
The Holding Layer Everyone Recommends, and Why It Is the Weak Link
The standard advice is property LLCs under a Wyoming holding LLC. That handles inside liability and adds a charging-order layer, but a single-member LLC is the weakest position on the charging-order axis — and Arizona’s limited partnership statute forecloses arguments the LLC route leaves open.
Search this topic and you will find the same structure from nearly every source: state-level property LLCs, owned by a Wyoming holding LLC, because Wyoming has strong charging-order protection.
That structure is not wrong. It is incomplete at the top.
Three problems with the Wyoming holding LLC as the outside-liability layer.
It is usually single-member. The charging-order rationale exists to protect innocent co-members from a creditor forcing into the business. With one member, there is no innocent partner — and courts have said so. In Florida, Olmstead v. FTC, 44 So.3d 76 (Fla. 2010) held a creditor could reach the entire membership interest of a single-member LLC, and the legislature codified foreclosure at Fla. Stat. §605.0503(4). Wyoming’s own statute is strong, but the enforcement question is decided in the forum where you are sued.
Charging-order exclusivity varies more than the marketing suggests. California’s Corp. Code §17705.03 calls the charging order the exclusive remedy — and then authorizes foreclosure of the lien and sale of the interest at subsection (b)(3), plus receivership at (b)(1). Oregon’s ORS 63.259 contains no express exclusivity language at all.
And a holding LLC is still an LLC. It carries whatever the forum state’s LLC enforcement law provides.
The alternative is a limited partnership. Under A.R.S. §29-341, a charging order is the exclusive remedy against a limited partner’s interest, stated in the statutory text with no foreclosure authorization. That is a narrower remedy than most LLC statutes provide, and it is why the holding layer in a properly built structure is an Arizona LP rather than a Wyoming LLC.
You serve as general partner and retain management authority. The economic interest sits at the protected layer.
What About a Series LLC or a Land Trust?
A Series LLC saves filing fees and creates internal liability walls, but its treatment across state lines is unsettled. A land trust provides privacy and no liability protection at all. Neither addresses outside liability.
Series LLC. One master entity with multiple series, each holding a property, liability theoretically separated between them. The appeal is cost and administrative simplicity at scale.
The problem is multi-state. Whether the state where the property sits — and where the lawsuit will be filed — recognizes and enforces the series separation is not settled everywhere, and litigation has arisen over questions as basic as whether the series or the master entity is the proper defendant. For a single-state portfolio it may work. Across three states it introduces an unresolved question at exactly the moment you need certainty.
Land trust. It changes whose name appears in the county recorder’s database. It provides no liability protection. The common structure — land trust holds title, LLC is the beneficiary — gets privacy from the trust and liability protection from the LLC, but the LLC is doing all the protective work.
And privacy is not protection. Which brings up the point most content in this space gets backwards.
Privacy Is Not Secrecy, and Neither Is Protection
No legitimate structure relies on a creditor failing to find your assets. Courts discover everything through the debtor’s examination process. A structure that depends on concealment fails the moment someone with a judgment starts asking questions under oath.
This is worth stating plainly because so much real estate asset protection marketing is built on anonymity.
Offshore accounts in your own name, international business companies, nominee filings — these appear to remove a court’s reach. They do not. As long as you remain the primary controller of the entity, the account, or the arrangement, a judge can order you to produce the assets yourself.
The debtor’s examination is a sworn deposition where you answer questions about everything you own or control. Anonymity is irrelevant there. You are being asked directly.
Protection that works does not hide anything. It changes who has the legal power to act.
Legal Authority vs. Practical Authority
The concept that explains real estate asset protection better than any other. Legal authority is what a statute permits a judge to do. Practical authority is what a judge can actually accomplish. The gap between them is the entire problem — and closing it is the entire solution.
This framework comes from Doug Lodmell, and it is the clearest explanation in the field.
Legal authority consists of statutes and case law. Under Arizona’s LP statute, the exclusive remedy against a limited partnership interest is a charging order. In theory, a judge — even in California — may not order anything else.
So on legal authority alone, the partnership and LLC structure does protect U.S. real estate.
Practical authority is what a judge can actually do. Order a detailed investigation of every asset you hold anywhere. Seize assets. Place liens. Foreclose. Order a sheriff’s sale. Clear title to enable a clean sale. Garnish wages.
The problem arises when a judge without the legal authority exercises the practical authority anyway — disregarding the LP, calling the LLC your alter ego, finding some rationale.
That may leave you with an appealable argument. It also means you are out the assets in the meantime, and appeals are difficult and rarely won.
So the objective is not only to be right on the law. It is to remove or hinder the judge’s practical authority, so that the court is forced back onto legal authority.
For liquid assets, that is straightforward. Once the structure exists, cash can physically sit in an account held by a trust outside U.S. court authority. Your trustee controls it, not a judge.
Real estate is the hard case, because you cannot move it.
So What Does the Structure Actually Do for Real Estate?
It creates an option on the equity that does not otherwise exist. Because the property is legally owned by a partnership held by a trust, the equity can be converted or leveraged and moved beyond a court’s practical reach — later, if it becomes necessary. Without that ownership chain in place first, the option does not exist.
This is the honest answer, and it is more useful than the version most marketing gives.
The real estate stays where it is. Nothing changes that. What changes is that ownership sits legally in the Arizona limited partnership, which is owned by the trust — and that ownership chain leaves two paths open if a judge appears likely to overreach.
Sell the property and convert to liquid assets, which can then be moved beyond the court’s practical authority.
Or leverage the property through genuine third-party borrowing and move the proceeds — leaving less equity behind, with the loan proceeds sitting where a court cannot practically reach them.
Neither option exists if the ownership chain was not built first, and neither is available once a claim is already pending, because at that point every move is a voidable transfer.
Two things this is not. It is not equity stripping through fabricated liens — a lien to an entity you control, with no money advanced, is voidable under the UVTA and supplies evidence of intent. And it is not a promise that a court cannot reach the property. It is a structure that preserves choices while choices still exist.
Does Your Umbrella Policy Cover the LLC?
This is the question I would ask before any of the structure above, and almost nobody asks it.
Most investors carry a personal umbrella policy and assume it sits behind the rentals. It may not. A personal umbrella insures persons — the named insureds on the declarations page. Once you move a property into an LLC, the entity that owns the building and gets named in the lawsuit is not a person, and it may not be an insured on that policy at all.
A California case shows how that plays out. In Hartford Casualty Insurance Co. v. Fireman’s Fund Insurance Co., 220 F. Supp. 3d 1008 (N.D. Cal. 2016), a worker was electrocuted at a Malibu rental in 2009. The wrongful death suit produced a judgment of roughly $8.8 million against Herndon Partners, LLC, and only Herndon held title to the property.
The owner was not uninsured. There was a business liability policy with $2 million primary and $1 million excess. A homeowner’s policy at $300,000 that listed the Malibu property and named the LLC as an additional insured. And a personal umbrella with a $5 million limit.
The umbrella paid nothing. The carrier refused coverage under the excess policy because the LLC “was not a named insured,” and separately cited the policy’s exclusions for business activity, business property, and workers’ compensation. The court describes “the business exclusions that ultimately precluded Herndon from receiving coverage.”
Then the detail that should stay with you. The carrier later refused to indemnify the LLC under the primary homeowner’s policy as well — the one that did list the property and did name the LLC.
So the usual advice, make sure each property is scheduled on the policy, is necessary and not sufficient. Listing the address did not save this claim.
Two questions settle it, and you can answer both tonight from your declarations page. Who is named as an insured — you, or the entity that owns the building? And what do the business activity and business property exclusions say?
If the rentals sit in LLCs and your umbrella still names only you and your spouse, you have the gap. The fix is usually a commercial general liability policy at the entity level, or an endorsement adding the entities as named insureds. Either is far cheaper than finding out during a deposition.
None of this is an argument against the LLC. The LLC did its job here — the judgment landed on the entity, not on the owners personally. What it also did was walk the claim out of a personal policy, because personal policies insure people. That is the coordination problem, and it is why the insurance layer and the entity layer have to be designed by someone looking at both at once.
The Layer Nobody Discusses: Your Lender
Due-on-sale clauses, personal guarantees, and refinancing restrictions can defeat or complicate an entity structure entirely — and almost no asset protection content addresses it. This is where good plans meet the loan documents.
I checked how the major AI research tools answer real estate asset protection questions. Every one recommended entity structuring. Not one mentioned lenders.
That is a significant gap, because the loan documents frequently control what you can actually do.
Due-on-sale clauses. Most residential mortgages contain one, giving the lender the right to accelerate the loan if the property transfers. Transferring a mortgaged property into an LLC is a transfer. Federal law under the Garn-St Germain Act creates exceptions — notably transfers into a revocable inter vivos trust where the borrower remains a beneficiary — but those exceptions are narrower than commonly assumed and do not cleanly cover LLC transfers.
In practice, many lenders do not call the loan. That is a business decision, not a legal protection, and it can change.
Personal guarantees. This is the exposure that defeats entity structuring entirely, and commercial real estate is full of it. If you signed a guarantee, the lender has a direct claim against you personally. The LLC is beside the point — they are not suing the entity, they are suing you.
Every investor with commercial debt should know which loans carry a guarantee, whether it is full or limited, and what the carve-outs trigger. Many do not.
Refinancing entity-held property. Once a property sits in an LLC, the financing options narrow. Residential lenders often will not lend to an entity at all, pushing you toward commercial terms with shorter amortization, higher rates, and — frequently — a personal guarantee that reopens the exposure you just structured around.
The sequencing matters. Refinance first, then transfer, is usually easier than the reverse. That is a conversation to have before the structure is built, not after.
The Full Architecture
Layer one — property LLCs, formed where each property sits. Contains inside liability and aligns each entity’s governing law with the law that will control any claim arising at that property.
Layer two — the Arizona limited partnership. Holds the LLC membership interests. Under A.R.S. §29-341, the charging order is the exclusive remedy against a limited partner’s interest, with no foreclosure authorization in the statutory text. You serve as general partner and retain management control. This is the outside-liability layer, and it is where the Wyoming holding LLC falls short.
Layer three — the Bridge Trust®. Holds the majority limited partnership interest.
Two independent tax rules apply. The instrument satisfies the court test and control test of Treas. Reg. §301.7701-7 under IRC §7701(a)(30)(E), so the IRS classifies it as domestic. Separately, it maintains grantor-trust status under IRC §§671–677, so income is reported on your own return. One rule determines classification, the other determines who reports income.
During normal operations there is no offshore filing burden.
If a genuine creditor threat arises, an independent Trust Protector — an attorney exercising professional judgment, not you — may declare an Event of Duress. Nothing fires automatically on the filing of a complaint. Once declared, the Protector may appoint the pre-committed Special Successor Trustee in the Cook Islands or a co-equal jurisdiction such as Nevis.
A licensed offshore trustee that honored a foreign court order lacking local jurisdiction would face personal liability and loss of license. That is why a U.S. repatriation order directed at the trustee has no practical effect.
And this is where the practical authority analysis lands. For a structure built on removing practical authority to work, it has to remove your own power to act while you are in the risk position. If you retain the ability to bring the assets back, a judge can order you to do exactly that — which is the lesson of FTC v. Affordable Media, where the settlors kept protector powers over their own trust and were jailed for contempt.
Timing Is the Threshold
Every element above assumes the structure exists before a claim is foreseeable.
Fraudulent transfer law evaluates transfers by when they occurred. Under the UVTA, a court can unwind a transfer made with intent to hinder or delay creditors, and separately unwind one made without reasonably equivalent value while insolvent — the second requiring no bad intent at all. In bankruptcy, 11 U.S.C. §548(e) reaches ten years for transfers to a self-settled trust.
Foreseeability starts earlier than people expect. Not at service of the complaint. At the incident. At the demand letter.
A structure built after that point is not protection. It is a transfer a creditor will attack, and it worsens your position in the underlying case.
If the building houses an adult family home or care facility you operate, the operating risk sits under the same roof as the real estate. I cover how to separate them in my guide to adult family home and care home asset protection.
FAQs
Does an LLC protect rental property from lawsuits? It protects against one of the two kinds of claim and not the other. If a tenant is injured at the property, the LLC confines that claim to the property it owns — that is inside liability, and it works. If you cause a car accident and a judgment is entered against you personally, the LLC does not stop a creditor from reaching your membership interest — that is outside liability, and it turns on your state’s charging order statute. Most investors form the entity worried about the second problem and only solve the first.
Can a tenant sue me personally if my rental is in an LLC? Yes, and they routinely try. Plaintiff’s counsel names the LLC and you, then argues you were personally negligent — you did the repair, you knew about the condition, you managed the property yourself. The entity does not shield you from your own conduct. It shields you from liability that belongs to the entity alone. Clean formalities and staying out of hands-on property management are what keep that argument from working.
Is the Bridge Trust® legit? Yes. It is a single trust registered in an offshore asset protection jurisdiction from day one that also meets the court and control tests of Treas. Reg. § 301.7701-7, so it is treated as a domestic grantor trust for U.S. tax purposes while life is calm. I take the common criticisms one at a time in What Critics of the Bridge Trust Get Wrong.
How do real estate investors protect assets from lawsuits? In layers. Insurance first, then property-level LLCs for inside liability, then a holding structure with charging-order protection for outside liability, then a trust layer with jurisdictional separation for significant portfolios. All of it before a claim exists.
Should each rental property be in its own LLC? Generally yes once the equity is meaningful, and each entity should be formed where the property sits. That handles inside liability only — it does nothing about a personal judgment against you.
Does a Wyoming LLC protect property in another state? It protects your ownership interest from your personal creditors. It does not protect the property from a claim arising there, and the state where the property sits governs its own real estate. Huckaby applied that rule in 2026.
Can an out-of-state LLC protect California real estate? Not from California law. The LLC will need to register as a foreign entity, pay California franchise tax, and comply locally — and a premises claim will be litigated in California under California law.
Is a Series LLC a good idea for a multi-state portfolio? It saves cost, and its treatment across state lines is unsettled. For a portfolio spanning multiple states, that introduces an open question at the moment you most need certainty.
Do I need a land trust? It provides privacy, not protection. Whatever liability protection exists in a land trust structure comes from the LLC named as beneficiary, not the trust.
LLC or limited partnership for the holding layer? A limited partnership under a statute with genuine charging-order exclusivity — Arizona’s, for example — is stronger than a single-member holding LLC, because the exclusivity is stated in the statutory text without foreclosure authorization.
Will my lender call the loan if I transfer a property into an LLC? It can. Most mortgages contain a due-on-sale clause, and transferring into an LLC is a transfer. Many lenders do not act on it, but that is a business decision rather than a legal protection.
Does a personal guarantee defeat my LLC protection? For that debt, yes. The lender has a direct claim against you personally, and the entity structure is irrelevant to it.
A tenant is suing me for more than my insurance covers. What can I do? Notify every carrier including umbrella, determine which entity actually owns the property and whether you were sued individually, and do not move assets. A transfer now is voidable and will make your position worse. Forward planning against future unrelated claims remains available.
The Bottom Line
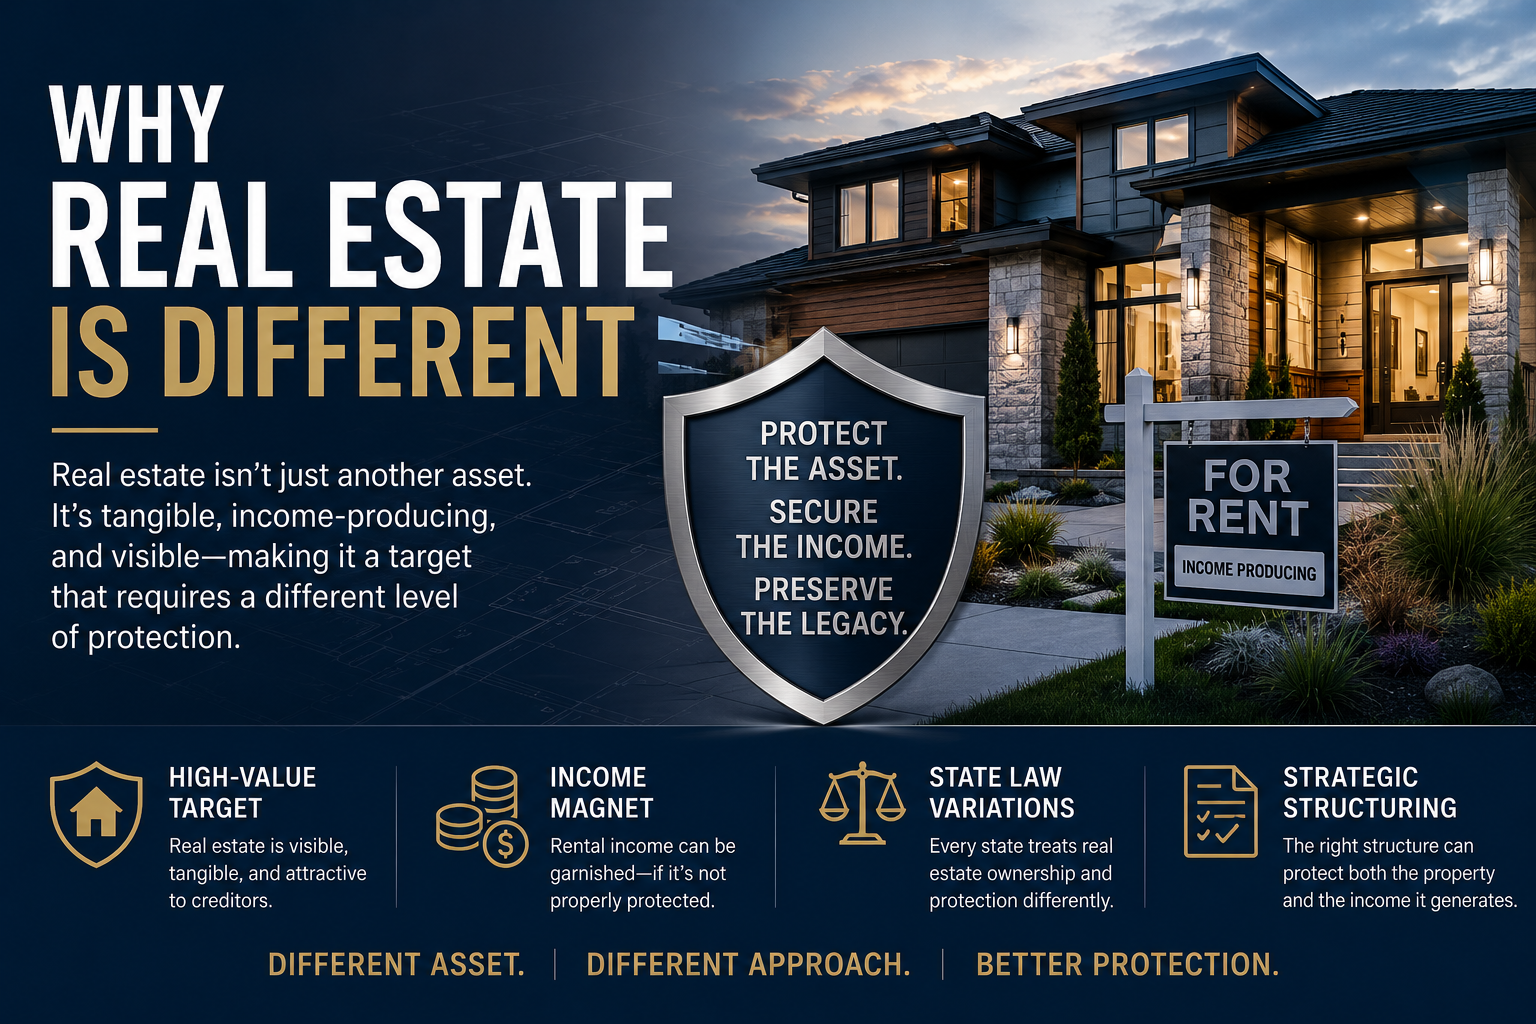
Real estate creates an enforcement problem no other asset class does. It is fixed, recorded, and visible. A plaintiff’s attorney can find every parcel you own before filing.
The question was never whether they can find it. It is whether they can reach the equity, and whether a judge’s practical authority can be pushed back onto legal authority.
Property LLCs solve inside liability. They do not touch outside liability. A holding structure with real charging-order exclusivity does. And a trust layer with jurisdictional separation is what removes your own power to act when you are the one a court is ordering.
I spent years on the plaintiff’s side of civil litigation running exactly this analysis. The structures that came apart came apart for the same two reasons every time: the debtor still controlled what he claimed to have given away, or he built it after the claim was already in view.
Neither is fixable once a lawsuit is filed. Both are entirely avoidable before one.
You don’t rise to the level of your income. You fall to the level of your legal structure.
Structure before stress.
📞 For a confidential legal consultation, contact Bradley Legal Corp. at (888) 773-9399, or complete the intake questionnaire at btblegal.com.
By: Brian T. Bradley, Esq. – National Asset Protection Attorney
Not ready to talk yet?
Take my 2-minute Lawsuit Exposure Test
Answer yes or no. You get an exposure score and see where your risk actually comes from.
Take the Lawsuit Exposure Test