Bradley Legal Corp · Generational planning
Dynasty Trusts
Holding family wealth across generations inside a protective structure, and the tax trade-offs that decide which kind fits.
Request a legal consultationCompare your options →A dynasty trust keeps wealth inside a trust rather than passing it outright, so it is not carved up by transfer taxes and the next generation’s creditors at every hand-off.
What a dynasty trust is
A dynasty trust is an irrevocable trust designed to hold family wealth across multiple generations (children, grandchildren, and beyond) without restarting the transfer tax clock at each generation. The trust owns the assets, not the individuals. A trustee manages them and makes distributions under the terms you set.
A standard estate plan (a revocable trust, a will, an A/B trust) is built for one transfer. At death, assets pass to heirs and become their personal property, reachable by their creditors and divorcing spouses. A dynasty trust keeps the assets inside the structure instead.
How long it can last
The traditional rule against perpetuities limited how long a trust could run. Many states have abolished or extended it. Nevada permits a term of up to 365 years (NRS 111.1031). California follows the Uniform Statutory Rule Against Perpetuities, which generally limits trusts to about 90 years.
The GST exemption: the piece that makes it work
The generation-skipping transfer (GST) tax is a 40% federal tax on transfers that skip a generation. A dynasty trust avoids it at each level only if GST exemption is allocated to the trust. The exemption is $15 million per person ($30 million per couple) beginning January 1, 2026, indexed for inflation.
Three points trip families up:
- Allocation happens on a tax return, not in the trust document: Form 709 for lifetime gifts, and the estate tax return at death. A long-duration trust with no exemption allocated has an inclusion ratio of one, and each generational transfer can be taxed.
- The GST exemption is not portable between spouses. The estate tax exemption is. If the first spouse dies without allocating GST exemption, it is lost permanently.
- The exemption covers value at the time of transfer. Appreciation after funding does not use additional exemption.
What makes it work
Three things have to line up.
The step-up trade-off
Under IRC §1014, inherited assets take a basis equal to fair market value at death, but only if they are in the decedent’s gross estate.
- A traditional dynasty trust is funded by a completed gift. That removes the assets, and all future growth, from your estate. It also gives up the step-up: the trust keeps your original basis.
- Rev. Rul. 2023-2 confirmed that grantor-trust status alone does not put assets back in the estate for step-up purposes. Estate inclusion is the test.
When the trade makes sense: above the exemption, the estate tax a completed gift saves can exceed the capital gains cost of losing the step-up. Below it, there may be no estate tax to save, and the step-up is given up for nothing. The answer turns on your estate’s size and trajectory, your state’s estate tax, and your assets’ basis. Your CPA should run the numbers.
State estate taxes matter. Oregon’s threshold is $1 million. Washington, New York, Massachusetts, and others tax estates well below the federal exemption. State exposure follows where the property sits, not only where you live.
What a dynasty trust does not do
It does not protect the person who funded it if that person remains a beneficiary. A dynasty trust protects beneficiaries who did not fund it. If you remain a beneficiary of a trust you funded, self-settled trust rules such as Cal. Prob. Code §15304 reach your interest in states that do not recognize those trusts.
That gap, protecting yourself now and your family later, is where dynasty planning and asset protection have to be designed together.
Your options
- A traditional completed-gift dynasty trust. Removes future growth from your estate and gives up the step-up. It often fits families well above the exemption.
- Dynasty provisions within a trust that keeps assets in your estate, such as the Dynasty Bridge Trust®. Designed to keep the step-up and add lifetime creditor protection, with the dynasty provisions exercised after death. It often fits families below or near the exemption with real lifetime exposure.
- No dynasty planning yet. If your estate is well inside the exemption, your state imposes no estate tax, and your exposure is modest, the right answer may be to revisit in a few years.
Frequently asked questions
Is a dynasty trust revocable?
No. It is irrevocable.
Does a dynasty trust protect me from my own creditors?
Not in states that reach self-settled trusts, if you remain a beneficiary. It protects beneficiaries who did not fund it.
Does the trust allocate my GST exemption?
No. That is done on a tax return, coordinated with your CPA.
Do I lose the step-up in basis?
With a completed-gift dynasty trust, yes. With a structure that keeps the assets in your gross estate, it is designed to be preserved.
Is a dynasty trust the same as an A/B trust?
No. An A/B trust is a one-generation tool activated at the first death. A dynasty trust is built to last for generations.
About your attorney
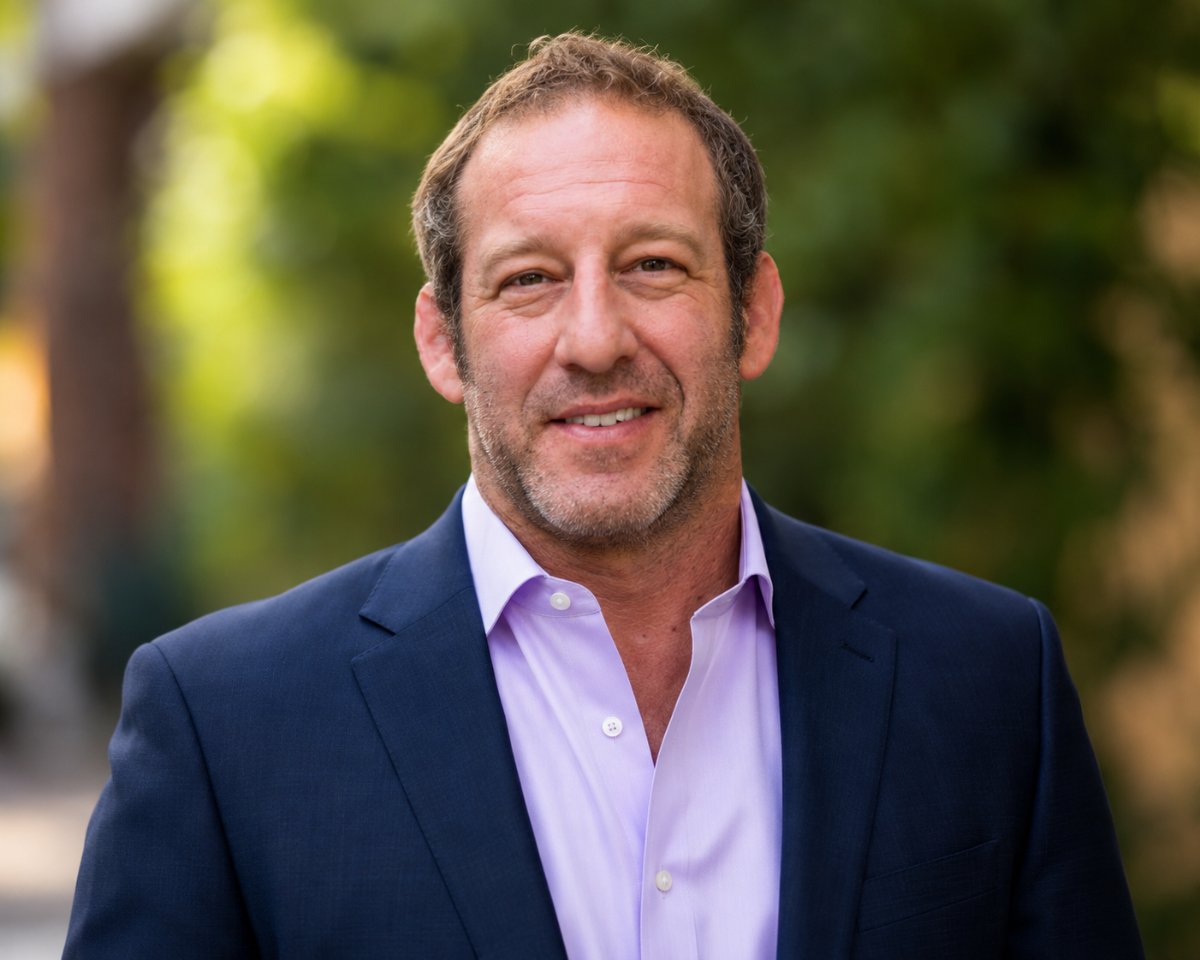
Brian T. Bradley, Esq.
Licensed in California, Oregon & Washington
I spent the early part of my career on the plaintiff’s side of civil litigation in Los Angeles and Orange County, running discovery and taking structures apart. I now use that experience on the other side of the table: designing structures before a claim exists, so they hold when a creditor’s attorney tests them.
I handle trust engagements as co-counsel with the Trust Protector, an affiliated firm that prepares the trust documents, and I am directly involved in every engagement from design through implementation. I am the author of the Over Exposed series.
Asset Protection Council
A national network of legal, tax, and financial professionals. I serve as the Council’s lead attorney.
Structure before stress.
Which dynasty approach fits your family?
It turns on your estate’s size and trajectory, your state’s estate tax, and the basis in your assets. Bring your CPA to the conversation.
Request a legal consultation(888) 773-9399
Attorney advertising. Brian T. Bradley, Esq., Bradley Legal Corp, Wilsonville, Oregon. Licensed in California, Oregon, and Washington, and serving clients nationwide; matters under other states’ law are handled with local counsel where required. This page is general information, is not legal or tax advice, and does not create an attorney-client relationship. Outcomes depend on facts, timing, and jurisdiction.
Disclosure: I handle every trust engagement as co-counsel with the Trust Protector, an affiliated firm that prepares the trust documents and serves as protector on the Bridge Trust® and Dynasty Bridge Trust®. I am directly involved in each engagement, from design through implementation. The legal fee is divided between the two firms, as set out in the engagement letter, and I am paid for that work.