A Seattle developer named Michael Mastro had a better structure than most people reading this.
His house was not in his name. Neither were the jewelry or the cars. Each sat in its own separate series of a Delaware series limited liability company — Series Home, Series Jewelry, Series Automobiles. A trust owned the series, and the trust was administered through what the court later described as a purported Belizean entity.
That is more aggressive than what the average physician or business owner in Bellevue has been sold. It is more layers, more jurisdictions, and more legal fees than almost anyone puts in place.
It came apart anyway.
In Rigby v. Mastro (In re Mastro), 465 B.R. 576 (Bankr. W.D. Wash. 2011), the bankruptcy trustee went after the whole arrangement. The court applied RCW 19.40.041 — Washington’s own fraudulent transfer act — and found the transfers avoidable. Mastro’s wife was held liable for property that had been moved into the trust through those entities. Her claim that the assets were her separate property under their premarital agreement failed, because the agreement itemized the property but nothing in the record substantiated it.
The Delaware series did not save it. The Belize entity did not save it.
I want to be precise about why, because the reason is the entire subject of this article. The structure did not fail because the jurisdictions were weak. It failed because of when it was built and who still controlled what was inside it. The court never had to reach a hard offshore question. Washington law answered it first.
That is the thing almost nobody explains to a Washington family before they sign.
Watch
Living in Washington? Your Wyoming LLC won’t work the way you think
Why Washington Is Harder Than People Are Told
I spent the early part of my career on the plaintiff’s side. My job was to find the seam — the thing the other lawyer did not think a creditor would look at. Washington gives a creditor more seams than most states, and they are all written into the statutes.
A trust you create for yourself is void against your own creditors
Washington has no domestic asset protection trust statute. It has the opposite. RCW 19.36.020 says that a transfer “made in trust for the use of the person making the same” is void as against the existing or subsequent creditors of the person who made it.
Read that twice. Not just against the creditors you have today — against creditors you do not have yet.
Washington courts have applied it to exactly the structure people are sold. See Wiswall v. Wallaert (In re Wallaert), 149 B.R. 665 (Bankr. W.D. Wash. 1992).
So a revocable living trust does what it was designed to do. It avoids probate. It does not stop a creditor, and it was never built to.
Choosing another state’s law does not move the question
The obvious workaround is to use a state that allows what Washington forbids. Alaska. Nevada. South Dakota. Sign the paperwork, name their statute, done.
A Washington bankruptcy court already ran that play to the end. In In re Huber, 493 B.R. 798 (Bankr. W.D. Wash. 2013), a Washington resident created an Alaska trust, named Alaska law, and funded it largely with Washington assets.
The court did not simply honor the choice-of-law clause. It ran a conflicts analysis, found that Washington had the more significant relationship to the trust, and applied Washington law. The transfers were void under RCW 19.36.020. The court then held, separately, that they were avoidable under 11 U.S.C. § 548(e)(1), the ten-year reach-back for transfers into a self-settled trust.
The choice-of-law ruling did not turn on sloppy drafting. It turned on where the settlor lived and where the assets sat. The second holding — avoidance under § 548(e)(1) — turned on timing and intent, which is a separate problem with a separate answer. A later order in the same case held that “void” in RCW 19.36.020 means voidable, so a creditor or trustee still has to act. That is a procedural step, not a defense.
The state whose statute you chose will not necessarily defend it
Here is the part that surprises people. The enacting state may not back you up.
In Toni 1 Trust v. Wacker, 413 P.3d 1199 (Alaska 2018), Alaska’s statute purported to give Alaska courts exclusive jurisdiction over fraudulent transfer claims brought against Alaska trusts. The Alaska Supreme Court held that a state cannot unilaterally strip other state and federal courts of jurisdiction over those claims.
The forum promise at the center of the sales pitch was rejected by the state that wrote it.
Real property is governed where it sits
If you own land, this one decides your case.
In United States v. Huckaby, No. 2:23-cv-00587-DAD-JDP (E.D. Cal. Mar. 2, 2026), two people created a self-settled Nevada spendthrift trust, served as settlors, trustees, and beneficiaries all at once, and put California land inside it.
The court agreed that Nevada law governed how the instrument was read. Then it held that whether a creditor can reach a beneficiary’s interest in a trust of land is governed by the law of the place the land sits. California law applied. The spendthrift restraint failed as to that creditor, and the court authorized foreclosure of the debtor’s one-half interest.
The trust was not voided. The protection simply was not there.
Your Washington LLC can be foreclosed, and then you are out of your own company
Most people have been told the charging order is the end of the road — a creditor gets a lien on distributions, the company stops distributing, and the creditor goes away frustrated.
RCW 25.15.256 does make the charging order the exclusive remedy. Then subsection (2) says this: “A charging order constitutes a lien on the judgment debtor’s transferable interest. The court may order a foreclosure upon the transferable interest subject to the charging order at any time.”
Washington courts say the same thing in plainer language. “The charging order constitutes a lien on the judgment debtor’s transferable interest, which may be foreclosed.” 3320 MLK, LLC v. Helsell Fetterman, LLP, No. 81406-1-I (Wash. Ct. App. Div. One, July 19, 2021) (unpublished; cited as nonbinding under GR 14.1).
Now watch what foreclosure actually does.
In Timberland Bank v. Mesaros, No. 50207-1-II (Wash. Ct. App. Div. Two, May 15, 2018) (unpublished; cited as nonbinding under GR 14.1), a bank obtained a charging order against a debtor’s interest in his single-member LLC. The court foreclosed the interest. The sheriff sold it to a stranger to the lawsuit.
And because all of his transferable interest had been sold, the debtor was dissociated from his own company under RCW 25.15.131(1)(b). Under RCW 25.15.131(3)(a), his right to participate in the management and conduct of the company’s activities ended. He was also held in contempt twice, at a thousand dollars a day, for refusing to turn over the company’s records.
He did not lose the distributions. He lost the company.
One more thing, because it is the most common misconception I hear. The statute says “transferable interest.” It does not say how many members the company has to have. Adding your spouse as a second member does not take a judicial sale off the table.
What Washington Already Gives You for Free
Before anyone sells you anything, know what you already have.
RCW 6.13.030, Washington’s homestead exemption, was rewritten in 2021. The old flat cap is gone. The exemption is now the greater of $125,000 or the county median sale price of a single-family home in the preceding calendar year. In King County that is a serious number, and it applies automatically. No filing. No structure. No fee.
It is also a ceiling, not a shield. It does not reach equity above that amount. It does not cover your practice, your brokerage account, or your rental portfolio. And it does not apply to every kind of creditor.
It is the floor you build on. It is not a plan.
The same goes for the marital estate. Under RCW 26.16.030, property acquired during a marriage is presumed community property, and the spouse claiming otherwise carries the burden of proving it. That cut against Linda Mastro. It will cut against anyone whose separate-property paperwork exists but whose records do not.
What Actually Works in Washington
Nothing above argues for doing nothing. It argues for building the right thing at the right time.
Protection in Washington comes from layered separation put in place before any claim exists. No single tool does the job.
The first layer is asset-level LLCs, formed in the state where the asset actually sits. Huckaby is the reason. If the law of the situs is going to supply the creditor rule for real property, then the entity holding that property should be formed and operating under the law you want applied. A Delaware LLC holding a Tacoma apartment building does not change where the building is.
The second layer is an Arizona limited partnership holding the LLC interests. Under A.R.S. § 29-341, the charging order is the exclusive remedy, and that section contains no foreclosure provision — the remedy RCW 25.15.256 hands a Washington creditor. That is a real difference in the statute, not a difference in marketing.
I will be direct about the limits of that layer. Charging-order exclusivity governs how a judgment creditor collects. Courts have carved out exceptions — receivership, reverse veil piercing, alter ego, fraudulent transfer — and it does not survive bankruptcy. What the domestic layers do is raise the cost and the difficulty of collection. That is worth real money in a negotiation. It is not a wall.
The third layer is the Bridge Trust®, holding the partnership interest.
The Bridge Trust® is one trust, not two. It is registered in an offshore asset protection jurisdiction from the day it is signed — the Cook Islands, with Belize registration as well — and a licensed offshore trustee is engaged on day one as Special Successor Trustee. At the same time, it is built to satisfy the court test and the control test of Treas. Reg. § 301.7701-7, so it is treated as a domestic trust for United States tax purposes, and as a grantor trust under IRC §§ 671–677.
Think of it as holding two passports at once.
While life is calm, it behaves like an ordinary domestic trust. You can serve as trustee during normal operations. You file the same 1040 you filed last year. There is no completed gift, no offshore filing obligation, and the step-up in basis at death under IRC § 1014 is preserved.
Serving as trustee is not the same as controlling the structure. The Mastro court found effective control because the settlor sat on a one-man advisory committee that controlled the protector, which controlled the trustee — so he could pull every asset back to himself at will. A properly built structure does not wire that path. The Trust Protector is independent of the person who funded the trust, and the settlor cannot declare the shift to foreign administration.
If a serious creditor threat materializes, an independent Trust Protector — never you — can declare an Event of Duress, and control shifts to the pre-committed offshore trustee. Nothing new transfers at that moment. The trust was always foreign. That is the entire point, and it is the part worth slowing down for.
Here is the honest version of why that matters, and it brings us back to Mastro.
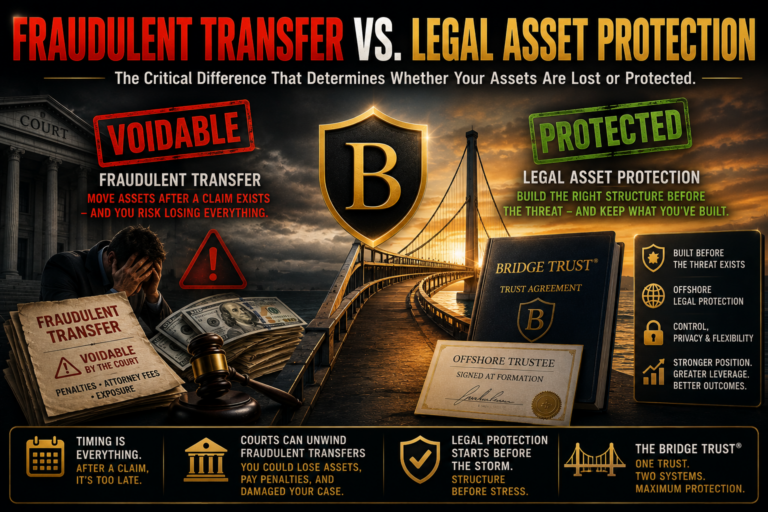
A creditor’s best argument is almost never about Cook Islands law. It is that you moved assets when you could already see the claim coming. That is a timing-and-intent argument under RCW 19.40.041, and it is decided in a Washington courtroom long before anyone has to think about a foreign trustee. Mastro lost on exactly that ground. The offshore question never had to be reached.
So the strength of a jurisdiction only matters if you get there. You only get there if the transfer was clean when it was made.
A Note on Nevada, Since Most Washington Readers Have Been Pitched One
People sometimes hear that the Bridge Trust® uses a Nevada situs and ask whether that is the same thing as the Nevada trust they were offered.
It is not, and the difference is worth understanding.
A Nevada DAPT asks a Washington court to apply Nevada’s self-settled trust statute instead of RCW 19.36.020. That is the argument Huber rejected.
The Bridge Trust® does not make that argument. Administrative situs supports the court test under Treas. Reg. § 301.7701-7 — a tax classification question. It is not the thing standing between you and a creditor. The offshore registration is.
One of those structures depends on a state statute surviving a conflicts analysis. The other does not.
The Decision You Are Actually Making
Strip away the structures and there is one variable that decides everything, and it is not which state is on the signature page.
It is when.
Under 11 U.S.C. § 548(e), a bankruptcy trustee can reach back ten years to undo a transfer into a self-settled trust made with intent to hinder a creditor. Outside bankruptcy, a Washington creditor uses chapter 19.40 RCW, with its own limitations provision at RCW 19.40.091.
Either way, structure built after the threat is not protection. It is evidence. Every case in this article turned on timing, control, or where the asset sat — not on the quality of the drafting.
I cannot promise you an outcome. No lawyer can, and anyone who does is telling you something they cannot deliver. What a properly built structure changes is the position you negotiate from — how expensive you are to collect against, how long it takes, and how much a plaintiff’s attorney has to spend to find out. I know what that calculation looks like, because I used to run it from the other side of the table.
The window for this closes quietly. There is no notice. One day you are planning, and the next day you are reacting, and the law treats those two people very differently.
Structure before stress.
Resources
- What Is the Bridge Trust®? A Plain-English Guide to Hybrid Asset Protection
- Cook Islands Trust: How It Works, What It Costs, and When You Need One
- Asset Protection Trusts: Domestic, Foreign & Hybrid Compared
- LLCs and the Asset Management Limited Partnership
- Washington Families With $15M+ Are Sitting on a State Estate Tax Problem
- Irrevocable vs. Revocable Trusts: Which One Protects Assets From Creditors?
Brian T. Bradley, Esq. is licensed in Washington, Oregon, and California and represents clients nationwide. Request a legal consultation.