A revocable trust provides no protection from creditors. Control is ownership — because you can revoke the trust and take the assets back, a court can reach them exactly as if the trust did not exist. An irrevocable trust can protect assets, but only if it genuinely divests control, and only if it is built before a claim arises.
Most families, business owners, and professionals are told they’re protected because they have a living trust. They’re not.
Estate-planning attorneys design revocable trusts to transfer assets when you die — not to defend them while you’re alive. That distinction is more consequential than most people realize. A lawsuit filed on a Tuesday afternoon doesn’t care whether you have a beautifully drafted trust with your name on it. What matters is whether the law considers you to still own those assets. In a revocable trust, you do.
True asset protection begins where traditional estate planning ends — with irrevocable, court-defensible structures that separate ownership from control without triggering IRS reporting problems or fraudulent-transfer exposure.
Understanding the Two Foundations
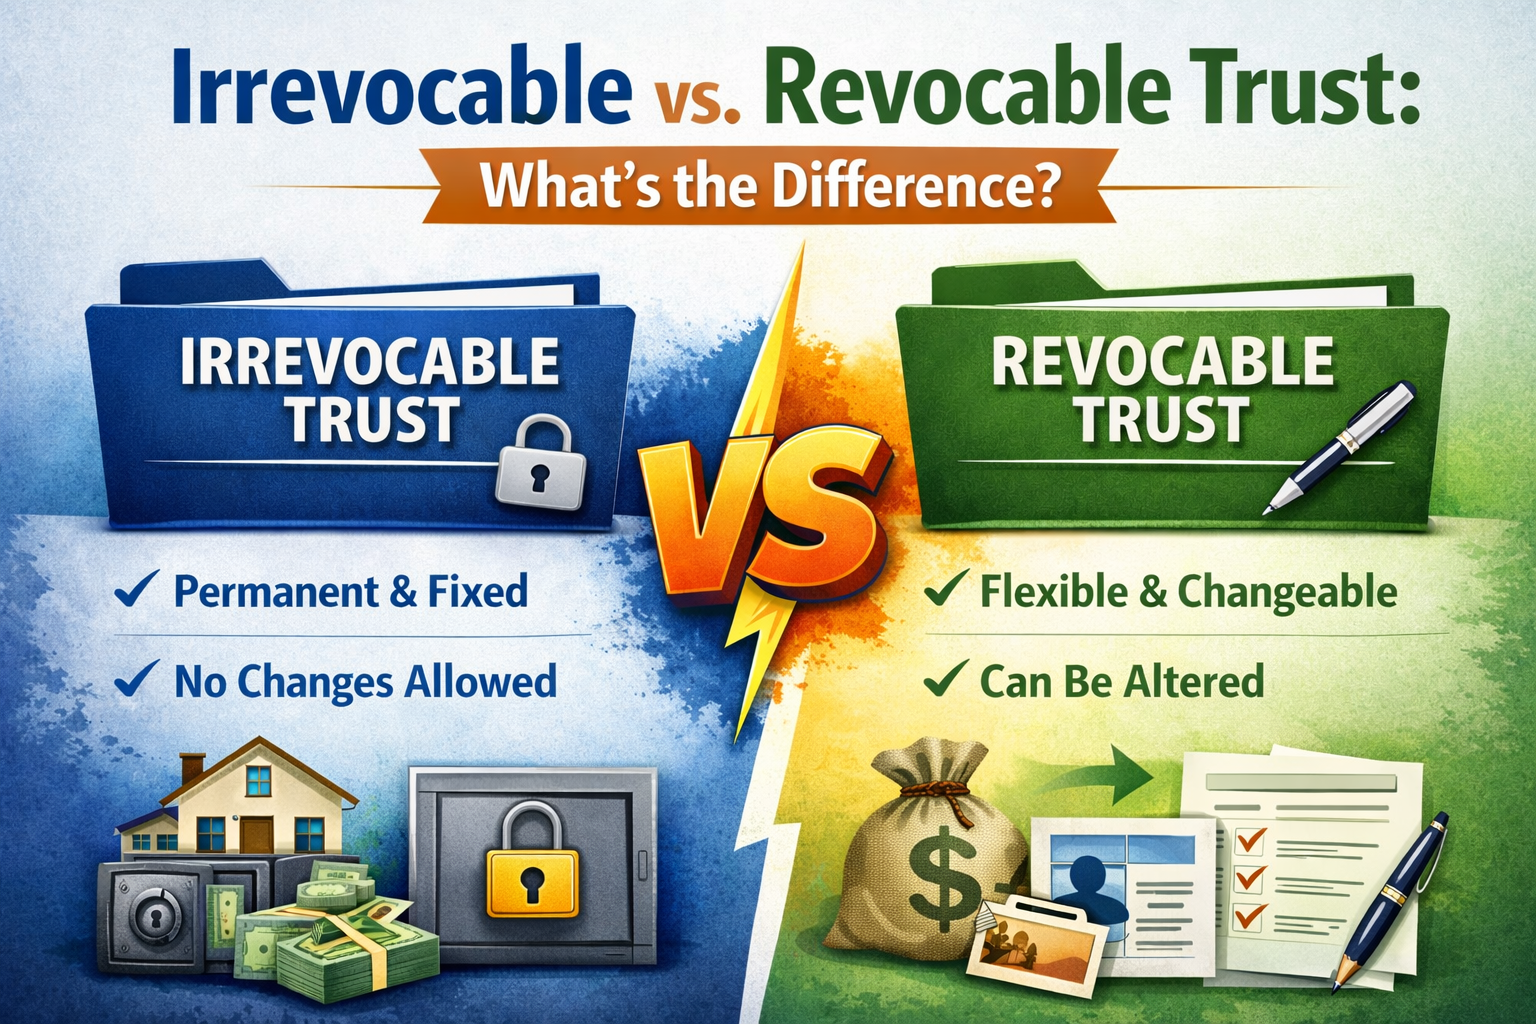
A revocable trust — commonly called a living trust — is an estate-planning tool, not a shield. The grantor retains full control: you can add or remove beneficiaries, move assets in and out, and revoke the trust entirely. That flexibility is the point. It lets your estate bypass the probate process after death, preserves privacy, and ensures cleaner transfers to heirs.
But that same flexibility is the fatal flaw for asset protection purposes. Because you retain control, the law treats those assets as still yours — personally and completely. A creditor who wins a judgment against you can reach everything inside a revocable trust just as easily as everything held in your individual name. Courts don’t look at the wrapper. They look at who really controls the asset.
An irrevocable trust operates differently. When properly structured, it removes assets from your personal ownership and transfers authority to an independent trustee. That legal separation — ownership in one legal entity, control in another — is what creates protection. A creditor can’t easily reach assets you no longer legally own. They must overcome the independent legal structure itself.
The protection comes with trade-offs. Once established, an irrevocable trust is difficult or impossible to modify. It typically requires its own tax identification number and a separate annual return (Form 1041). And if the trust, trustee, and assets all remain within the United States, the jurisdictional advantage is limited — a domestic judge can compel a domestic trustee to cooperate, order assets turned over, and evaluate transfers for fraudulent intent under state law.
The core rule is simple: control equals ownership, and ownership equals exposure. Irrevocability removes that exposure — but it often does so at the cost of flexibility you may need when circumstances change.
Why Domestic Irrevocable Trusts Fail Under Pressure
The promise of domestic asset protection trusts — DAPTs offered in states like Nevada, South Dakota, Alaska, and Delaware — is that you can create an irrevocable trust for your own benefit and still receive protection from future creditors. In theory, this sounds like exactly what you want. In practice, courts have declined to honor that promise with uncomfortable frequency.
In In re Mortensen (Bankr. D. Alaska 2011), a bankruptcy trustee successfully voided an Alaska self-settled trust, finding the transfer was made with intent to delay creditors — Alaska’s own protective statute couldn’t immunize it. In In re Huber, 493 B.R. 798 (Bankr. W.D. Wash. 2013), the trust was created in Alaska and designated Alaska law, which permits self-settled asset protection trusts under AS 34.40.110. The court ran a choice-of-law analysis, applied Washington law instead, and held the transfers void under RCW 19.36.020 — Washington does not recognize such trusts. It then found the transfers independently avoidable under 11 U.S.C. §548(e)(1). No federal statute preempted anything. The settlor simply did not control which state’s law the court would apply. In Kilker v. Stillman (Nov. 26, 2012, G045813), an unpublished California decision, the debtor transferred real property into a Nevada entity he had formed, having told a deposition that creditors “could not get at any equity” he held in it. The court found a fraudulent transfer under Civ. Code §3439.04(a). His argument that Nevada law authorized the structure failed for a simple reason: Nevada has enacted the same Uniform Fraudulent Transfer Act. Because the opinion is unpublished it is not citable under Cal. R. Ct. 8.1115(a), and is included here as illustration rather than authority. The trust was never the problem. The timing was. In Toni 1 Trust v. Wacker, 413 P.3d 1199 (Alaska 2018), Alaska’s own supreme court held that the state’s exclusive-jurisdiction provision, AS 34.40.110(k), cannot unilaterally deprive other state and federal courts of jurisdiction. The trust itself was not invalidated. What failed was the premise that a state can route every challenge to its own courthouse — and a Montana judgment creditor proceeded anyway. In Dahl v. Dahl, 2015 UT 23, 345 P.3d 566 (Utah 2015), the trust designated Nevada law. The Utah Supreme Court refused to enforce that choice-of-law provision, holding that Utah has a strong public policy interest in the equitable division of marital assets. Construing the trust under Utah law instead, it held the trust was revocable and that the wife had an interest in the trust property as a settlor. The settlor picked the law. The forum court picked a different one. And just this year, in United States v. Huckaby, No. 2:23-cv-00587-DAD-JDP (E.D. Cal. Mar. 2, 2026), a federal district court allowed the IRS to foreclose on California real property held inside a Nevada DAPT — applying California law rather than Nevada’s protective statute because the asset was physically located in California. Since Huckaby served as both trustee and beneficiary, he retained sufficient legal and equitable interest for a federal tax lien to attach. A Nevada trust instrument held no weight against California’s rule that a settlor cannot shield assets from creditors while remaining a beneficiary.
The lesson across all six cases is the same: domestic trusts fail when a court — state or federal — decides to look past the wrapper. Location of the asset, identity of the trustee, and degree of retained control are the variables that determine outcome under real enforcement pressure. The label on the trust instrument is not.
The Bridge Trust®: Offshore Protection Without Offshore Reporting
The Bridge Trust® was developed nearly 30 years ago to solve the jurisdictional problem that domestic irrevocable trusts cannot solve on their own. It is a Cook Islands trust that is also registered in Belize from inception, with a licensed offshore trustee engaged from day one as Special Successor Trustee — offshore in legal character from the day it is signed. At the same time it is classified as domestic for U.S. tax purposes under the court and control tests of Treas. Reg. §301.7701-7, and is a grantor trust under IRC §§671–677. In that posture, the trust is completely tax-transparent. Income flows directly to your individual return. No Form 3520. No offshore reporting obligations. No PFIC exposure. None of this is concealment. The trust is fully disclosed and fully reported — it reports the way any domestic grantor trust reports, because in that posture that is what it is.
What makes the Bridge Trust® structurally different is its pre-engineered offshore activation mechanism. If the Trust Protector declares an Event of Duress and a licensed Cook Islands trustee is appointed and assumes control of substantial trust decisions, § 7701’s control test is no longer satisfied. The trust reclassifies as foreign, and administration sits with the offshore trustee, who is not subject to a U.S. court’s contempt power — though you remain subject to it personally. No structure puts anyone beyond the reach of a court that has jurisdiction over them; what changes is what a creditor can practically reach and what it costs to try. All of this happens without requiring you to re-title assets, create new entities, or file emergency motions.
The Cook Islands offers something no U.S. jurisdiction can match: a legal environment designed from the ground up to be hostile to creditor attacks on properly established trusts. Foreign court judgments are unenforceable there. Creditors who want to challenge a transfer must re-litigate the entire claim under Cook Islands law — bearing the burden of proving fraudulent transfer beyond a reasonable doubt, the highest evidentiary standard available in any jurisdiction. They face a strict statute of limitations running from the date of transfer. And they must retain Cook Islands counsel and litigate in a Cook Islands court, with no procedural assistance from any U.S. judgment they already hold.
This is why the Bridge Trust® architecture has been in continuous use for roughly three decades. No appellate court has construed it, and no court has ordered assets extracted from one after a duress declaration. The challenges it has faced were all at the trial level, and all resolved by settlement. Read that for what it is: it reflects how these matters resolve — privately, or before a creditor gets that far — not a published record of wins. The structure isn’t theoretical. It has been tested in real adversarial proceedings — exactly the condition under which most estate planning tools quietly fail.
Does an Irrevocable Trust Need an Independent Trustee?
For creditor protection, yes — and this is the single most common drafting failure I see. An irrevocable trust whose grantor still serves as trustee, or who can remove and replace the trustee at will, has not divested control. It has relabeled it.
The reason is the same principle that defeats the revocable trust. A creditor stands in your shoes. If you can direct distributions to yourself, a court can order you to direct them to your creditor. Dahl shows the related danger: the settlor chose Nevada law, and the Utah court refused to apply it and construed the trust as revocable under Utah law. Neither the word on the cover page nor the governing-law clause decided the question. The forum did.
A court does not need the word “revocable” to get there. It looks at what you can actually do. In Kokoszka v. Samatas (In re Samatas), 678 B.R. 109 (Bankr. N.D. Ill. 2026), the debtor was a beneficiary, a co-trustee, and the trust’s investment advisor. The co-trustee deferred to him on everything. The court found he exercised dominion and control over the trust, and the spendthrift provision did not shield the assets. Stacking roles is how an irrevocable trust becomes your bank account in the eyes of a court.
The drafting can fail even when the roles are clean. In Linscott v. Kittrell (In re Kittrell), No. 4:22-bk-01130-BMW, Adv. No. 4:22-ap-00206-BMW (Bankr. D. Ariz. July 24, 2026), the trust was irrevocable by its terms, carried an express anti-reversion clause, and named only the grantors’ children and grandchildren as beneficiaries. The grantors were never named as beneficiaries at all. But a power of appointment could be exercised in favor of “descendants of the Grantor’s parents” — a class that includes the grantors themselves. The court treated it as self-settled, avoided the transfer under 11 U.S.C. §548(e), and entered a $6.5 million judgment. Four words in a class definition undid the whole instrument.
What independence actually requires is narrower than most people expect, and broader than most documents deliver. The trustee must be someone with no obligation to follow your instructions — not your spouse, not a business partner who depends on you, not an entity you control. Distributions must be genuinely discretionary with that trustee. And your power to replace the trustee, if you keep one at all, must be limited to replacing them with another independent party, for cause.
Retaining some influence is possible, and legitimate. A trust protector can hold the power to replace a trustee who is performing badly, to change administrative situs, or to adapt the trust to a change in law. What matters is that the protector is independent of you, and that the powers retained do not amount to control over whether you get the money. A structure that keeps you comfortable is usually a structure that keeps you exposed.
Comparing What These Structures Actually Do
A revocable trust is a probate-avoidance tool. It keeps your estate out of the public probate record, simplifies transfers to heirs, and provides administrative convenience during incapacity. It does not protect you from creditors, plaintiffs, or judgments — not even slightly.
A traditional irrevocable trust provides protection through ownership separation. Removing assets from your personal estate makes them harder to reach. But the limitation is jurisdictional: a domestic trustee operating under a domestic court’s authority can be compelled. The independence of the structure is real in theory. In enforcement, it is more fragile than the documents suggest — as the cases above show.
The Bridge Trust® combines the accessibility of a domestic structure’s day-to-day operation with the jurisdictional strength of a properly established offshore trust. During calm periods, you function as your own managing trustee. That is a deliberate trade-off, and it is worth being direct about it. While you hold that role, the structure is not relying on trustee independence to stop a creditor — it is relying on the Cook Islands trustee already being in place, and on the Protector’s power to move administration there. The protection is jurisdictional, not custodial. That is why the Protector must be independent of you: the one power that matters is the power to declare an Event of Duress, and if you held it, a court could order you to un-declare it. That is not a theoretical concern. In Lawrence v. Goldberg (In re Lawrence), 279 F.3d 1294 (11th Cir. 2002), the Eleventh Circuit held a duress clause void precisely because it “leaves to the settlor and the Trustees the discretion to determine when an event of duress has occurred.” Who holds that determination is the whole question. Your assets remain available to you as a discretionary beneficiary. No offshore reporting is triggered. When a credible threat appears, an independent Trust Protector — not you — may declare an Event of Duress. That declaration suspends your authority under the terms of the instrument, and appointing the offshore successor trustee is a separate, discretionary decision that may follow. Nothing fires automatically on the filing of a complaint. The mechanism is already embedded in the governing instrument from day one.
The practical translation is straightforward. Revocable trusts manage inheritance. Domestic irrevocable trusts primarily manage estate-tax exposure and Medicaid positioning. The Bridge Trust® defends your wealth against the threat that neither of those tools was built to address — the plaintiff attorney with a contingency-fee retainer, the IRS with a tax lien, and the bankruptcy trustee who knows exactly which statutes to invoke.
Why Timing Is Not Optional
Asset protection law across all U.S. jurisdictions — and under the Uniform Voidable Transactions Act, which the majority of states have now adopted — subjects transfers made after a claim arises to close scrutiny — not an automatic presumption of fraud, but a far harder position to defend. The analysis turns on two questions: whether you were insolvent at the time of transfer, and whether the transfer was made with intent to hinder, delay, or defraud a creditor. A structure built in the weeks before a judgment is entered will be attacked and likely unwound. A structure established years earlier, before any dispute existed, carries a completely different legal posture.
This is not a technical footnote. It is the single most important practical constraint on legitimate asset protection planning. The structure has to exist before the threat — before the dispute, the lawsuit, the investigation, or the deal that goes sideways. Once that clock starts, your planning window has closed.
Conclusion
Revocable trusts are for estate transfer. Traditional irrevocable trusts create ownership separation, with the jurisdictional limitations that come with domestic courts and domestic trustees. The Bridge Trust® was engineered specifically to deliver the flexibility of a domestic structure and the enforcement resistance of an offshore one — tax-neutral, fully compliant with U.S. law, and pre-tested against real legal attacks over three decades.
If your exposure is real — business liability, professional risk, substantial real property, a concentrated investment position, or a liquidity event on the horizon — the question isn’t whether you need a structure. The question is whether the one you have would survive a serious challenge.
You don’t rise to the level of your income. You fall to the level of your legal structure.
Schedule a legal consultation at (888) 773-9399.
Structure before stress.
By: Brian T. Bradley, Esq.