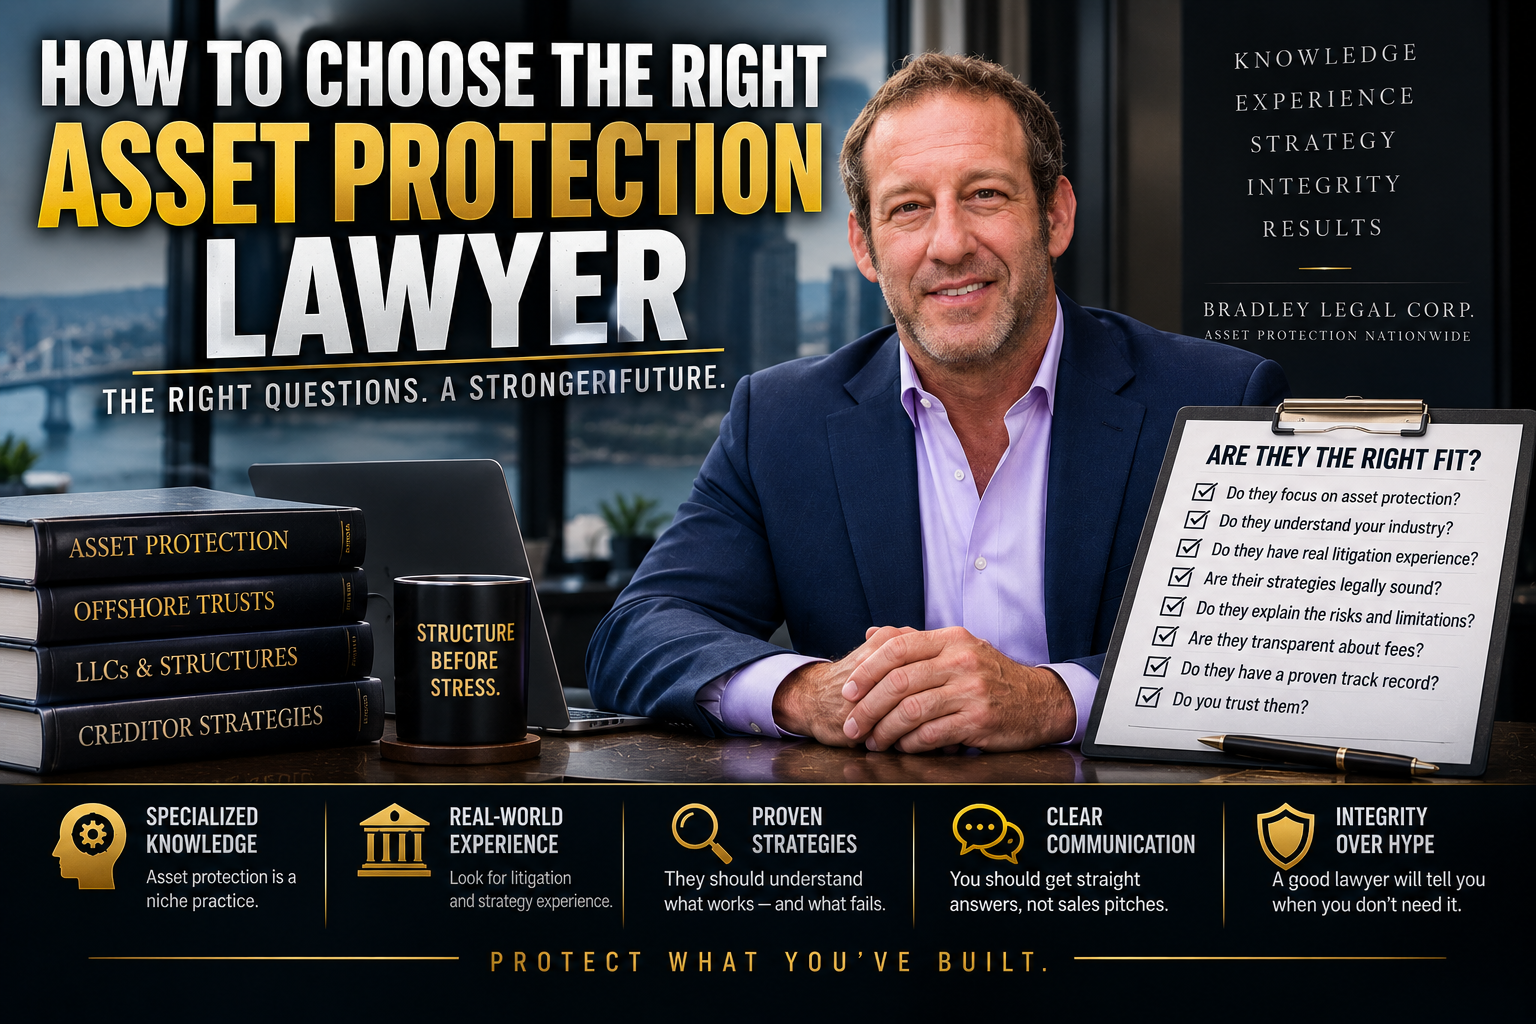
The fastest way to evaluate an asset protection attorney is to ask questions whose answers you can verify. Ask what happens on day one of a lawsuit, which cases they think went badly and why, whether the plan changes your tax return, and what they would refuse to do. A specialist answers those precisely. A promoter deflects, oversells, or promises a result.
This is not a list of things to Google. It is a set of questions to ask in a consultation, with what a competent answer sounds like next to what should end the conversation.
Key Points
- Attorney-client privilege is the first filter. Non-lawyer promoters and LLC formation mills cannot protect your communications from a subpoena.
- Ask about failures, not successes. Anyone can describe a structure. Only someone who has read the case law can tell you what defeats one.
- Tax-neutral is the correct answer. A plan sold as reducing taxes is either a different product or a problem.
- Timing is the threshold question. If the attorney does not ask when your exposure started before quoting a price, they are selling a document.
- “Guaranteed” and “untouchable” are disqualifying words. No structure guarantees an outcome.
- A domestic-only plan in a non-DAPT state is a warning sign, not a cost saving.
Why This Decision Is Harder Than It Should Be
Asset protection sits at the intersection of trust law, creditor rights, conflict of laws, tax, and litigation strategy. Very few attorneys work across all five, and the barrier to claiming the specialty is nearly zero.
The result is a market where an estate planning attorney with a form book, a business lawyer who has read about charging orders, and a non-lawyer promoter selling Wyoming LLCs are all competing for the same client using similar language.
The questions below are designed to be hard to fake.
1. Are You a Licensed Attorney, and Does Privilege Apply?
The answer must be an unqualified yes, from someone licensed and in good standing. Non-lawyer promoters, formation companies, and “trust consultants” cannot assert attorney-client privilege, which means your planning conversations and documents are discoverable.
What a good answer sounds like: the attorney names their bar admissions without hesitation, and can explain what privilege does and does not cover in an asset protection engagement.
What should end the meeting: anyone selling structures who is not an attorney, or who is vague about whether an attorney is actually involved in the drafting.
This matters more here than in most legal work. In a creditor proceeding, the other side will try to discover how and why your structure was created. Privilege is the reason they cannot.
2. What Happens on Day One of a Real Lawsuit?
A specialist will walk you through the actual enforcement sequence — who files, what discovery looks like, what a judgment creditor can do, and where your structure creates friction. A generalist will describe the documents.
This is the single most revealing question you can ask, because it separates people who have thought about enforcement from people who have thought about drafting.
What a good answer sounds like: they describe the debtor’s examination, the subpoenas to your bank and registered agent, the charging order and what it does and does not reach, and the point in the sequence where a creditor’s attorney runs the math on collectibility and decides whether to keep spending.
What should end the meeting: an answer that stops at “the assets are in the trust, so they’re protected.”
Asset protection works by making collection uneconomic. If your attorney cannot describe the collection process in detail, they cannot design against it.
3. Which Asset Protection Cases Have Gone Badly, and Why?
Ask them to name cases where structures failed. Someone who works in this area can name several and explain the specific defect in each. Someone who cannot is working from marketing material.
What a good answer sounds like: they can distinguish failures by cause. Toni 1 Trust v. Wacker (Alaska 2018) — a state’s own supreme court holding that its DAPT statute cannot bind other states or federal courts. In re Huber and Battley v. Mortensen — home-state law and the ten-year bankruptcy reach under 11 U.S.C. §548(e). United States v. Huckaby (E.D. Cal. 2026) — a self-settled Nevada trust that could not shield California real property, because land is governed by the law where it sits. FTC v. Affordable Media — settlors jailed for contempt because they stayed on as trust protectors of their own trust with power to reverse the freeze.
What should end the meeting: an attorney who cannot name any of them.
There is an important distinction here. A firm saying its own structures have not failed is a track-record statement, and if it comes with the honest qualifier — where the structure was properly established and funded in time — it is a fair thing to say. What is disqualifying is an inability to discuss the cases in the field where structures did fail. That is not confidence. It is unfamiliarity with the material a creditor’s attorney will be reading.
The failures follow three patterns — reactive timing, retained control, and reliance on one state’s statute in another state’s courtroom. An attorney who cannot articulate those three patterns has not read the case law.
4. When Did My Exposure Actually Start?
A specialist asks this before quoting a price, because it determines whether they can help you at all. Fraudulent transfer law measures a transfer from the date it was made, and a claim becomes “foreseeable” well before a complaint is filed.
What a good answer sounds like: they ask about demand letters, adverse events, regulatory inquiries, notices of intent, and deals that went sideways — and they explain that a structure funded after a claim is foreseeable is a voidable transfer that can make your position worse.
What should end the meeting: anyone willing to build a structure for you after you have described a pending or threatened claim, without explaining the fraudulent-transfer consequences.
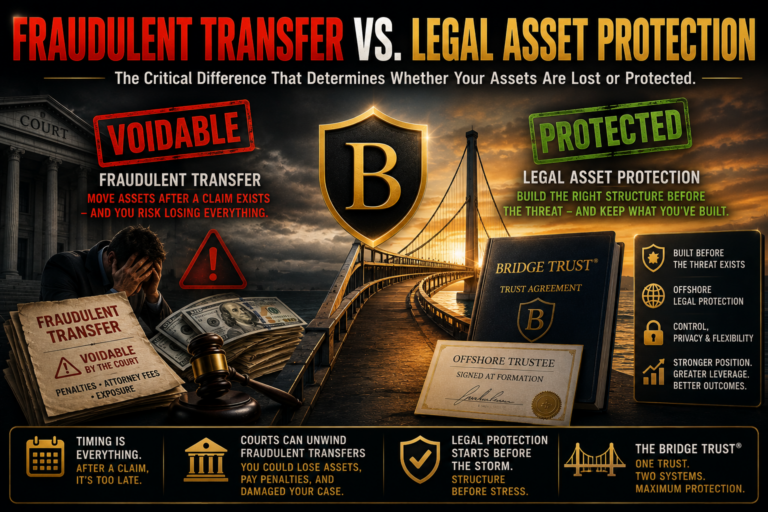
Under the Uniform Voidable Transactions Act, a court can unwind a transfer made with intent to hinder or delay creditors, and separately unwind one made without reasonably equivalent value while you were insolvent — the second requiring no bad intent at all.
5. Is the Plan Tax-Neutral?
The right answer is yes, without qualification. Asset protection and tax reduction are different disciplines, and structures sold as doing both are usually doing neither well.
What a good answer sounds like: the attorney explains that income continues to flow through to your personal return, identifies which forms you will and will not file, and states plainly that the plan does not reduce, defer, or hide tax.
What should end the meeting: any promise of tax savings as part of the protection pitch, or any suggestion that offshore means unreported.
Legitimate offshore structures are fully reportable. Depending on classification, that can include Forms 3520 and 3520-A, Form 8938, Schedule B, and an FBAR — with penalties under IRC §6677 measured against asset value rather than tax owed. You can owe zero additional tax and still face six figures of exposure from a missed form.
6. What Would You Refuse to Do?
This is the question promoters cannot answer. A real practice has a list of engagements it declines — clients already in litigation, assets of questionable origin, anyone whose goal is concealment rather than protection.
What a good answer sounds like: they describe the fact patterns where they say no, and why. Someone arriving after a judgment, someone with criminal activity, someone wanting to hid assets to avoid paying taxes. In some circumstances it’s often better served by relying on exemptions that already exist than by building something new that will be attacked.
What should end the meeting: an attorney with no disqualifying criteria at all. “It’s never too late.”
A practice that takes every engagement is a practice that will take yours regardless of whether the timing works.
7. Does the Plan Depend on One State’s Statute?
If the answer is yes and you do not live in that state, ask directly what happens when you are sued at home. That question has a well-documented answer, and it is not favorable.
What a good answer sounds like: the attorney distinguishes the internal affairs doctrine — which governs how an entity or trust is managed and does follow the state of formation — from creditor enforcement, which follows the forum where you are sued. They explain that a Nevada or Wyoming statute does not travel with you.
What should end the meeting: “We’ll set it up in Nevada, so Nevada law applies.”
Three cases answer that directly, from three different directions.
Toni 1 Trust v. Wacker, 413 P.3d 1199 (Alaska 2018) — published state supreme court authority. Alaska’s own high court held that its DAPT statute cannot divest other states or federal courts of jurisdiction. When the state that wrote the statute concedes the limit, the question is settled.
Kilker v. Stillman — a California court disregarded a Nevada asset protection trust for a California-resident settlor, finding the transfer voidable under California’s fraudulent transfer act even though no claim was pending when the trust was funded. The court treated the eventual plaintiffs as “reasonably foreseeable” creditors. Note the posture: the opinion is unpublished and non-citable as authority under California Rule of Court 8.1115, so it is an illustration of judicial attitude rather than precedent — and an attorney who cites it to you as binding law has told you something.
United States v. Huckaby, No. 2:23-cv-00587-DAD-JDP (E.D. Cal. Mar. 2, 2026) — a self-settled Nevada trust could not shield California real property from a federal judgment lien. Under Restatement (Second) of Conflict of Laws §280, California law governed creditor access because the land sits in California, and Cal. Prob. Code §15304 voided the self-settled protection.
A related check: real estate is governed by the law of the place it sits. You cannot move dirt. Any plan that puts out-of-state property directly into a trust or an out-of-state LLC and calls it protected has misunderstood the situs rule that decided Huckaby and Cursi.
8. Who Controls the Assets, and What Changes Under Pressure?
Retained control is the single most common cause of failure. Ask specifically what powers you keep, what happens to those powers if a creditor threat arises, and who makes the decision.
What a good answer sounds like: the attorney can explain exactly which of your powers are suspended when a threat materializes, and identifies who holds the protective decision — someone independent of you and not subject to the same court order.
What should end the meeting: a structure where you remain in the decision loop after a threat appears, or one that fires automatically on the filing of a complaint.
Two cases define both ends of this, and any attorney working in this area should be able to walk you through them.
FTC v. Affordable Media, LLC, 179 F.3d 1228 (9th Cir. 1999) — the Andersons established a Cook Islands trust in July 1995, nearly three years before the FTC filed in April 1998. Timing was not their problem. They named themselves co-trustees and trust protectors, and as protectors they retained the power to override the event of duress or replace the trustee. When ordered to repatriate, the offshore trustee declared duress and refused — twice, including after they tried to install their children as replacements. The assets never came back, and the FTC later lost in the Cook Islands with costs awarded against it. But the Andersons went to jail, because holding a live control mechanism over the trust meant they could not establish impossibility.
United States v. Grant — the other end. Ordered to repatriate, Mrs. Grant complied with the request, and when the trustee refused she attempted to replace the trustee. She was unsuccessful for more than two years. The court found the failure was not for lack of effort and that she was genuinely unable to comply, and denied the government’s motion. Control had actually been relinquished.
Grant also produced the drafting instruction. The trust gave her the “non-reviewable, sole and complete discretion to remove and replace the Trustee at any time” — a power that nearly sank her. The fix is one clause: make that power exercisable only when the beneficiary is not acting under duress.
Ask whether the instrument you are being sold contains that limitation. It is a specific, checkable question, and the answer tells you whether the drafter has read the case law or copied a form.
Both extremes fail. Retained control defeats impossibility. At the other end, a clause that triggers mechanically on a lawsuit reads to a court as pre-programmed obstruction. What works is a documented decision by an independent fiduciary — which puts a witness on the record who can testify to reasoned judgment.
9. Do You Work With Clients Like Me?
Exposure profiles are not interchangeable. A physician’s malpractice risk, a real estate investor’s premises and guarantee exposure, and a founder’s pre-liquidity window each require different structures and different timing.
What a good answer sounds like: they can describe the specific failure modes in your profession — for a surgeon, what a claim exceeding policy limits does to a personal balance sheet; for an investor, why single-member LLCs are the weakest position on the charging-order axis; for a founder, why the window before a sale closes is the highest-leverage moment available.
What should end the meeting: a single structure recommended before they have asked what you own and where.
10. What Will You Not Promise Me?
The right answer includes the word “outcome.” No structure guarantees a result, and any attorney who says otherwise is either inexperienced or selling.
What a good answer sounds like: the honest frame — a properly built and properly timed structure does not make you judgment-proof. It changes the position you negotiate from, and it changes what collection costs. Most matters resolve at the leverage and settlement stage rather than through a courtroom ruling.
What should end the meeting: “untouchable,” “impenetrable,” “hidden,” or “guaranteed.”
Those words are marketing, and in most states they are also a problem under the advertising rules.
Common Pitfalls That Void Otherwise-Good Plans
Improper timing. Transfers must precede foreseeability, not filing. This is the most common failure and the only one that cannot be fixed later.
Insolvency after funding. You must remain able to pay reasonable debts. A transfer without reasonably equivalent value that leaves you insolvent is voidable with no proof of intent required.
Assets in the wrong container. Real property in a trust rather than a state-matched entity. Operating businesses commingled with passive holdings. Single-member entities where multi-member would hold.
Misalignment with the estate plan. A protection structure and an estate plan drafted by different people who never spoke produce gaps at exactly the moment both are tested.
Concealment. Undisclosed accounts and incomplete discovery responses turn a survivable civil problem into a criminal one. Discovery responses are made under oath.
FAQs
How do I choose an asset protection attorney? Ask questions with verifiable answers — what happens on day one of a lawsuit, which cases have gone badly and why, when your exposure started, and what they would refuse to do. Specialists answer precisely; promoters deflect or oversell.
What’s the difference between an estate planning attorney and an asset protection attorney? Estate planning transfers wealth at death. Asset protection defends it from creditors during life. The two overlap but require different expertise — particularly around self-settled trust doctrine, conflict of laws, and fraudulent transfer timing.
How much should asset protection cost? It varies by complexity and jurisdiction. What matters more than the number is whether you receive a written plan identifying the structures, the jurisdictions, the tax treatment, the ongoing compliance obligations before you engage, and your state public policy.
Can an attorney guarantee my assets are protected? No, and an attorney who says otherwise is telling you something useful about their practice. A properly built structure changes the position you negotiate from; it does not make you judgment-proof.
Should I hire a local attorney? Asset protection is largely federal and multi-jurisdictional, so physical proximity matters less than whether the attorney understands the law of the state where you would actually be sued and where your assets sit.
Is it too late if I’ve already been sued? For that claim, largely yes — a transfer now is voidable and can worsen your position. For claims that do not yet exist, fraudulent transfer analysis is creditor-specific and forward planning remains available.
What questions reveal an attorney who isn’t a specialist? Ask them to name cases where asset protection structures failed and explain the defect in each. Anyone who cannot is working from marketing material rather than case law.
Why I Answer These Questions the Way I Do
I spent the early part of my career on the plaintiff’s side of civil litigation — running discovery, tracing assets, taking structures apart to find where a debtor still held what he claimed to have given away.
That is an unusual background for this work, and it shapes the whole approach. Most asset protection is designed from the drafting side. Mine is designed from the collection side, because I know what the questions sound like when the other attorney is asking them under oath.
The structures that came apart in my hands came apart for the same two reasons every time. The debtor still controlled what he claimed to have transferred. Or he built the thing after the claim was already in view.
Neither is fixable once a lawsuit is filed. Both are entirely avoidable before one.
If you are interviewing attorneys, ask all ten of these questions — including of me.
You don’t rise to the level of your income. You fall to the level of your legal structure.
Structure before stress.
📞 For a confidential legal consultation, contact Bradley Legal Corp. at (888) 773-9399, or complete the intake questionnaire at btblegal.com. There is no charge for the consultation.
By: Brian T. Bradley, Esq.
About the Author
Brian T. Bradley, Esq. is a national asset-protection attorney and the founder of Bradley Legal Corp; Co-Counsel of Lodmell & Lodmell; Director of Business Development for the Asset Protection Council; the author of Over Exposed and a former plaintiff-side civil litigator.