If something already happened — a demand letter, an accident, a notice of intent, a conversation with a lawyer that did not go well — read the next section before you do anything else. Not because the news is good, but because the most common first instinct is also the most damaging one.
If nothing has happened yet, you are in the only position where this work does what people think it does, and the rest of this article is written for you.
I spent the early part of my career on the plaintiff’s side of civil litigation in Los Angeles and Orange County. I ran the discovery, took the depositions, and found the seam in structures that were supposed to hold. That is the view this is written from.
Key Points
- Do not move money. A transfer made after a claim is foreseeable is voidable, and it usually makes the underlying case worse.
- Find out what is already protected before you buy anything. Retirement accounts and homestead equity are frequently the largest protected block you own, and identifying them costs nothing.
- An LLC answers one question, not two. It separates the business’s liability from you. It does not stop a personal judgment from reaching what you own.
- Insurance is the first layer and the thinnest one. It pays within limits. Everything above the limit is a personal judgment.
- Where you live decides the answer before anyone looks at your structure.
First, Do Not Move Anything
This is the part I would say to you on the phone before anything else.
Every state has a voidable transactions statute. A transfer made with intent to hinder, delay or defraud a creditor can be unwound — and so can a transfer made without reasonably equivalent value while you were insolvent, with no intent required at all.
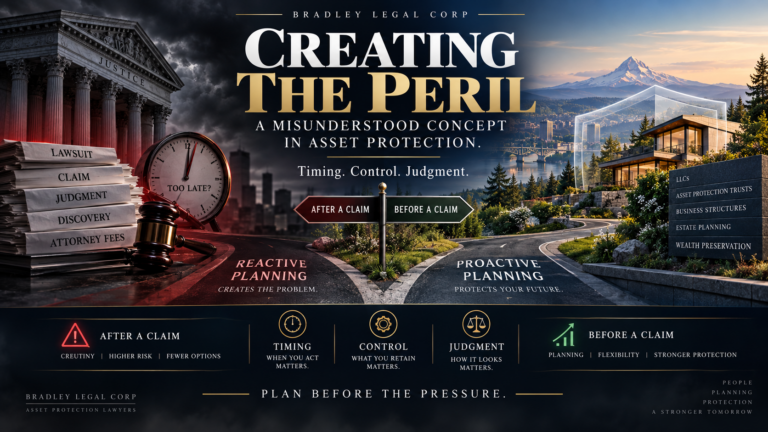
Foreseeability does not begin at service of the complaint. It begins at the adverse outcome. At the demand letter. At the notice of intent. At the conversation where you first thought this could become something.
So the retitling, the quick transfer to your spouse, the LLC you form this weekend — those do not protect the asset. They hand the other side a story about what you did when you got scared, and that story damages you on every contested issue in the case, not just the one about the asset. Juries understand it without needing a statute explained to them.
Doing nothing is almost always better than doing that.
Are You Actually Exposed?
Most people have never actually looked. Take five minutes.
Probably already protected. ERISA-qualified retirement plans carry strong federal anti-alienation protection and are often the single largest protected asset a professional household owns. Home equity, up to your state’s homestead exemption. IRAs and non-ERISA plans, depending heavily on your state.
Almost certainly not protected. Brokerage and investment accounts. Rental property. Business or practice equity. Home equity above the exemption. A second property. Anything held in your own name.
And the exemption number is not a national number. Oregon exempts $158,300 for a single judgment debtor under ORS 18.395. Washington’s is the greater of $125,000 or the county median sale price of a single-family home — which in King County tracked a 2025 median of $940,000 and in Ferry County tracked $199,500. California’s runs on a floor and a ceiling tied to county median price, indexed annually.
If the second list is longer than the first, you have your answer, and the rest of this is for you.
Is It Too Late?
For the claim that already exists, largely yes. That is the honest answer, and anyone telling you otherwise is selling something that will hurt you.
For every claim that does not yet exist — and over a thirty-year career there will be others — planning remains fully available right now. This is where most people get it backwards. They stop planning at the exact moment they finally understand why it matters.
The right move when something is already pending is to defend that case properly, keep your hands off the assets, and build correctly for everything that comes after it.
What to Do, in Order
One. Read your own declarations page. Not the summary the agent emailed. The policy. Find your limits, whether coverage is claims-made or occurrence, whether you have tail coverage, and — if you own anything through an entity — whether that entity is a named insured. This costs nothing and it is the most commonly skipped step.
Two. Identify what is already exempt. Qualified plans, IRAs to your state’s limit, homestead to your state’s number. People routinely pay to protect assets that were never exposed.
Three. Separate operating liability from the assets. Entities formed where the assets actually sit, with real formalities and real separation. This handles the claim that arises inside a business or a property.
Four. If the exposed number justifies it, add a layer that separates ownership, control and jurisdiction — before any of it is tested.
Nothing on that list is exotic. None of it works retroactively.
Four Things People Believe That Are Not True
“My LLC protects me from everything.”
An LLC answers one of two questions. If something happens inside the business — a customer is injured, a tenant is hurt at a property — the entity confines that claim to the entity’s assets. That is inside liability, and it works.
If a judgment is entered against you personally, the LLC does not stop a creditor from reaching your membership interest. That is outside liability, and it turns on your state’s charging order statute and whether that statute makes the charging order the exclusive remedy. Most owners form the entity worried about the second problem and only solve the first.
“My umbrella policy covers it.”
Maybe. A personal umbrella insures persons — the named insureds on the declarations page. If you moved the rental into an LLC, the entity that owns the building and gets sued is not a person.
In Hartford Casualty Insurance Co. v. Fireman’s Fund Insurance Co., 220 F. Supp. 3d 1008 (N.D. Cal. 2016), a wrongful death suit produced a judgment of roughly $8.8 million against an LLC that held title to a Malibu rental. The owner carried a personal umbrella with a $5 million limit. It paid nothing — the carrier refused coverage because the LLC “was not a named insured,” and separately cited exclusions for business activity, business property and workers’ compensation.
Two questions answer this tonight. Who is named as an insured? And what do the business exclusions say?
“I’ll put it in my spouse’s name.”
In a community property state this is worse than useless. California Family Code § 910(a) provides that “the community estate is liable for a debt incurred by either spouse before or during marriage, regardless of which spouse has the management and control of the property and regardless of whether one or both spouses are parties to the debt or to a judgment for the debt.”
It does not matter whose name is on the account. Washington reaches the same place. And the retitling is itself a transfer, so you have created a voidable transaction on top of accomplishing nothing.
“I’ll just hold all the roles myself.”
This is the defect that kills otherwise sound structures, and it is not that you kept too much control. It is that you held roles that should sit in different hands.
In re Samatas (Bankr. N.D. Ill. 2026) is the cleanest domestic example, because every other variable was right. A father created the trust in 1988 for his son — third-party, not self-settled. Spendthrift clause. Even a restricted-trustee provision barring a trustee who was also a beneficiary from making discretionary distributions. Timing was perfect; it predated the claim by thirty years.
It failed anyway, because the son was beneficiary, co-trustee and investment advisor with absolute investment discretion — including the power to direct the trustees to lend trust assets to him. The court described the co-trustee as essentially a nonfunctioning trustee. The spendthrift provision was invalidated, the trust was pierced as his alter ego, and the transfers in were avoided.
Three roles in one person. That alone was enough.
The offshore case everyone cites makes the same point, and it is almost always told wrong. In FTC v. Affordable Media, LLC, 179 F.3d 1228 (9th Cir. 1999) — the Anderson case — the Cook Islands trustee treated the U.S. repatriation order as duress and removed the Andersons as co-trustees. When they appointed their children in their place, the trustee removed the children too. The FTC then litigated in the Cook Islands and lost on every point, with costs awarded against it. The assets were never recovered through litigation.
The structure held. The settlors did not.
They went to jail because they had kept the protector power to certify that no duress existed — which meant a court could say they were able to reverse the freeze they claimed they were powerless to lift. Their inability to comply was self-created. The trust had also been built reactively, after the FTC investigation was already underway.
Keep the two questions apart, because this is where the analysis usually goes wrong. Asset protection answers what a creditor can reach. Civil contempt answers what a court can order you to do. Anderson answered them differently — the creditor reached nothing, and the people were jailed.
One honest limit before anyone over-reads it: that case arose from a federal enforcement action over the proceeds of an investment scheme. Those facts cut against the Andersons everywhere, and they limit how far the case travels against an ordinary private creditor. It is a proof of concept for the jurisdiction and a cautionary tale about drafting — not a promise in either direction. I take the whole case apart here.
So the rule is not that you surrender control of your assets. It is that a settlor should never hold a role that lets a court say you could undo this if you chose to. Investment direction can stay with you. Distribution discretion cannot. And whoever declares a duress event cannot be the person the court is pointing at.
Jurisdiction Is a Pillar, Not a Footnote
Asset protection runs on a short list of pillars, and jurisdiction is one of them. Not background. A pillar — because which state’s law applies decides what a creditor can reach before anyone has looked at your structure.
In asset protection, the issue is about where your assets sit, where you are domiciled, and whose courts would have to cooperate for a creditor to reach you.
California, Oregon, Washington, Florida, New York, Texas, Illinois, New Jersey and Massachusetts are among the largest and most litigious states in the country. Not one of them has enacted a self-settled spendthrift trust statute. In each, the general rule is that a creditor of the settlor may reach the maximum amount that can be distributed to or for the settlor’s benefit — whether or not the trust contains a spendthrift provision.
So if you live in one of them, the “domestic asset protection trust” being sold to you is a trust your own state does not recognize for that purpose. You are not buying protection. You are buying a choice-of-law argument you will have to win at home, in your own state’s courts, against your own state’s public policy.
That is a thinner thing than it sounds like in the brochure, and it is why a structure that works in a seminar often does not survive first contact with a judgment creditor.
Even among states that reach the same result, the mechanism differs sharply. California invalidates the spendthrift restraint but preserves the trust, capping the creditor’s reach at the settlor’s proportionate contribution under Probate Code § 15304. Washington does not bother with the distinction — under RCW 19.36.020 the transfer is simply void as against existing or subsequent creditors. Oregon gets there a third way, under ORS 130.315.
Same answer, three different routes, and the route decides what a creditor actually collects.
Where You Sit Changes What You Need
Physicians and surgeons. The risk is not average, it concentrates. AMA research puts 11% of physicians under 45 as having been sued, against 45.2% of physicians 55 and over — and among OB/GYNs and general surgeons over 55, nearly three in four. The exposure that matters is the verdict above your policy limits, and it is not theoretical. In Trull v. MAG Mutual Insurance Co., No. 3:24-0202 (S.D. W. Va. Nov. 13, 2025), a refused $450,000 settlement offer became a $1.9 million verdict, left over $400,000 outstanding after the carrier paid its limit, and produced a collection action against the physician personally in another state. More on physician exposure
Real estate investors. Two different problems wearing one name — a tenant injured at the property, versus a judgment against you personally that reaches the entity. The first is solved at the property level. The second is not. More on real estate
Business owners. For most owners the largest single exposure is not the business at all. It is the stack of personal guarantees on the line of credit, the equipment financing and the lease — each one a direct claim against you that the entity is irrelevant to. More on personal guarantees
Dentists. Practice ownership concentrates the guarantee problem, and the moment it surfaces is the exit. You sell, the buyer assumes the loan and the lease, everyone shakes hands. Unless the lender and the landlord each signed a written release, you are still on it. The buyer’s promise to you is not a release from them.
E-commerce and Amazon sellers. A product liability claim names the selling entity and, routinely, the individual behind it. Sellers operating as sole proprietors, or through a single-member LLC with one commingled bank account, have very little separation to argue about — and inventory financing and ad spend are usually personally guaranteed on top of it. The structure is ordinary; what is missing is usually the discipline.
FAQs
How do I protect my assets from a lawsuit? In layers, and before a claim exists. Read your insurance first, then identify what is already exempt under your state’s law, then separate business liability from personal assets through properly formed entities, then add a trust layer with jurisdictional separation where the exposed number justifies it. Anything built after a claim becomes foreseeable is a voidable transfer.
Is it too late if I have already been sued? For that claim, largely yes — a transfer now is voidable and typically worsens your position. For future unrelated claims, planning remains available and most people should still do it.
What should I do first if I think I am about to be sued? Nothing with your assets. Defend the claim, read your policy, and do not move, retitle or transfer anything.
Does an LLC protect my personal assets from a lawsuit? It protects you from liability that belongs to the business. It does not stop a personal judgment from reaching your ownership interest, which depends on your state’s charging order statute.
Is umbrella insurance enough to protect me from a lawsuit? It is the right first layer and it is not sufficient. It pays within limits, and it may not respond at all to a claim against an entity you own if that entity is not a named insured.
Can I protect my assets by putting them in my spouse’s name? Not effectively in a community property state like California or Washington, where the community estate answers for a debt incurred by either spouse regardless of title.
Does my state allow asset protection trusts? Most of the largest ones do not. California, New York, Texas, Florida, Illinois, New Jersey and Massachusetts all make a trust you create for your own benefit reachable by your own creditors.
Does any of this hide assets or reduce my taxes? No. Everything I build is fully disclosed when disclosure is required and tax-neutral by design. The purpose is not to disappear. It is to change the position you negotiate from.
The Bottom Line
You cannot build protection after the thing you needed protection from. Every tool here works on one condition — that it existed before the claim did.
The people who come out of this well are not the ones with the most aggressive structure. They are the ones who did ordinary work early: read the policy, found the exemptions, separated what should have been separate, and did it in a year when nothing was happening.
If something is already pending, the best thing you can do today is leave the assets alone and get the defense right. If nothing is pending, this is the window. It does not announce itself, and it closes without warning.
Structure before stress.
📞 For a confidential legal consultation, contact Bradley Legal Corp. at (888) 773-9399, or complete the intake questionnaire at btblegal.com.
By: Brian T. Bradley, Esq. – National Asset Protection Attorney