What the Structure Actually Does — on Timing, Control, Jurisdiction, and Collectibility
A surgeon I’ll call David co-signed a construction loan for his brother’s development company.
He did it in a good year.
The project was funded, the market was strong, and the guarantee felt like paperwork.
Three years later, the project stalled and the lender called the note. It did not chase the brother, who had nothing. It chased David, who had a practice, a brokerage account, two rental buildings, and a home.
David had a revocable living trust. His estate attorney had built it well. It avoided probate and used his exemption efficiently.
It did nothing for him here.
Because it was revocable.
And if you retain the legal power to revoke a trust and reclaim its assets, a creditor generally does not have to pretend that power does not exist.
David is a composite, but I have watched some version of him walk through the door many times.
What matters in that story is not the lawsuit.
It is the calendar.
Every meaningful asset-protection choice David had was gone before the demand letter arrived.
So when you read about Bridge Trust® risks — and there is a growing amount of commentary online — read it carefully.
If you found this article after searching phrases such as “Bridge Trust risks,” “Bridge Trust problems,” “Bridge Trust case law,” or even “Broken Bridge Trust,” that is exactly why this article exists.
I am not going to answer one marketing label with another marketing label.
I am going to address the underlying claims against the structure itself: the governing documents, the statutes, the tax rules, the trustee relationships, the cases, and the practical economics of creditor litigation.
If you are putting eight figures behind a legal structure, pressure-test it first. Now matter what it is.
Ask who controls the assets.
Ask what happens on day one of litigation.
Ask what the offshore trustee is actually obligated to do.
Ask what happens if that trustee cannot serve.
Ask how the trust is classified for tax purposes.
Ask which jurisdiction’s law matters when a creditor actually tries to collect.
And ask what the case law really says.
Skepticism is the correct posture.
I would rather earn a client who arrived skeptical.
But criticism has to describe the thing it is criticizing. Otherwise it’s just marketing content.
That is where much of the current commentary breaks down — not necessarily because the critics misunderstand basic asset-protection law, but because they are applying real principles to a structure built differently than they describe.
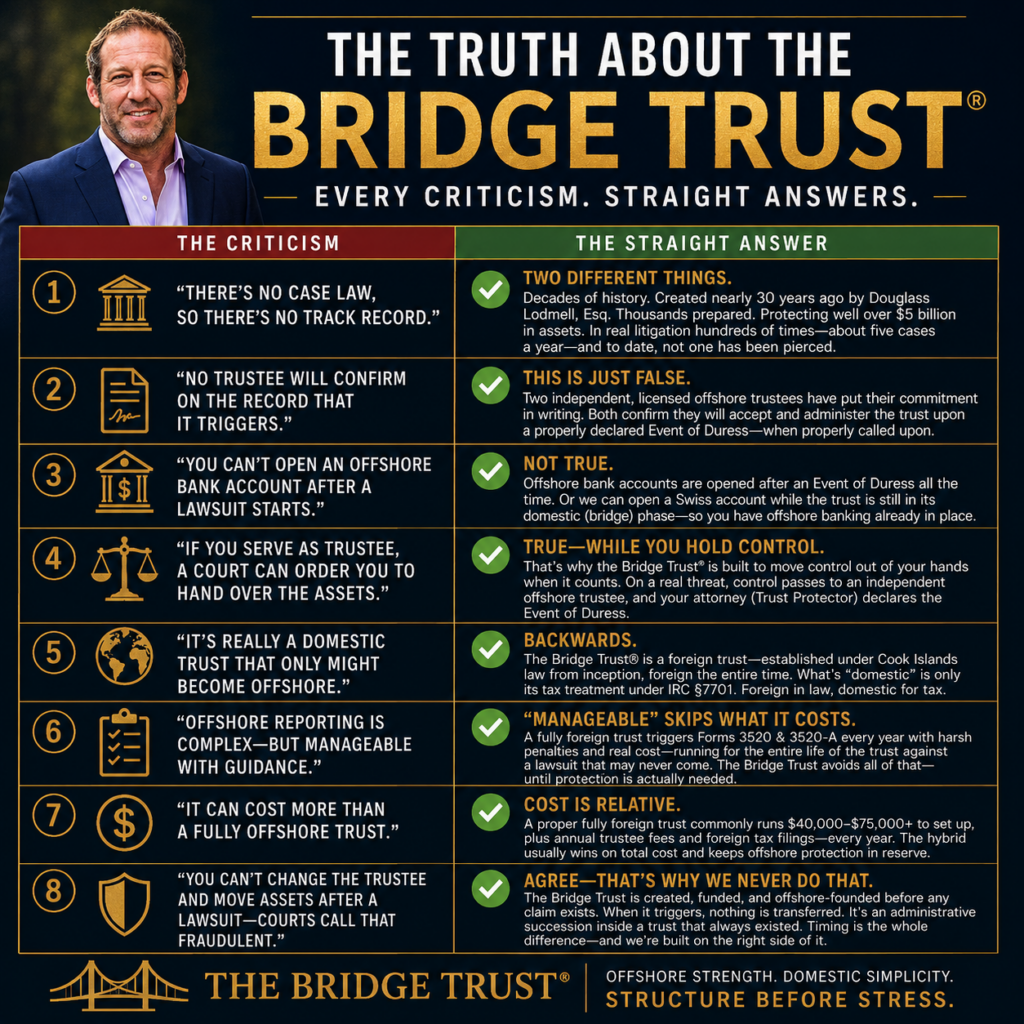
Eight criticisms circulate.
I will answer all eight.
But they are not really eight separate problems.
They are four questions wearing eight hats, and they are the same four questions I apply to every asset-protection plan I build:
Timing. Control. Jurisdiction. Collectibility.
First, one distinction before I start.
Nearly every misunderstanding downstream traces back to it.
The Two Tracks
A trust’s legal character and offshore architecture and its U.S. federal tax classification are different questions governed by different bodies of law.
The Bridge Trust® is built on that distinction.
Not around it.
Track One: Legal Character and Offshore Architecture
The Bridge Trust® is registered in a selected offshore trust jurisdiction at formation — typically the Cook Islands, Nevis, or Belize depending on the structure — with the offshore trustee relationship built into the architecture from the outset.
The offshore registration is not something created for the first time when litigation arrives.
The offshore trustee is not supposed to be found during a crisis.
That foreign legal architecture exists beforehand.
Track Two: U.S. Federal Tax Classification
Separately, the trust’s ordinary U.S. administration is deliberately structured to qualify as a domestic trust for federal tax purposes under 26 U.S.C. §7701(a)(30)(E).
Treasury Regulation §301.7701-7 implements that rule through two requirements commonly called the Court Test and Control Test:
- A U.S. court must be able to exercise primary supervision over administration of the trust.
- One or more U.S. persons must control all substantial decisions of the trust. (Legal Information Institute)
The Bridge Trust instrument is structured to satisfy both during ordinary administration.
Primary U.S. supervision sits in Nevada.
Primary control sits with U.S.-person trustees and a U.S.-person Protector.
Nevada is not an accidental choice.
Nevada recognizes self-settled spendthrift trusts under NRS Chapter 166. California takes a very different approach: California Probate Code §15304 generally makes a restraint on a settlor-beneficiary’s interest ineffective against the settlor’s creditors. (Nevada Legislature)
For a California client, that distinction matters.
So when someone says:
“The Bridge Trust is domestic.”
the correct response is another question:
Domestic for what purpose?
If we are talking about its ordinary U.S. federal tax classification, yes.
That is intentional.
That is the design.
If someone takes that tax classification and uses it to claim there was no pre-existing offshore legal architecture beforehand, that is a completely different proposition.
And that question is answered by the trust’s offshore registration and governing architecture — not by the Internal Revenue Code.
The two tracks run in parallel. They do not take turns.
Understanding that distinction resolves a surprising number of the criticisms that follow.
Pillar One: Timing
Timing decides whether anything else matters.
Nearly every asset-protection failure I have studied is a timing failure wearing a costume.
Criticism #1: “You Can’t Open an Offshore Bank Account After a Lawsuit Starts.”
This one is simply wrong, and I want to be precise about why, because the error is instructive.
A bank deciding whether to onboard a client is running a compliance analysis, not a creditor analysis. It cares about source of funds, sanctions exposure, know-your-client documentation, and reputational risk. A pending civil complaint is not disqualifying, and in practice it rarely moves the needle.
Accounts get opened after an Event of Duress routinely. That is not a theoretical position — it is ordinary administration.
Now the honest caveat. Criminal conduct, money laundering, sanctions exposure, or an unusually high public profile can change a bank’s answer.
There is also a proactive version for clients who would rather not test any of this. The account can be opened while the trust is still in its domestic tax phase — a Swiss account, funded with securities, sitting in place long before anything happens. Reporting in that posture is FBAR (FinCEN Form 114) and FATCA (Form 8938), not Forms 3520 and 3520-A. Substantially lighter, and the banking is already done.
What I do agree with is a different proposition, and I address it below: do not build the structure after the claim arises. That is a real rule.
FBAR and Form 8938 are reporting regimes applicable to specified foreign financial accounts/assets, while Form 3520-A is specifically an annual foreign-trust reporting form for a foreign trust with a U.S. owner. (Taxpayer Advocate Service)
Criticism #2: “You Can’t Change the Trustee and Move Assets After a Lawsuit Starts. That’s a Fraudulent Transfer.”
The rule is right. The description of the structure is not.
If someone calls me after a verdict asking how to move everything offshore, I decline.
Anyone selling the opposite is selling a problem.
The criticism assumes this sequence:
Claim arises → trust is created → assets move offshore.
That sequence is exactly what this structure is built to avoid.
That is the sequence that raises fraudulent-transfer and intent problems.
The foreign registration exists from formation.
And the instrument makes that concept operative rather than decorative.
The Bridge Trust agreement contains provisions allowing governing law and administration to relate to the jurisdiction in which the trust was previously registered rather than treating the creditor event as the date the foreign architecture suddenly came into existence.
That distinction matters because offshore fraudulent-disposition rules generally measure their limitations periods from settlement or disposition dates, not from the later date on which a creditor discovers that protection exists.
So on a properly declared Event of Duress, the premise is not: new trust, new conveyance, new asset-protection plan.
The premise is: same pre-existing trust, with control and administration changing inside an architecture that was already established.
And the trust’s §7701 tax classification changes as the Court and Control Tests cease to be satisfied.
An Event of Duress does not create the protection. It changes how existing protection is administered.
The actual Bridge Trust documents reinforce the importance of pre-claim planning. The client instructions expressly warn that transfers must comply with fraudulent-transfer and voidable-transaction law and state that the structure is not designed to hinder existing creditors.
What do the Indiana Investors cases actually teach?
The cases critics cite make the timing point better than I can.
In Indiana Investors, LLC v. Hammond-Whiting Medical Center and Indiana Investors v. Fink, courts entered asset-freeze orders.
No court pierced a Bridge Trust®.
No court invalidated Cook Islands trust law.
No court reached a Bridge Trust offshore trustee.
The courts restrained people and assets that remained subject to domestic control.
That is a timing and control lesson.
And I accept it completely.
It is also worth keeping the evidentiary standard consistent: both are unpublished trial-court matters. If unpublished trial-court orders count when they are offered as criticism, they cannot suddenly become irrelevant merely because they do not involve the Bridge Trust itself.
Pillar Two: Control
Control is what a court can actually reach.
Jurisdiction over a person becomes extraordinarily important when that person possesses authority to command the property a creditor wants.
Criticism #3: “If You Serve as Trustee, a Court Can Order You to Hand Over the Assets.”
Yes. I agree without qualification.
If you are within a U.S. court’s jurisdiction and hold legal authority over property, that court may order you to exercise it.
Refusing can lead to contempt.
This is not a weakness in the criticism.
It is a foundational principle of asset-protection law, and any planner who waves it off is asking the client to bear the consequences of that mistake.
The real question is:
What does your control look like when a serious threat actually arrives?
A properly structured Bridge Trust® is designed so that the person subject to U.S. compulsion — the client — does not continue to hold the same relevant authority at that moment.
That is why the roles are divided among the grantor, domestic trustee, independent Protector, and Special Successor Trustee.
The separation is not ceremony.
It is the product.
The current trust instrument makes the Protector’s role concrete. Upon declaration of an Event of Duress, certain retained grantor powers are suspended, distributions and administrative decisions become restricted, and the Protector receives authority to appoint or replace trustees, including the Special Successor Trustee.
What Anderson Actually Teaches
This is also how FTC v. Affordable Media, LLC, 179 F.3d 1228 (9th Cir. 1999) — commonly called the Anderson case — should be read.
The Andersons remained co-protectors of their offshore trust. The Ninth Circuit ultimately held that the district court did not abuse its discretion in rejecting their claimed impossibility defense and holding them in contempt. (Justia Law)
The lesson I take from Anderson is not that foreign jurisdiction is meaningless.
It is that:
Retained control and self-created impossibility can destroy the defense.
That is an argument for doing the control analysis carefully.
Not for skipping it.
Criticism #4: “Your Trust Is Guaranteed to Trigger” / “No Offshore Trustee Will Confirm That It Accepts.”
These are actually two different claims.
I reject the first one on my own side.
Nothing here should be marketed as an automatic mechanical trigger.
And that is deliberate.
The governing instrument itself says that declaration of an Event of Duress does not automatically change situs, governing law, or trustee structure. Instead, it gives the independent Protector a menu of protective options based upon the actual threat.
The Bridge Trust® is not supposed to be a self-executing machine that fires blindly the instant a court takes some action.
It requires human judgment.
I would not want it otherwise.
A structure that mechanically reacts to judicial action without independent fiduciary judgment invites an entirely different level of scrutiny.
The Protector’s role is to evaluate the threat and determine what response is appropriate.
What About the Offshore Trustee?
The demand circulating online is that an offshore trust company appear on video and promise that it will serve.
I will take a written commitment from a regulated fiduciary over a promotional video every time.
And those written commitments exist.
Southpac’s Cook Islands trustee states that it has served as designated Special Successor Trustee for the Bridge Trust® for more than twenty years, across hundreds of Bridge Trusts, and that during that period it has never refused an appointment when properly called upon under the trust agreement.
A separate written commitment from Lugano Dame states that, after completing its due diligence and accepting appointment as Special Successor Trustee, it commits to accept and perform the duties of trustee following a properly declared Event of Duress, subject to the stated conditions.
Both commitments are qualified. Both are in writing.
And I will say so plainly because a critic who reads them will say it otherwise.
No licensed trustee anywhere can contract in advance to ignore:
- anti-money-laundering requirements;
- sanctions regimes;
- know-your-client obligations;
- source-of-funds requirements;
- criminal law; or
- its fiduciary duties.
Those conditions apply to a conventional fully foreign trust too.
They are not unique defects in the Bridge Trust.
They are the consequences of using a regulated fiduciary rather than Uncle Bob with a mailbox.
Could a designated trustee become unwilling or unable to serve in a particular circumstance?
Yes.
The instrument assumes that possibility.
And it expressly gives the Protector authority to appoint a replacement Special Successor Trustee if necessary.
That clause is not the vulnerability.
It is the redundancy.
The strength was never that refusal is metaphysically impossible.
The strength is that the structure does not depend on pretending impossibility exists.
Due diligence occurs beforehand.
Written commitments exist.
Trustee relationships are maintained rather than discovered in an emergency.
And the Protector has authority to route around a trustee that cannot properly serve.
Single points of failure are what kill structures.
The goal is to eliminate them.
Pillar Three: Jurisdiction
Jurisdiction answers a different question:
Even if a creditor wins, what legal system governs the assets and the people controlling them when collection begins?
Criticism #5: “It’s Really a Domestic Trust That Only Might Become Offshore.”
This is the most consequential misunderstanding in the debate.
It collapses the two tracks into one.
If the description were accurate —
domestic trust → lawsuit → newly created offshore trust → transfer into it
— I would agree with the criticism completely.
That sequence produces exactly the timing problems sophisticated Bridge Trust planning is designed to avoid.
But that is not the architecture being described.
The foreign registration and offshore trustee architecture exist from formation.
The domestic classification operates simultaneously as a federal tax result under §7701 and Treas. Reg. §301.7701-7. (Legal Information Institute)
One trust. Two analyses. At the same time.
This is also why the language in tax-oriented trust materials has to be read in context.
The Bridge Trust’s tax advisory describes the trust as domestic before trigger and foreign afterward because that document is explaining U.S. tax reporting treatment. It separately explains that once foreign classification applies, additional foreign-trust reporting such as Forms 3520 and 3520-A becomes relevant.
That language is about tax posture.
It does not answer the separate question of when the offshore legal architecture and registration were put in place.
And No, the Bridge Trust Is Not Simply a DAPT
A Domestic Asset Protection Trust rests on the law of a U.S. state.
That introduces questions involving:
- choice of law;
- situs;
- retained control;
- public policy;
- bankruptcy;
- federal supremacy; and
- enforceability outside the DAPT state.
California and Nevada illustrate the problem clearly.
Nevada provides statutory recognition of self-settled spendthrift trusts under NRS Chapter 166. California Probate Code §15304 generally refuses to honor a spendthrift restraint against the settlor’s own creditors when the settlor remains a beneficiary. (Nevada Legislature)
United States v. Huckaby
United States v. Huckaby, No. 2:23-cv-00587-DAD-JDP (E.D. Cal. Mar. 2, 2026) illustrates the jurisdictional problem.
The case involved a Nevada self-settled spendthrift trust holding an interest in California real property. The federal court allowed enforcement of the federal judgment lien against the debtor’s interest, applying the law associated with the situs of the California real estate rather than allowing Nevada spendthrift law to dictate the creditor result. (Leagle)
It is a federal district-court decision.
The trust involved the same people occupying multiple roles as settlors, trustees, and beneficiaries, and the asset at issue sat in California.
I read Huckaby as support for the importance of the Bridge Trust design principles, not as an argument against them.
The lesson is that relying exclusively on the statute of another U.S. state does not make questions of situs, creditor law, and federal enforcement disappear.
The answer to a jurisdiction problem cannot simply be “choose a friendlier domestic statute and hope everybody else honors it.”
Criticism #6: “Offshore Reporting Is Complex — But Manageable With Proper Guidance.”
Let me be clear:
I am not opposed to fully foreign trusts.
They are powerful.
For some clients, I recommend going fully foreign from day one, and I will continue doing so.
In those circumstances, we will draft a fully foreign asset-protection trust.
My disagreement is narrower.
It is with the suggestion that the added compliance burden does not matter because a good CPA can handle it.
Of course a competent CPA can handle it.
That was never the question.
A foreign trust with a U.S. owner can implicate the reporting regime under IRC §6048, including Forms 3520 and 3520-A. The IRS’s current Form 3520-A instructions expressly state that a foreign trust with a U.S. owner must file Form 3520-A so the U.S. owner can satisfy the annual reporting requirements of §6048(b). (IRS)
And §6677 sets the stakes.
Under §6677(a), certain failures involving §6048(a) or (c) carry an initial penalty equal to the greater of $10,000 or 35% of the gross reportable amount.
For the foreign-trust owner reporting obligation under §6048(b), §6677(b) substitutes a 5% rate. (Legal Information Institute)
So the question is not:
Can the forms be prepared?
The question is:
What compliance burden, professional cost, and penalty exposure are you choosing to carry — and for how long?
Five calm years?
Twenty?
Thirty?
A lifetime without a serious creditor claim?
The Bridge Trust proposition is that a client should not necessarily have to shoulder full foreign-trust operational treatment during every ordinary year merely to keep offshore jurisdictional protection available if it is ever genuinely needed.
Financing Is Part of the Cost Too
In my experience placing clients with conventional lenders, there is another cost that rarely gets raised.
Foreign ownership can create friction with underwriting systems built around familiar U.S. borrowers, guarantors, entities, and ownership chains.
That is my professional judgment from practice, not a universal rule.
It does not mean financing is impossible.
But friction has an economic cost.
I had a commercial real-estate investing client with a fully foreign Cook Islands trust whose regular lender refused to lend to them simply because of the fully foreign trust ownership.
Sophisticated clients should price that too.
Pillar Four: Collectibility — The Bridge Trust Risk Nobody Prices
Collectibility is the pillar nobody markets.
It is also the pillar that often determines how litigation actually ends.
A rational creditor ultimately has to price collectibility.
Obtaining a judgment and collecting a judgment are not the same economic event.
A plaintiff’s lawyer evaluating settlement has to ask:
- What can actually be reached?
- At what cost?
- In what jurisdiction?
- Through what enforcement process?
- How long will collection take?
- What legal uncertainty remains?
- How much additional money must be spent before recovery occurs?
That changes settlement economics.
Criticism #7: “There’s No Bridge Trust Case Law, So There’s No Track Record.”
Case law and operating history are different things.
Published opinions are not a database of every structure ever challenged.
They are the residue of disputes that progressed far enough to produce an accessible judicial decision.
Many asset-protection disputes never get there.
They settle.
Creditors re-price collection.
Litigation economics change.
Claims resolve.
No court publishes an opinion announcing:
“The debtor’s asset-protection plan worked exactly as intended and therefore the parties settled.”
That is generally not how reported case law gets created.
And there is a logical problem inside the criticism.
Some of the same commentary arguing that the Bridge Trust lacks a track record because there are no reported cases also argues that properly established offshore trusts have essentially no reported failures on the merits — and offers that absence as evidence of offshore strength.
I agree that an absence of reported failures can be relevant.
But it has to mean the same thing both times.
You cannot say:
“No reported failures proves offshore trusts work.”
and then say:
“No reported failures proves the Bridge Trust has no record.”
Those are opposite interpretations of the same evidentiary fact.
There is a similar tension in the cases offered against hybrid planning.
The affirmative examples most frequently cited include unpublished trial-court freeze orders.
If unpublished trial-court orders count as meaningful evidence when they support the criticism, they cannot cease to count merely when the factual differences become inconvenient.
The Bridge Trust® platform reports approximately three decades of use across thousands of clients, with the Special Successor Trustee mechanism having been used repeatedly.
That is platform history, and I attribute it as such.
It is not a representation about my personal caseload.
It is not a promise about your result.
And it is certainly not a guarantee.
Prior results never guarantee future outcomes, and no ethical attorney should tell a client otherwise.
The case I would want to see is straightforward:
A Bridge Trust® properly established and fully funded before the creditor problem arose, followed through the actual Bridge Trust structure, and then pierced on the merits.
I am not aware of one.
I have repeatedly asked critics to identify one.
Nobody has yet.
That is a statement about the record as I understand it.
It is not a warranty.
Criticism #8: “It Can Cost More Than a Fully Offshore Trust.”
Sometimes the initial invoice may be higher.
That does not answer the economic question.
Compare total cost of ownership:
- planning;
- offshore trustee fees;
- tax compliance;
- accounting;
- administration;
- banking;
- valuations where applicable;
- financing friction;
- and ongoing professional support.
Then compare those costs across:
five years, ten years, twenty years, or thirty years.
That is the number that matters.
And it changes depending on the client.
This is not an argument that the cheapest structure wins.
It never does.
A structure that fails when needed can become the most expensive thing you ever bought.
But the reverse is also true.
Carrying a more burdensome structure for thirty years has a real economic cost, and pretending otherwise distorts the comparison.
The goal is the right amount of protection for the client’s actual risk profile, assets, goals, lifestyle, and tolerance for complexity.
For some clients, a fully foreign trust wins that analysis.
For others, the Bridge Trust does.
For another client, a DAPT may be entirely appropriate.
I have recommended all three.
Asset protection should not be ideology. It should be risk engineering.
Apply the Four-Pillar Test to Your Own Plan
You can run almost any asset-protection strategy through these four questions.
It takes ten minutes and will tell you more than most marketing materials.
1. Timing
Was the structure built before the creditor problem existed?
If it was created reactively after the claim matured, most of the sophisticated drafting in the world may not save it.
2. Control
On the worst day of your financial life, who can the judge order to move your assets?
If the practical answer is still you, then you personally own that risk.
The paperwork does not change reality.
3. Jurisdiction
What legal system governs when the creditor actually attempts collection?
Does the plan depend entirely on one U.S. state’s statute surviving another state’s public policy, the situs of the property, federal law, or bankruptcy?
Huckaby is a useful example of what can happen when those assumptions collide.
4. Collectibility
Does the structure materially change what a rational creditor believes it can ultimately collect?
Because that is what changes settlement leverage.
Not the name of the trust.
Not a glossy binder.
And not the theoretical possibility of winning a trial.
Back to David
David’s problem was never the personal guarantee.
It was that he signed it during a good year and did nothing about the exposure while the years were still good.
By the time the lender called the note, the meaningful planning window had largely closed.
That is the point prospective clients often miss.
You do not build serious asset protection because you know a lawsuit is coming.
You build it because you do not know which ordinary decision today becomes the lawsuit three years from now.
A business guarantee.
A commercial real-estate deal.
A professional liability claim.
An accident.
A partnership dispute.
An employee.
A tenant.
A transaction everyone thought was routine.
The lawsuit is unpredictable.
The existence of exposure is not.
So if you are researching Bridge Trust® risks right now, you are doing the right thing at the right time — while your options are still open.
Keep reading.
Read the critics.
Read my responses.
Read the statutes.
Read the cases.
Ask the hard version of every question.
And then make the decision that is best for you.
Because sometimes a simpliar plan is a better fir for you. Sometime it is not.
Frequently Asked Questions About Bridge Trust® Risks
Is the Bridge Trust® a domestic trust or a foreign trust?
Those terms answer different questions in the Bridge Trust architecture.
The trust has offshore legal registration and architecture established at formation. Separately, while its ordinary U.S. administration satisfies the Court Test and Control Test under IRC §7701(a)(30)(E) and Treas. Reg. §301.7701-7, it receives domestic classification for U.S. federal tax purposes. (Legal Information Institute)
The key question is therefore:
Domestic or foreign for what legal purpose?
Is there Bridge Trust® case law?
There does not appear to be a reported judicial opinion specifically adjudicating and piercing a properly established Bridge Trust® on the merits.
That is not the same statement as saying there is no relevant case law.
Cases involving offshore trusts, DAPTs, fraudulent transfers, retained control, contempt, choice of law, and collection all inform the analysis.
The issue is whether a cited case actually involved the Bridge Trust structure being criticized.
Has a Bridge Trust® ever been pierced?
I am not aware of a reported case in which a properly established and timely funded Bridge Trust® was ultimately pierced on the merits.
That is an operating-history statement, not a guarantee of future performance.
Every trust remains dependent on proper timing, funding, administration, facts, and applicable law.
Can the offshore trustee refuse to accept the Bridge Trust?
A licensed fiduciary can never promise to disregard law, sanctions, AML/KYC obligations, or its fiduciary duties.
But the Bridge Trust structure uses pre-designated offshore successor trustees and written commitments rather than waiting until litigation to locate a trustee.
Southpac has stated that its Cook Islands trustee has served in that role for more than twenty years across hundreds of Bridge Trusts and has never refused when properly called upon, subject to normal fiduciary requirements.
The instrument also allows the Protector to appoint a replacement Special Successor Trustee if the named trustee becomes unwilling or unable to serve.
Can an offshore bank account be opened after a lawsuit begins?
A pending civil lawsuit does not automatically answer a bank’s onboarding decision.
The analysis involves compliance, KYC, AML, sanctions, source of funds, reputational risk, and the specific facts.
More importantly, opening an account should not be confused with the timing of the underlying asset-protection structure.
The planning itself needs to be established before the creditor problem.
Does a Bridge Trust® require Forms 3520 and 3520-A?
While the trust satisfies the domestic-trust tests and remains domestically classified for U.S. federal tax purposes, it is not being treated as a foreign trust merely because offshore architecture exists.
If the trust becomes foreign for U.S. tax purposes, foreign-trust reporting requirements can become applicable, including Forms 3520 and 3520-A. The Bridge Trust materials themselves identify those additional reporting requirements after foreign classification occurs.
What happens when a Bridge Trust® “triggers”?
The term “trigger” can be misleading if it suggests a fully automatic mechanism.
The governing instrument provides for an independent Protector to declare an Event of Duress and then exercise protective powers appropriate to the threat.
Declaration alone does not mechanically cause every possible jurisdictional or trustee change. The Protector is given discretion over the appropriate response.
Is triggering a Bridge Trust® a fraudulent transfer?
A fraudulent transfer generally concerns the movement or disposition of property under circumstances in which creditor rights have already arisen.
A properly established Bridge Trust is intended to be created and funded before that point.
The Bridge Trust documents themselves expressly warn against transfers designed to hinder existing creditors.
An Event of Duress is therefore not supposed to be the moment the client first creates the asset-protection plan.
The plan existed before the stress.
The Bottom Line
There is nothing wrong with criticizing the Bridge Trust®.
You should.
You should also pressure-test a fully foreign Cook Islands trust.
You should pressure-test a Nevada DAPT.
You should pressure-test an LLC.
You should pressure-test insurance.
You should pressure-test every significant legal structure you intend to place substantial wealth behind.
Every structure has failure modes.
The useful question is not:
“Can someone invent a theoretical risk?”
Of course they can.
The useful questions are:
What exactly is the claimed failure mode?
Does the criticism describe the structure accurately?
Was the plan established before the claim?
Who controls the assets under duress?
Which jurisdiction governs collection?
What do the actual governing documents say?
What has the offshore trustee actually agreed to?
What reporting and cost burdens exist?
And does the structure materially change collectibility?
That is how sophisticated asset-protection planning should be evaluated.
Not by slogans.
Not by fear.
Not by marketing labels — including “broken.”
By the four pillars:
Timing.
Control.
Jurisdiction.
Collectibility.
If you want those four questions applied to your own facts, schedule a legal consultation before the problem exists.
Structure before stress.
Brian T. Bradley, Esq. – National Asset Protection Attorney


