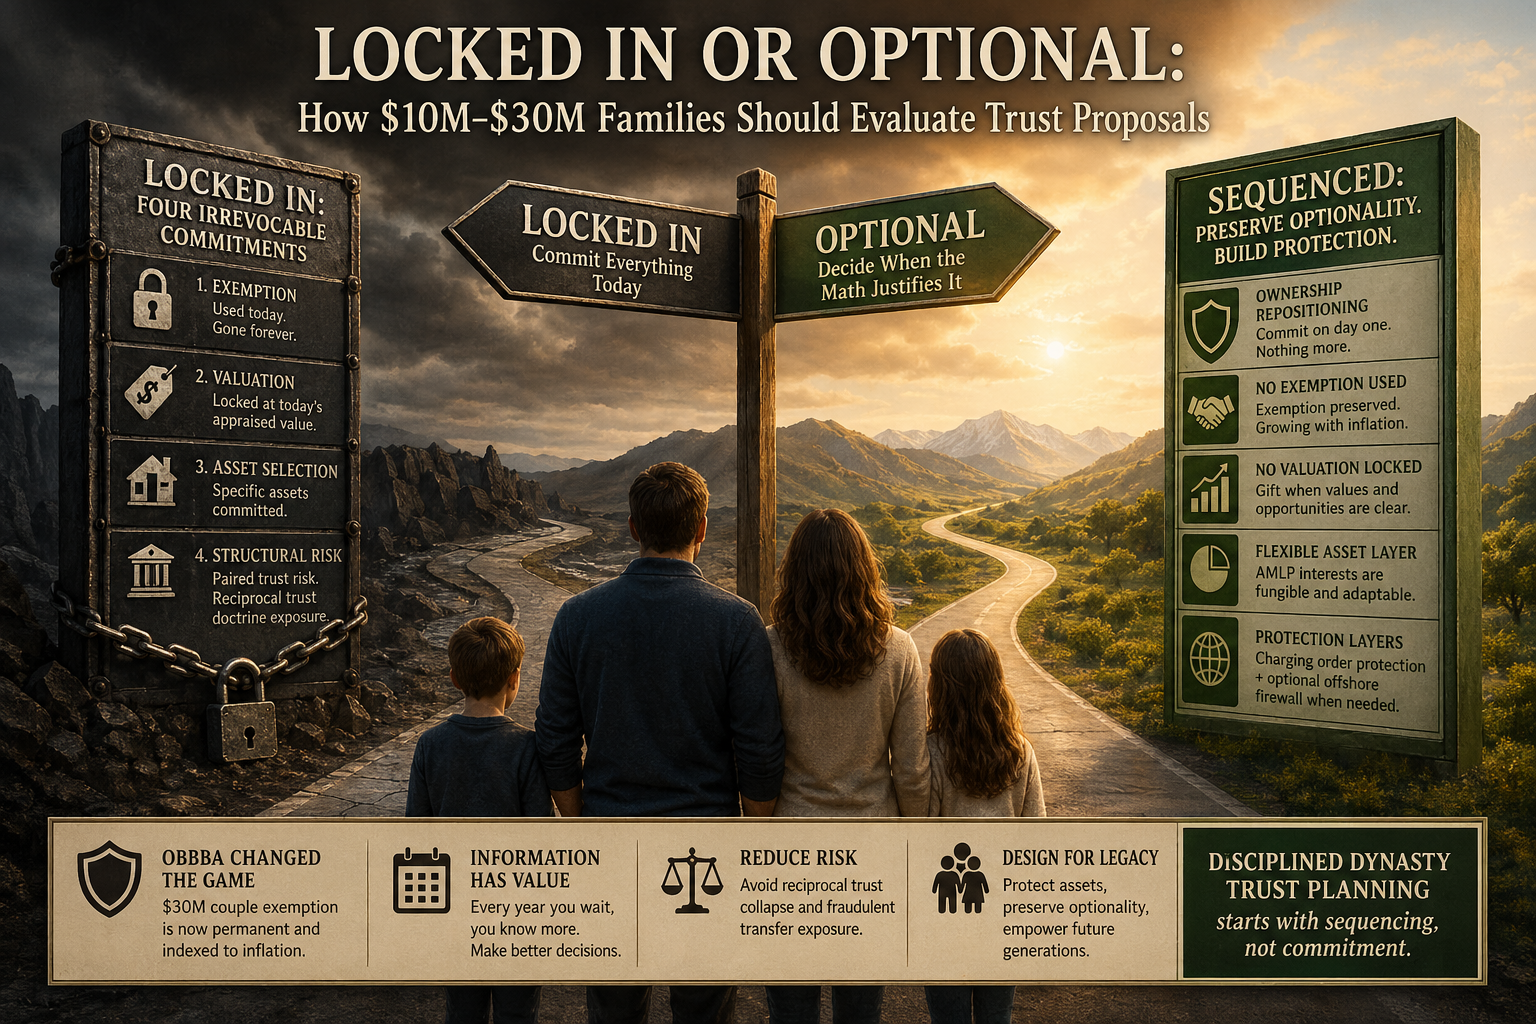
A typical paired-trust gifting structure asks a family to make four irrevocable commitments on the same day: exemption, valuation, asset selection, and structure. Each has consequences that take decades to play out, and almost no one walks the family through what each one costs. With the OBBBA making the exemption permanent, the sunset that justified front-loading all four is gone — which means the case for committing today has to rest on the family’s actual position rather than on a deadline that no longer exists.
Key Points
- Four commitments, one day. Exemption, valuation, asset selection, structure — all irrevocable.
- The cliff is gone. Reducing the exemption now requires new legislation, not automatic expiration.
- Optionality has value when the future is uncertain, and the future is always uncertain.
- Two risks compound the case against premature gifting — reciprocal trust collapse and fraudulent transfer optics.
- But one deadline is real and nobody controls it: GST exemption is not portable, and it disappears at the first death.
- Sophisticated is not the same as correct. The question is whether the structure matches the family’s actual position.
“It Feels Like They’re Being Asked to Commit to a Lot All at Once”
A financial planner I have worked with for years called me last month. One of his clients — a married couple with operating businesses, real estate, and a balance sheet in the $10 million to $30 million range — had just come out of a meeting with a well-known transfer-tax attorney at an AmLaw 200 firm.
The proposal was elegant. Paired Nevada irrevocable trusts. Formula valuation clauses to defend against IRS challenge. Full deployment of the couple’s combined estate tax exemption. A long-term dynasty structure for the grandchildren.
The clients were impressed. The planner was not.
He could not name what was wrong. The firm was respected. The structure was sophisticated. The presenting attorney was confident. But something kept bothering him, and he finally said it the way an experienced advisor says it when his instincts are firing without language yet attached.
“Brian, it feels like they’re being asked to commit to a lot all at once. Can you take a look at this before they sign anything.”
That instinct was correct. And the reason he caught it — and the reason most clients do not — is exactly what almost no one explains to families sitting in those meetings.
What the OBBBA Actually Changed
The exemption is permanent at $15 million per individual and $30 million per couple. The sunset that drove eight years of “use it or lose it” planning is gone. Reducing it now takes affirmative legislation rather than automatic expiration.
On July 4, 2025, Congress enacted the One Big Beautiful Bill Act. It permanently set the federal estate, gift, and generation-skipping transfer tax exemption at $15 million per individual and $30 million per married couple, effective January 1, 2026, indexed to inflation beginning in 2027.
The word that matters is permanent.
Before the OBBBA, the Tax Cuts and Jobs Act exemption was scheduled to sunset at the end of 2025 — dropping by roughly half if Congress did nothing. That sunset was the engine of the entire “use it or lose it” conversation for eight years. Every paired trust pitch, every dynasty deployment, every aggressive front-loaded gift was framed against the cliff.
The cliff is gone. Reducing the exemption now requires new legislation, which is a different political dynamic than letting an existing sunset expire on schedule. It can happen. It is no longer the default.
For families above $30 million, the case to deploy now can be strong — appreciation lock-in, generation-skipping leverage, and political risk are real arguments on the right facts.
For families at or below $30 million, the math is more nuanced. The affirmative case for deploying now has to rest on the family’s specific position — appreciation profile, asset mix, succession timeline, current creditor exposure — rather than on a sunset that no longer exists.
The question is no longer how do we beat the deadline. It is what should we commit to today, and what should we preserve as a decision we can make later when we know more.
The Four Irrevocable Commitments Most Plans Force
Exemption, valuation, asset selection, and structure. All four happen on day one, before the family knows whether any of them will turn out to be the right call. That is what locked in means.
One: exemption
When the gift hits Form 709, the exemption is used. Whatever the family deploys today is gone. They cannot reclaim it if circumstances change, redirect it to a different trust or beneficiary, or defer it to a better moment.
Deploy $20 million of combined exemption this year and two-thirds of lifetime capacity is committed to one decision made on one day.
Two: valuation
The entire point of the formula clause defense — the Wandry, Petter, and McCord line of authority — is to lock in today’s appraised value of the transferred interests.
If the assets double next year, the family captured the gift at the lower number. Good outcome.
If they crash next year, the family used exemption against an inflated value. Bad outcome, with no adjustment available. The gift completed at the appraised figure and the appraisal is on file.
For closely held business interests and concentrated positions, that second scenario is not hypothetical.
Three: asset selection
Specific assets land inside the trust. A 50 percent interest in the operating company. A piece of real estate. A concentrated stock position.
Once the gift is complete, those particular assets are owned by the trust, not the family. Removing, swapping, or unwinding them requires either a substitution power with its own tax mechanics or a modification process that can be expensive, slow, and sometimes impossible.
The family cannot simply decide to sell that property next year and redeploy the proceeds without engaging trust mechanics the structure was not designed to make easy.
Four: structure
The paired trusts exist. Trustee fees are running. The administrative burden is locked in. And the reciprocal trust risk under United States v. Estate of Grace, 395 U.S. 316 (1969) is now baked into the family’s estate plan.
If a court applies the doctrine, the structure can collapse on itself in ways the family did not anticipate when they signed the engagement letter.
Sequencing as Disciplined Planning
Start from a different question: what does the family actually need to do today, and what should they preserve as a decision they can make later?
The architecture that follows from that question executes one commitment on day one. Ownership repositioning. Nothing more.
A foundational dynasty trust is created — irrevocable, drafted as a long-duration trust under Nevada law, which permits a term of up to 365 years under NRS 111.1031, and drafted so that GST exemption capacity is preserved rather than consumed.
That distinction is the whole point. Because funding is not a completed gift, no exemption is allocated at creation and none is used. It remains available — indexed, growing — to be allocated later, on Form 706, when the family actually knows what the assets are worth and what the law says.
One caveat that belongs in every version of this conversation. The GST exemption is not portable between spouses. There is no DSUE equivalent under IRC §2010(c). Allocation is planned around the first death, not the second — exemption unallocated when the first spouse dies is permanently gone, and no later planning recreates it.
The trust holds an Asset Management Limited Partnership organized under Arizona law. Under A.R.S. §29-341, the charging order is the exclusive remedy against a limited partner’s interest, and the section contains no foreclosure provision — an omission that reads as deliberate alongside §29-1044(B), which expressly authorizes foreclosure for Arizona general partnerships. A creditor of a partner gets a charging order against distributions only. No attachment of the underlying interest. No forced liquidation.
The Bridge Trust® holds the AMLP interests. Two independent tax rules operate: the instrument satisfies the court test and control test of Treas. Reg. §301.7701-7 under IRC §7701(a)(30)(E), so the IRS classifies it as domestic, and separately it maintains grantor-trust status under IRC §§671–677, so income is reported on the family’s own return.
The agreement is governed by Nevada law and registered offshore from inception, in both Belize and the Cook Islands — the Belize registration starting the offshore limitation period at day one, and the Cook Islands recognizing the trust as of that original filing date while supplying the pre-committed successor trustee. An independent Trust Protector controls when that offshore capacity activates, by declaring an Event of Duress. Nothing fires automatically.
What is committed, and what is not
Committed on day one: ownership repositioning into the structure.
Not committed: any of the four irrevocable decisions a paired-trust gifting structure forces.
No exemption is used. It sits available, growing with inflation, ready to deploy when the math justifies it.
No valuation is locked in. Appraisals can be obtained over time, with multiple data points across multiple years, when the family actually decides to gift.
No specific assets are permanently committed beyond what is needed to populate the AMLP. LP interests are fungible. The family can sell the underlying real estate, restructure the operating business, or swap one investment for another without engaging mechanics a completed gift would lock in.
And no paired-trust structural risk exists. There is one foundational trust, not two mirror-image trusts. The reciprocal trust doctrine has nothing to uncross.
The Optionality Engine
Because LP interests transfer in fractional amounts, the family retains the ability to implement gifting later, deliberately.
If the exemption drops by future legislation, they deploy. If the asset base grows meaningfully, they deploy on the appreciation. If they want to gift to a specific child or grandchild for a specific purpose, they deploy that fraction. If they want to gift nothing, they do nothing.
The structure supports every outcome.
Every year that passes, the family gets more information — about asset values, legislation, their own circumstances, their heirs, their creditor exposure. That information has economic value, and sequencing lets the family use it when making transfer decisions. The locked-in approach forces every decision before that information exists.
In any other domain this would be obvious. No one would tell a portfolio manager to liquidate every position on day one because prices might fall. No one would tell a buyer to sign every contract before due diligence because the seller might raise the price.
Optionality has positive value when the future is uncertain, and the future is always uncertain.
The Two Risks That Compound Locking In
Reciprocal trust collapse
When two spouses each create substantially similar trusts naming each other as beneficiaries — same year, similar structures, similar timing, similar funding — the framework in Estate of Grace allows the trusts to be uncrossed, treating each spouse as settlor of the trust they actually benefit from.
That collapse converts a third-party-settled structure into a self-settled structure. On California facts, it triggers Cal. Prob. Code §15304‘s anti-self-settled rule, which lets creditors reach what could be distributed to the settlor-beneficiary despite the spendthrift clause.
This is not theoretical, and California courts have applied the analysis to Nevada trusts.
Kilker v. Stillman (Cal. Ct. App. 2012) is frequently cited for the proposition — though it is an unpublished decision, non-citable as precedent under Cal. R. Ct. 8.1115, and it is offered here as illustration rather than authority.
The binding version arrived in 2026. In United States v. Huckaby, No. 2:23-cv-00587-DAD-JDP (E.D. Cal. Mar. 2, 2026), the court allowed Nevada law to govern trust construction but applied California situs law to creditor access against California real property held in the trust. Because the debtors were settlors, trustees, and sole lifetime beneficiaries, §15304 made the spendthrift restraint ineffective and the federal judgment lien attached.
The Nevada governing-law clause did not save the structure.
Fraudulent transfer optics
When a family makes a large gift close in time to any potential claim, the transfer becomes vulnerable under Cal. Civ. Code §3439 et seq., the Uniform Voidable Transactions Act.
The badges of fraud analysis at §3439.04(b) — insider transferee, retention of control, concealment, threat of suit, transfer of substantially all assets — can apply even when the family had no specific creditor in mind. A creditor arising within four years of the transfer can move to set it aside, with a longer outside limit where actual fraud is alleged.
The sequencing approach avoids that exposure entirely. No gift is made at the front end. The family is repositioning ownership into a protected structure, not transferring value out of their estate. There is no fraudulent transfer to attack, because there is no transfer.
When the family does decide to gift later — through fractional LP transfers calibrated to current circumstances — the gifts can be timed and sized to avoid creditor proximity issues.
These two risks compound. A paired-trust structure that gets reciprocal-trust-collapsed and attacked under the UVTA is a double failure. The sequencing structure has neither vulnerability.
The Diagnostic the Family Should Run
Ask the family, not the lawyer: what do you actually know today, and what would you prefer to decide later when you know more?
At $50 million with concentrated growth assets, a clear succession plan, established heirs, and a stable creditor profile — the case for executing aggressively today is strong. Enough capacity, enough appreciation potential, enough certainty about the family’s structure to commit. The locked-in approach makes sense.
At $10 million to $30 million, with operating businesses whose values fluctuate, children whose paths are not yet clear, grandchildren still young, active liability exposure, and no legislative cliff to beat — the case for executing aggressively today is much weaker. The family does not yet have the information needed to make several of those four decisions well.
The question is not whether the proposed structure is sophisticated. The diagrams from AmLaw 200 transfer-tax firms are sophisticated.
The question is whether the structure matches the family’s actual position, exposure profile, and timeline.
Questions to Bring to Your Next Meeting
If you walked out of an estate planning meeting this month with a paired trust proposal in hand:
Why am I being asked to use my exemption today rather than later?
What will I know in three years that I do not know now, and would that change this decision?
If the exemption is permanent and growing with inflation, what is the urgency case for executing today?
What does this structure cost me in optionality if circumstances change?
What does it cost me in protection if a creditor arises before I have completed the gifts?
And one that runs the other direction: if my spouse died next year, would our GST exemption be allocated — or lost?
If the answers do not satisfy you, the proposal may be solving a problem the family does not have while leaving the problem the family does have — operating-business liability, real estate exposure, concentrated wealth — completely unaddressed.
FAQs
Should I use my estate tax exemption now or wait? It depends on estate size, appreciation profile, and tolerance for irrevocable commitment. Above the $30 million couple exemption with rapidly appreciating assets, deployment today often makes sense. At or below it, the case for waiting is usually stronger now that the OBBBA locked the exemption with inflation indexing. Decide on the math, not on urgency that no longer applies.
What did the OBBBA change? It permanently set the federal estate, gift, and GST exemption at $15 million per individual and $30 million per couple, effective January 1, 2026, with indexing from 2027. It eliminated the scheduled sunset. Reducing the exemption now requires new legislation.
Is there any real deadline left? Yes, and it is not legislative. The GST exemption is not portable between spouses. If the first spouse dies without it allocated, that exemption is permanently lost. That deadline is not controlled by Congress or by you.
What is the reciprocal trust doctrine? When two spouses create substantially similar trusts naming each other as beneficiaries, a court can uncross them and treat each spouse as settlor of the trust they benefit from. Estate of Grace, 395 U.S. 316 (1969). The collapse converts a third-party trust into a self-settled one, which California refuses to honor under Prob. Code §15304.
What is the difference between a SLAT, a SLANT, and a Dynasty Bridge Trust®? A SLAT is a grantor trust where one spouse gifts to a trust for the other spouse and descendants. A SLANT is the same structure drafted to be non-grantor for income tax purposes. Both are completed gifts. The Dynasty Bridge Trust® is a layered architecture — a long-duration dynasty trust, an Arizona AMLP for charging-order protection, and offshore capacity that activates on a Protector declaration — funded without a completed gift, which is what preserves the §1014 step-up.
Is my estate too small for sophisticated planning? No estate is too small for asset protection. Operating businesses, real estate, and concentrated investments create liability exposure regardless of size. The question is what kind of planning fits. Below $30 million, transfer-tax-driven gifting often imposes costs — committed exemption, locked valuations, lost optionality — that exceed the benefit.
Can I undo a dynasty trust if I change my mind? Generally not. Irrevocability is what makes it work for transfer tax purposes. Some flexibility exists through trustee discretion, decanting, and protector powers — but the core decisions made at funding are irrevocable. That is exactly why the timing of those decisions is the most important question in the conversation.
What if my advisor’s proposal is from a top firm? Sophisticated is not the same as correct for your situation. The diagrams are excellent. The question is whether the structure matches your actual position — and that is a question about your facts, not about the firm.
The Bottom Line
The instinct that financial planner had on the call was right. A sophisticated structure is not the same as the right structure.
Committing to four irrevocable decisions on the same day, before the family has the information needed to make any of them well, is not disciplined planning. It is the appearance of planning, applied without regard to whether the family’s position requires it.
Disciplined planning starts with sequencing, not commitment — while recognizing the one deadline that is real and that nobody controls.
Structure before stress. And optionality before commitment.
📞 For a confidential legal consultation focused on whether a proposed structure matches your actual exposure profile, asset mix, and family timeline, contact Bradley Legal Corp. at (888) 773-9399, or complete the intake questionnaire at btblegal.com.
By: Brian T. Bradley, Esq. – National Asset Protection Attorney
Not ready to talk yet?
Take my 2-minute Lawsuit Exposure Test
Answer yes or no. You get an exposure score and see where your risk actually comes from.
Take the Lawsuit Exposure Test